Closelook@Hypergrowth
Paid — the Test Bench, the Fibre and Korean Memory. Charged — the Control Plane and American Storage. The Names Into the Fed Week
The tracker's ten best names this week are eleven-twelfths build-out — test equipment, power, photonics, fibre and the CPU makers — and its ten worst are enterprise software, from UiPath to Adobe. Inside — the strongest and weakest sleeves of each AI index on the week and on the year, the flow behind the names that were paid, the two Asian chip markets against the US technology sector, and what the Hypergrowth book did with Micron, Qualcomm, SK hynix, Lumentum and SpaceX on Friday.
Current edition · 2026-09-13
1 · This Week's Action
Where this letter sits, in one line. Sunday's US edition reads the market at index and sector degree; this one reads it at name altitude — which companies the money went into, which it left, and what the flow behind each is doing. The backdrop, one line more: the S&P sold four sessions into a hot inflation print and bought the print, the chips beat the market a second week from under their average, the Nasdaq 100 without its technology stocks turned negative on the year, and the Fed decides on Wednesday with a hike four-fifths priced.
The selection, first — what the tracker paid and what it charged. Across the three AI indices' constituents, the twelve best lines of the tracker's week are eleven build-out names and one operator: Aehr Test +24.2%, Cohu +24.1%, FormFactor +18.8%, Bloom Energy +17.1%, Coherent +15.5%, HPE +14.1%, Corning +14.0%, Nokia +13.9%, AMD +13.1%, Marvell +13.1%, DigitalOcean +12.4%, Intel +12.3%. Test equipment, power, photonics, fibre, the CPU makers — the physical layer, and inside it the parts that are not memory. The twelve worst: Zhipu −26.2%, UiPath −24.5%, Amgen −15.0%, Kingdee −14.9%, Elastic −13.3%, PTC −12.9%, HubSpot −12.4%, Adobe −11.7%, Shopify −11.7%, Money Forward −11.5%, Delta Electronics −11.2%, SailPoint −11.1% — enterprise software in three time zones, one health-care name, one Taiwanese power-supply maker. (The tracker's week is a five-session window; across Labor Day it reaches back to Thursday 3 September, so its name-level moves are wider than the Friday-to-Friday tape the US letter reads.) The medians say the same thing in one row: capex +2.25% with 85 of 126 green; opex −0.30% with 14 of 34; applications −6.13% with 4 of 40. Section 2 has the same cut per index and per sleeve, on the week and on the year; section 6 has what the book did about it on Friday.
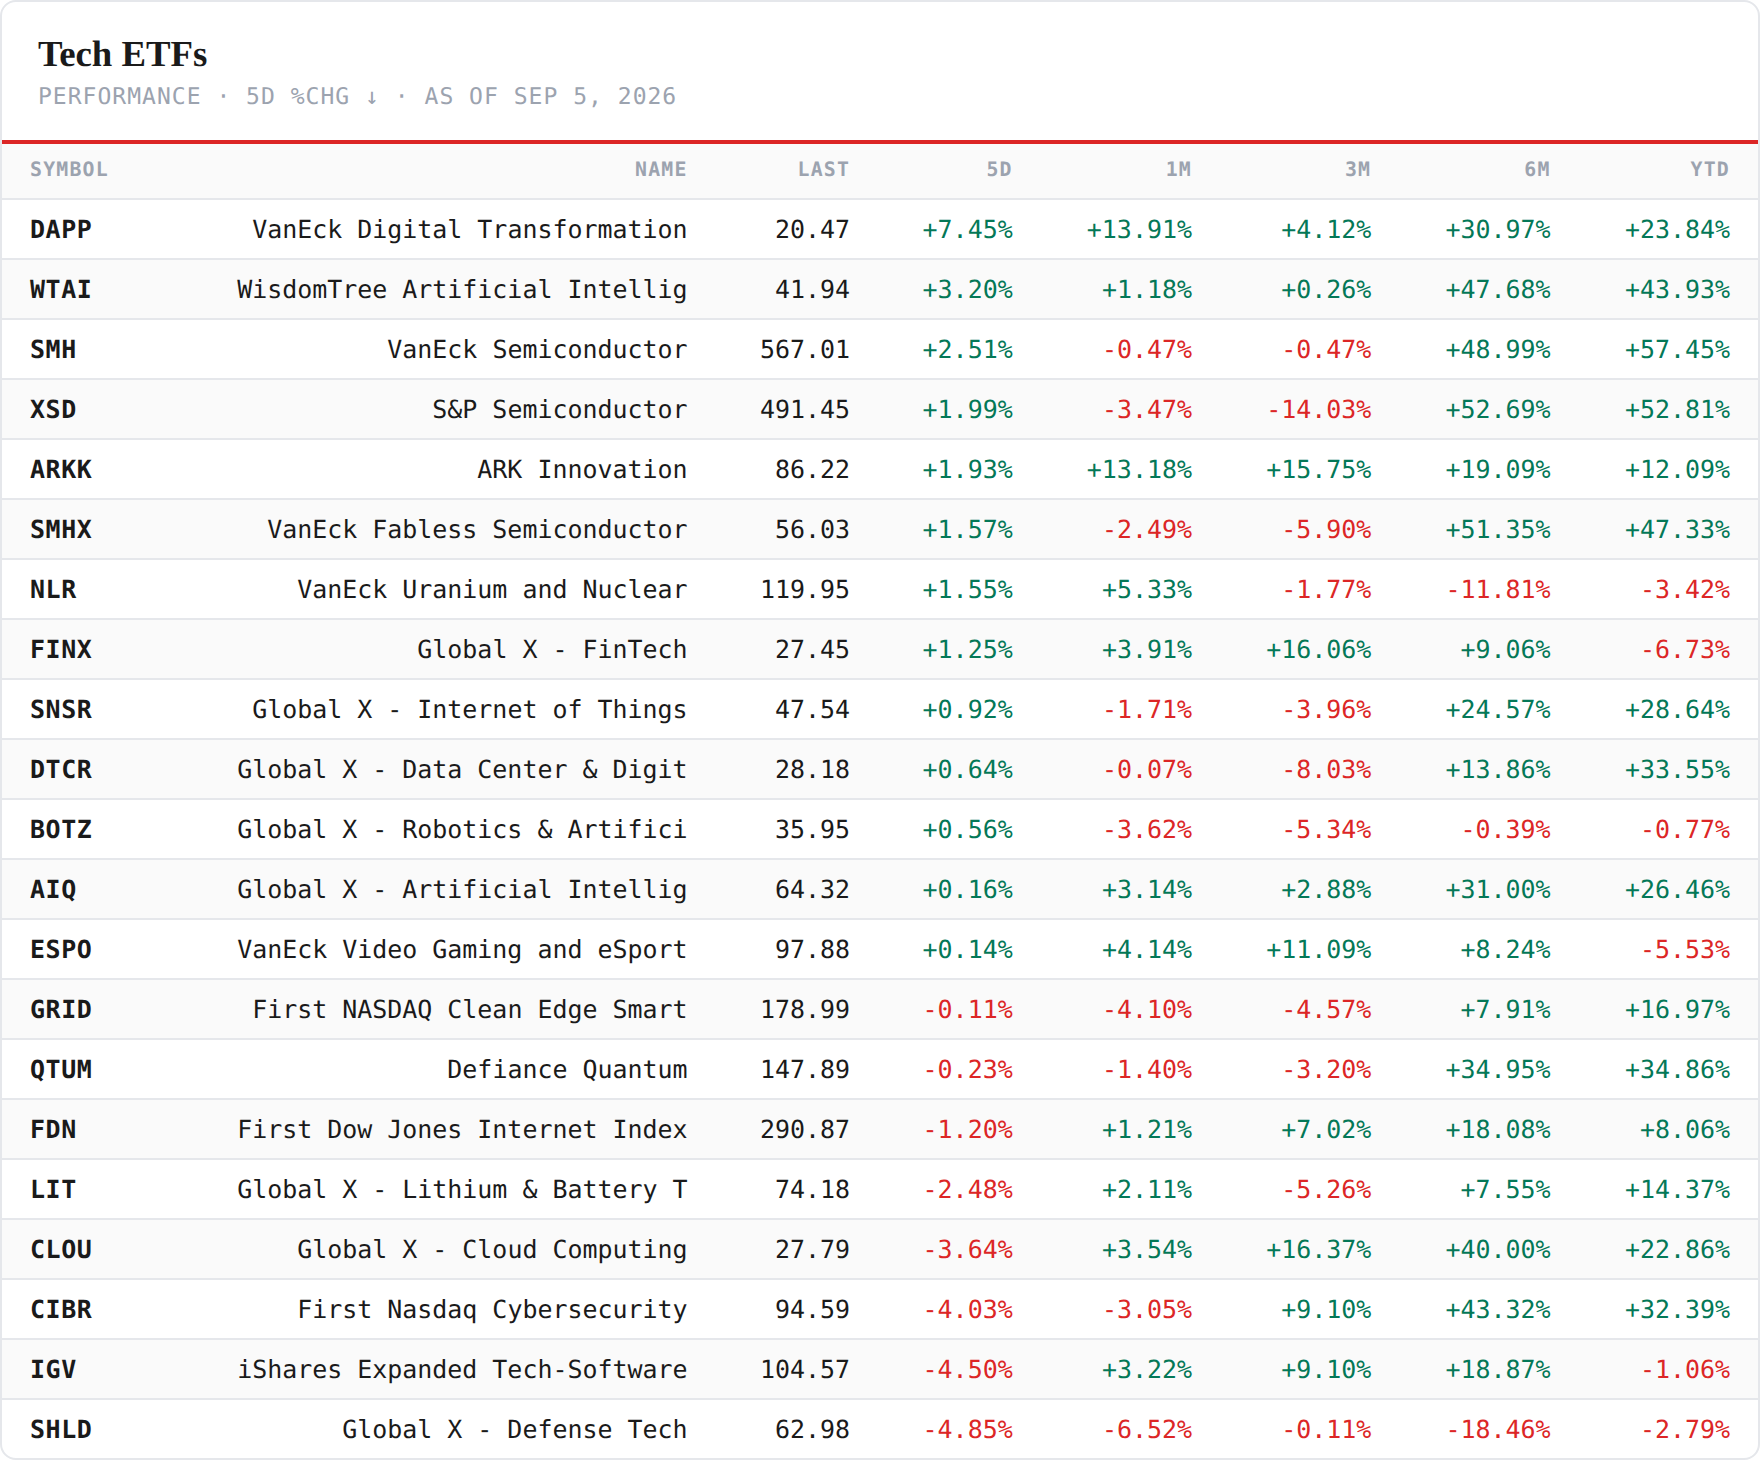
The tech shelf — silicon green, everything else red. Six green lines of twenty-one, five of them chips or the things chips plug into: XSD +2.87%, SMHX +1.18%, the grid fund +1.00%, the internet-of-things fund +0.56%, data centres +0.28%, SMH +0.27%. Fifteen red, led by nuclear −5.61%, fintech −4.74%, lithium −3.63%, ARK −3.06%, software −2.92%, the digital-asset fund −2.69%, cloud −2.37%. Second consecutive week of the inversion, and it narrowed: the semis did not rise much; they did not fall while the index did. The software-to-semis ratio fell 3.18% on the week to 37% above its June 22 low, from 41% — ten percent of the ratio's rise surrendered in two weeks.
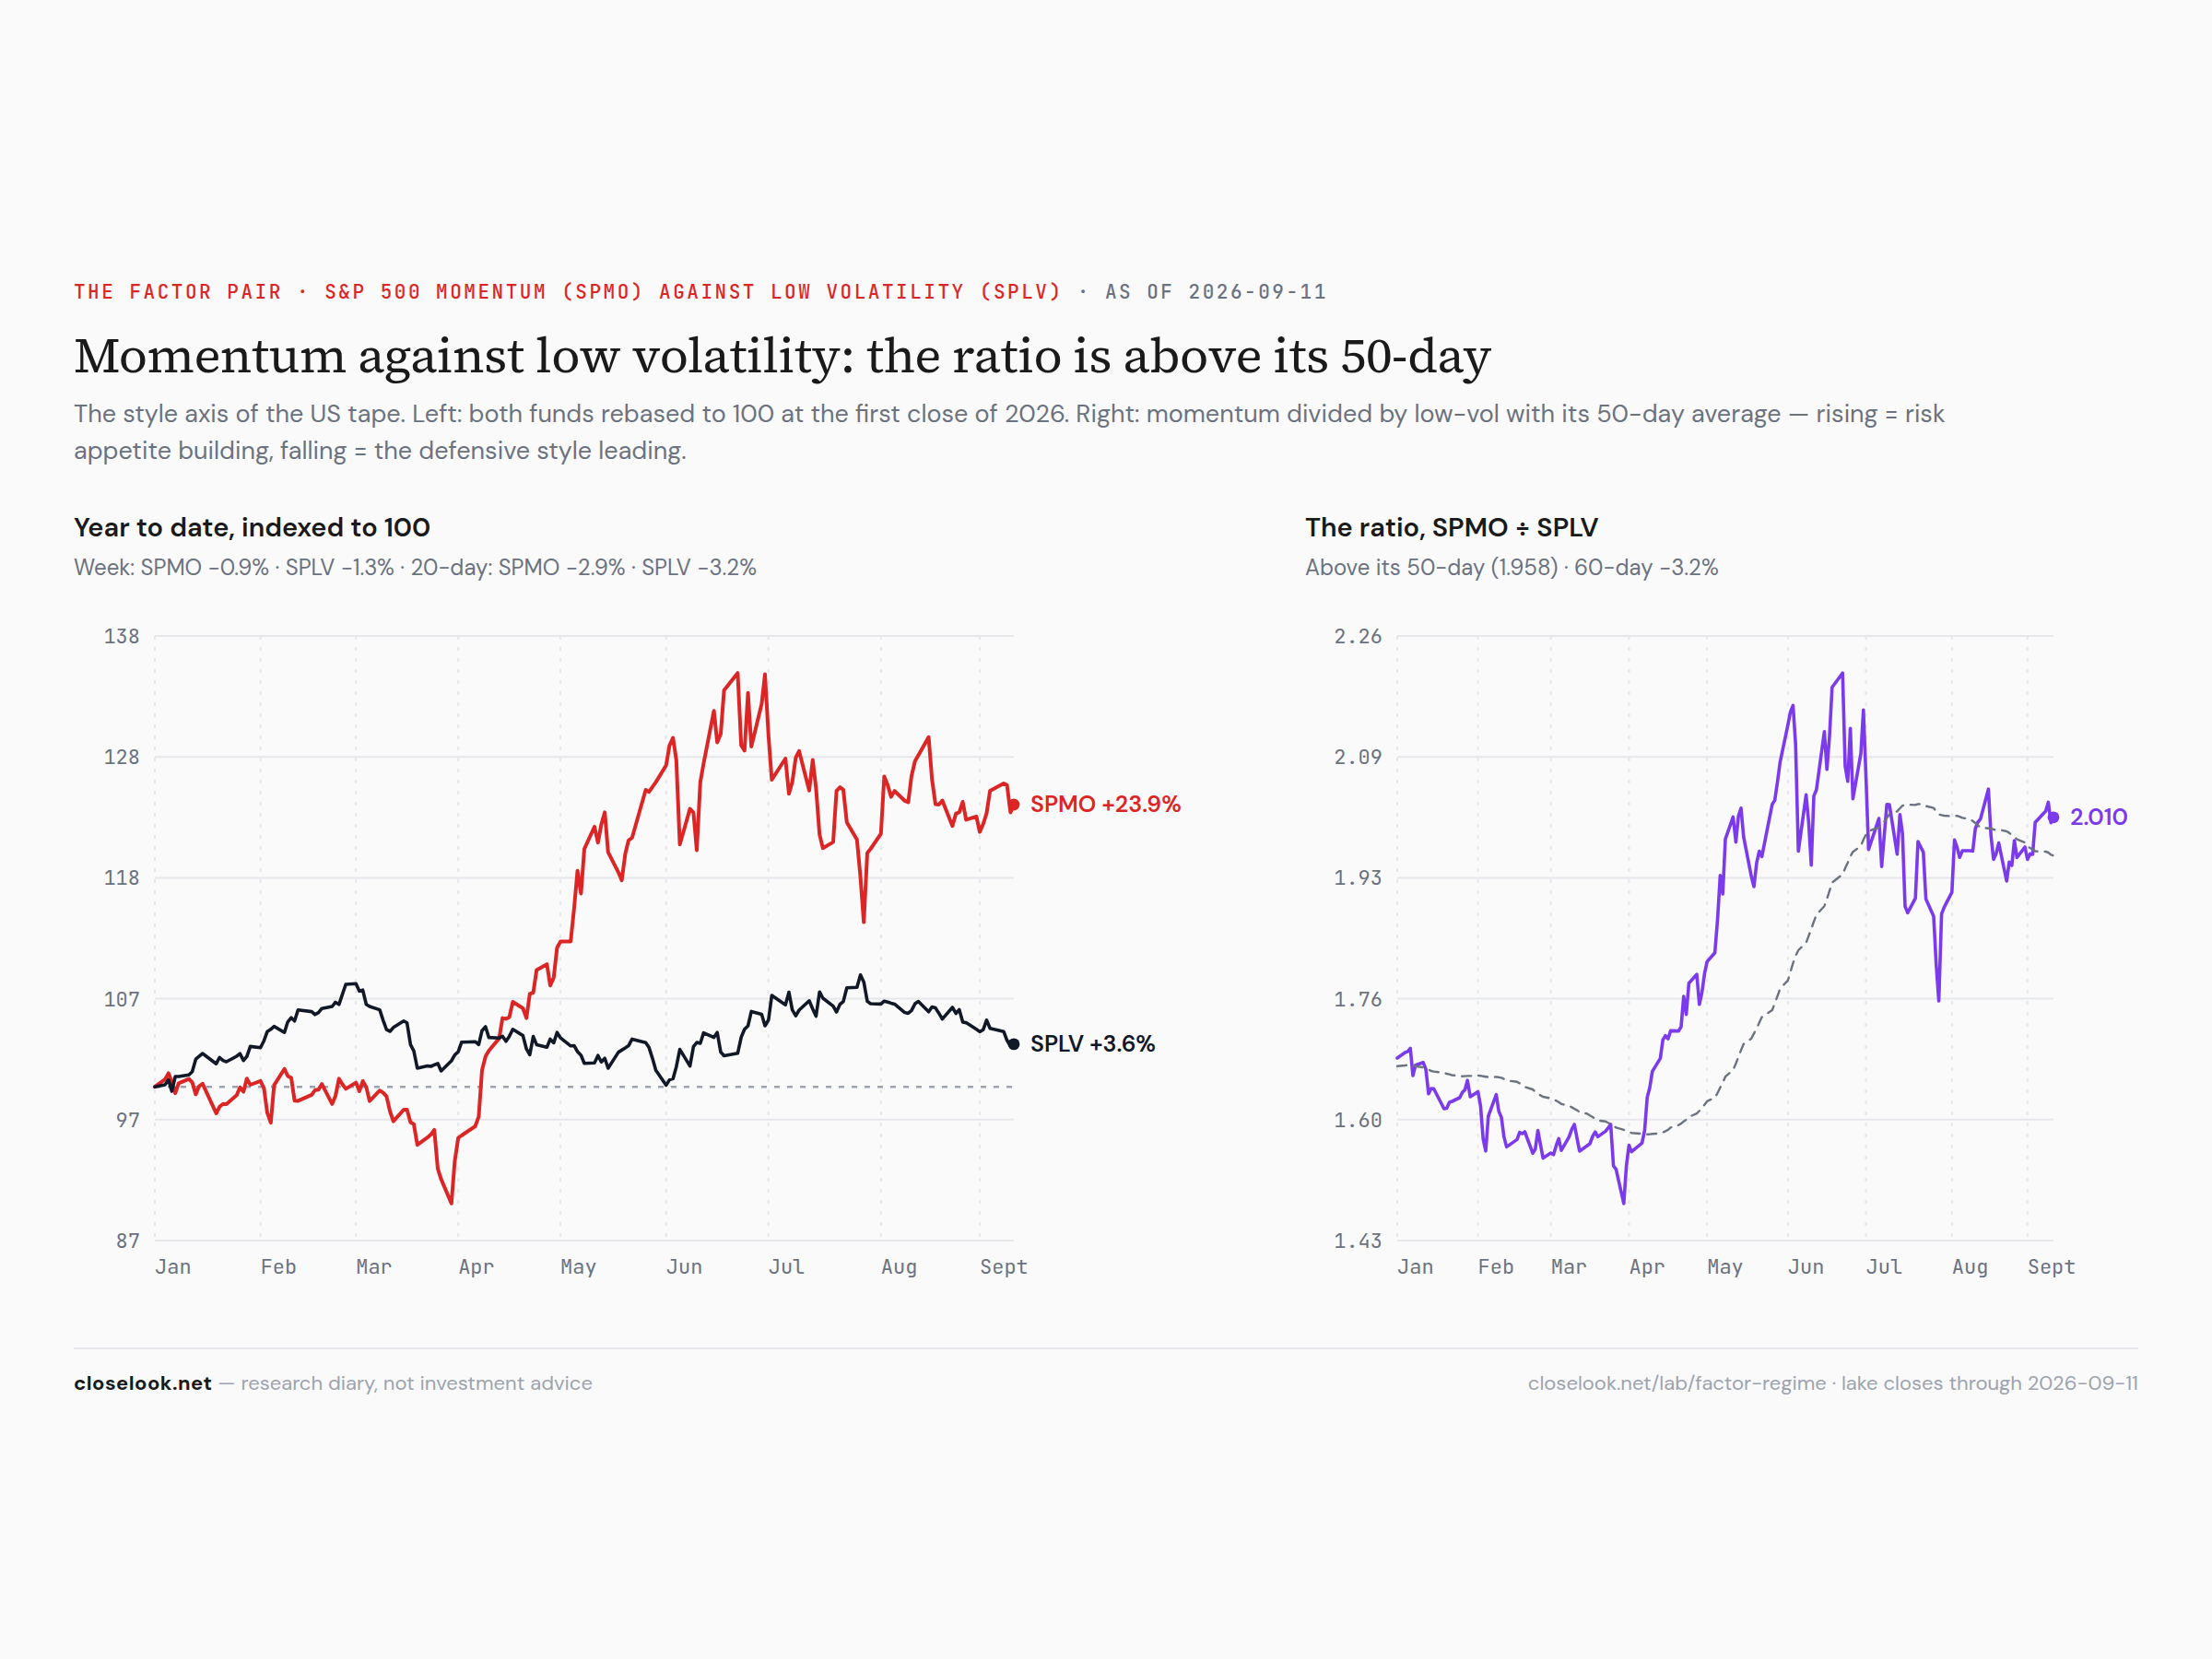
The factor view — both legs down, the label held. The factor-regime gauge kept "momentum leading, risk appetite building" — indexed 159.61 against a 50-day at 155.45, 94.4th percentile — on a week in which SPMO −0.94% and SPLV −1.27% both fell. For this cohort the read is the same as a week ago and matters more into a Fed decision: when the tape sold, it sold the defensive factor harder than the momentum factor. The money that left the software names did not go to low-volatility. It went to a test-equipment maker.
Our own board — the Rotation Ledger, on Friday's closes, and the receipts. The scanner missed its Friday-night run a third week and this desk triggered it Saturday afternoon, so the tables carry Friday's closes across 647 stocks. The shares: building flow (accelerating-up plus reversing-up) 36.5% of the universe, from 38.5%; decelerating-up 36.2%, from 34.5% — now the largest bucket outright, and still the long warning; accelerating-down 9.1%, from 8.4%; flat 18.2%. Softer at the building end, heavier at the draining end, a second week. The receipts, both ways, because that is the contract: the fastest-risers table published here last Sunday — Atlassian, freee, Appier, e.l.f., Duolingo, Elastic, Veeva, Workday, Salesforce, ServiceNow, UiPath, Snowflake — was charged again on price: Atlassian −6.27%, ServiceNow −6.18%, Workday −5.15%, Salesforce −4.44%, Elastic −9.17%, Snowflake −2.43% after its paid window, UiPath the second-worst name in the family. And the draining table — SanDisk, Kioxia, KLA, Applied Optoelectronics — was right this week: SanDisk −6.13%, Kioxia sold in Tokyo on Thursday, KLA −2.67%, and every one of them sat out Friday's chip rally. Three weeks in: one lead, one lag, and one split — right on the draining side, wrong on the building side. The instrument reads a 252-day trend of flow; the software names it says are building have now been sold for two weeks by a market pricing a hike. The letter keeps the score it earns.
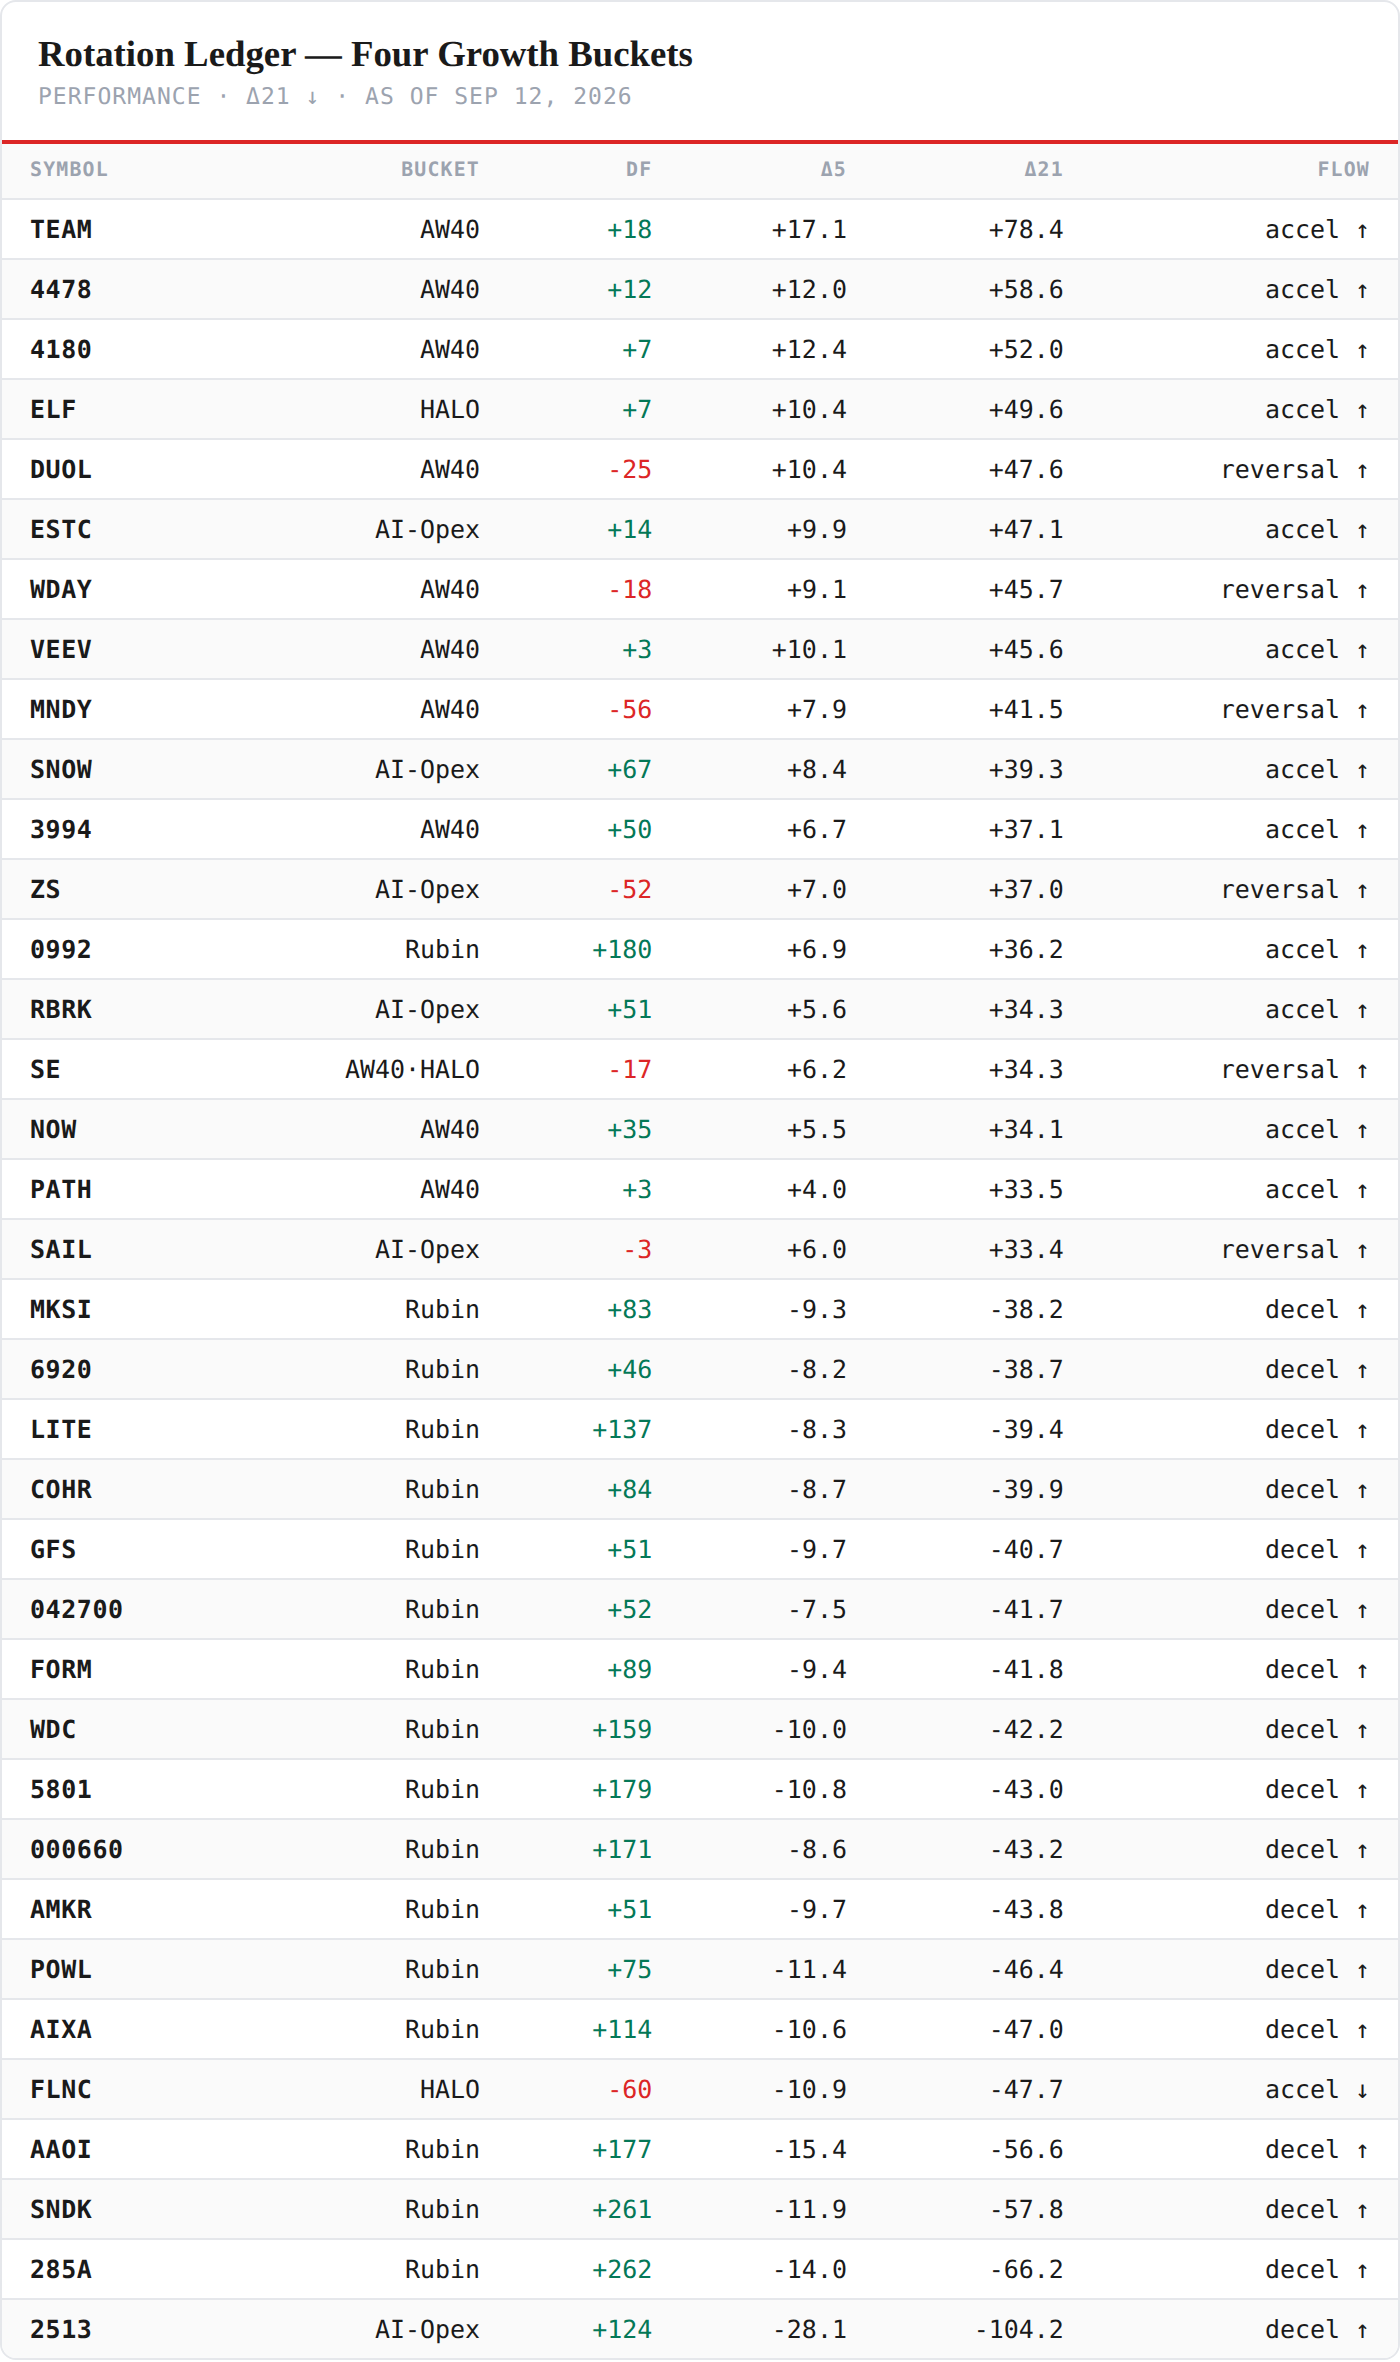
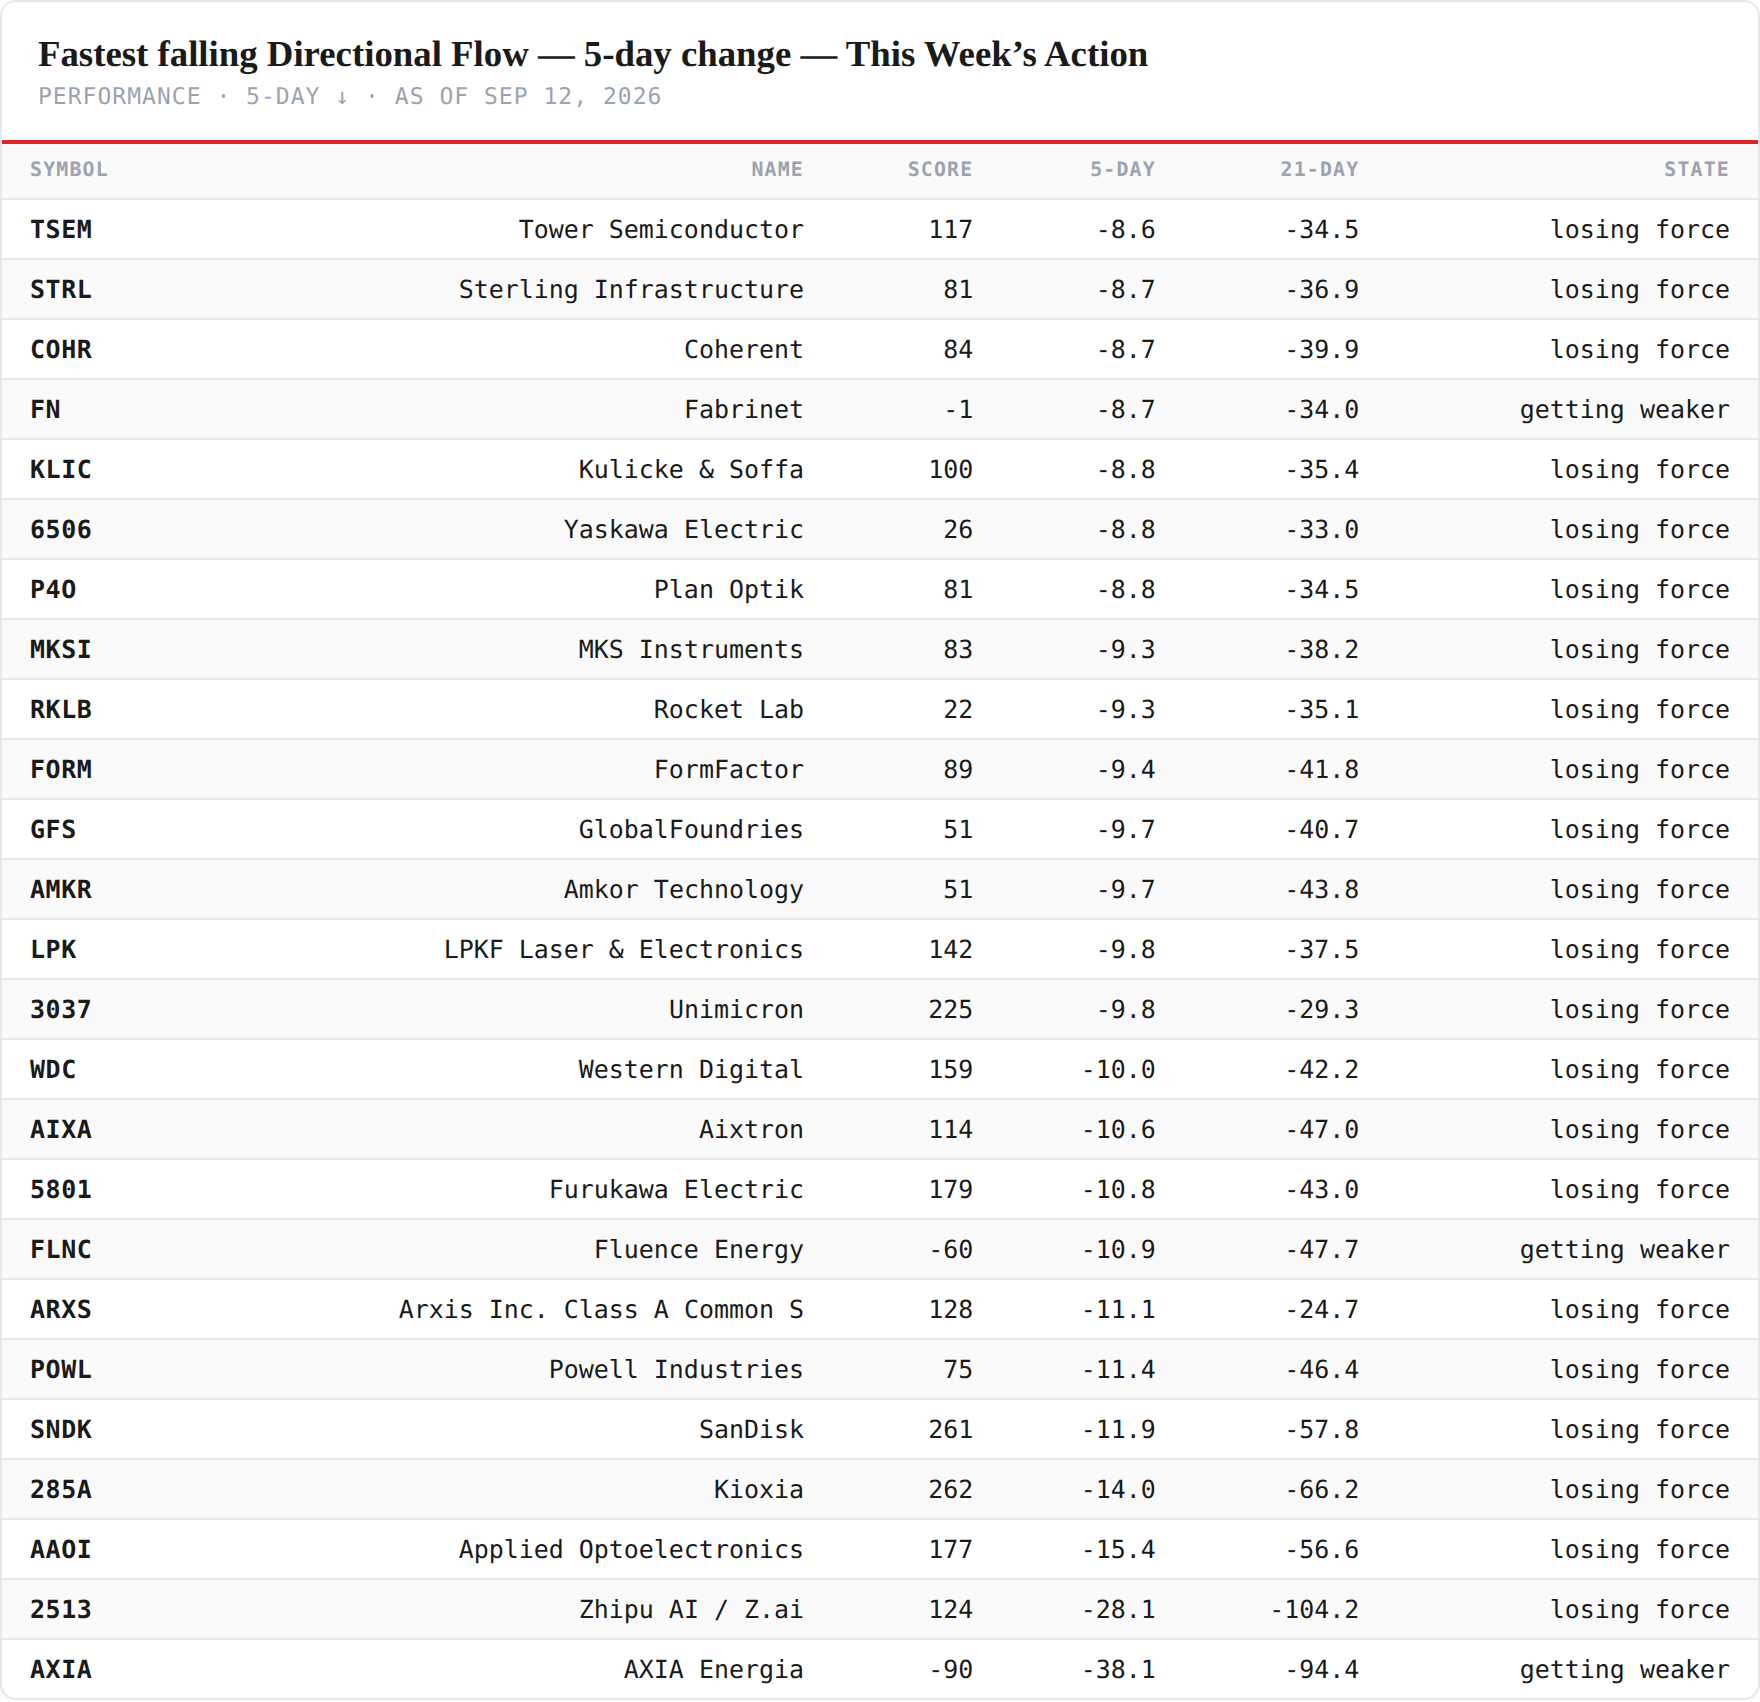
The four stock tables — this letter's own board, as of Friday 11 September.
The strongest trends, confirmed on the medium term. Dell at 211 (+16.9 on the month), Lenovo 180 (+36.2 — the fastest-building high score on the board), HPE 143 (+18.4, the week after its paid window), Nebius 135 (flat on the month), Astera Labs 129, ams-OSRAM 125, Fortinet 116, Palo Alto 112 (+21.8), Nynomic 107, Datadog 100. The confirmed board is the assemblers and the firewall pair, a third week running — and this week the assemblers were paid on price too: HPE +19.4% on the tape's week, Dell +8.2%, Lenovo the book's line in the sibling book. The exhibit of level-versus-change is unchanged and larger: Kioxia 262 and SanDisk 261 with the deepest monthly drains on the board (−66.2, −57.8), and this week the price agreed with the drain.
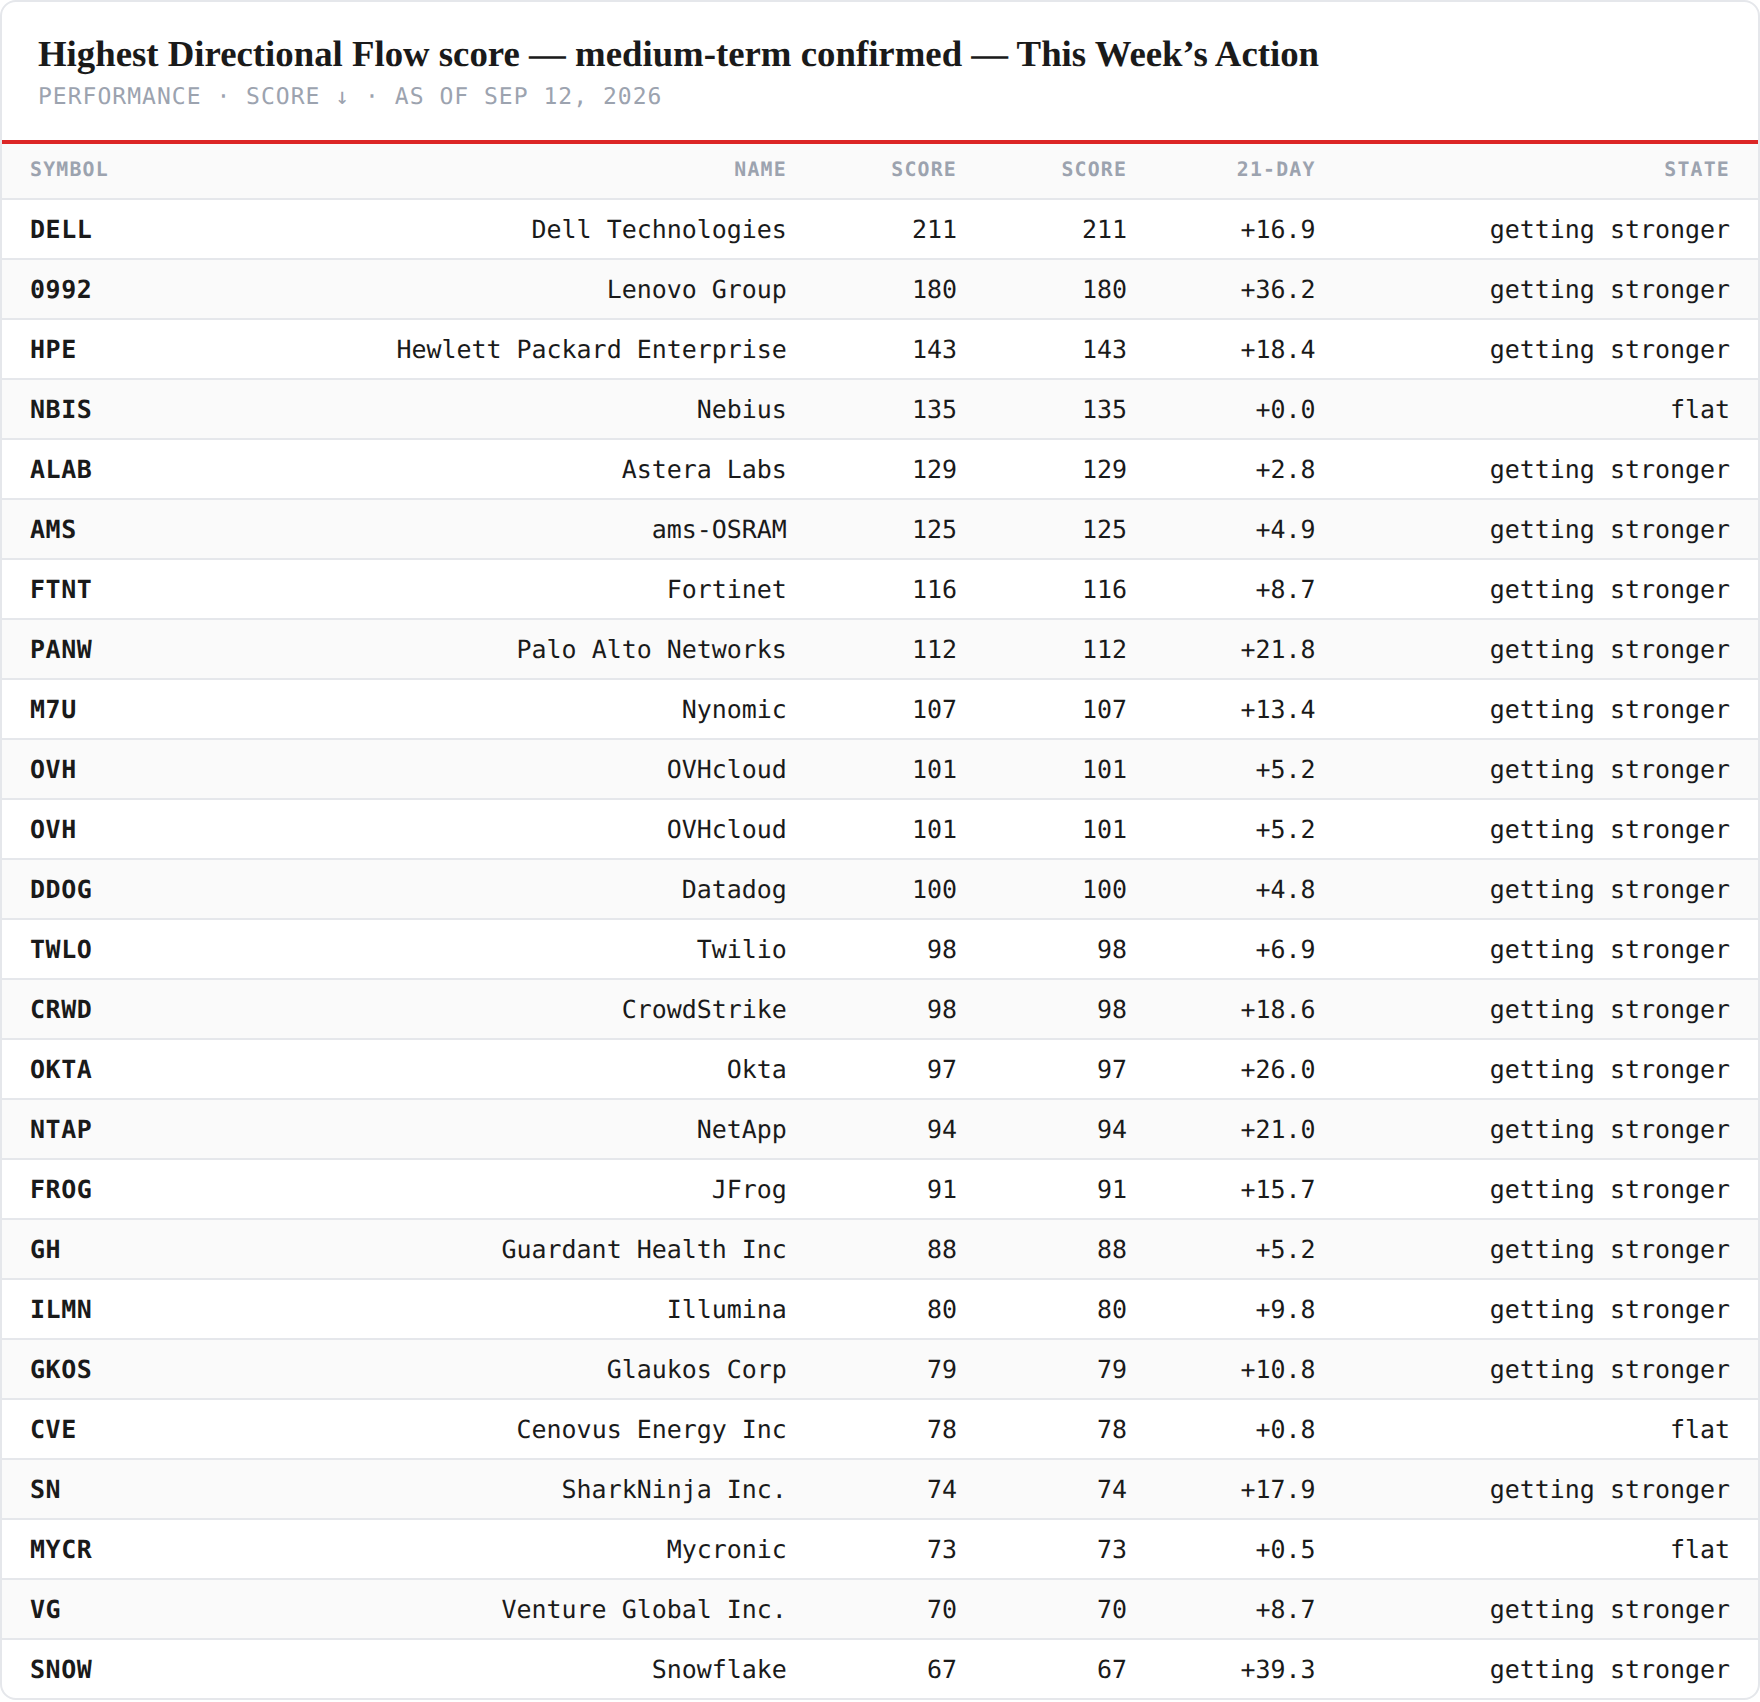
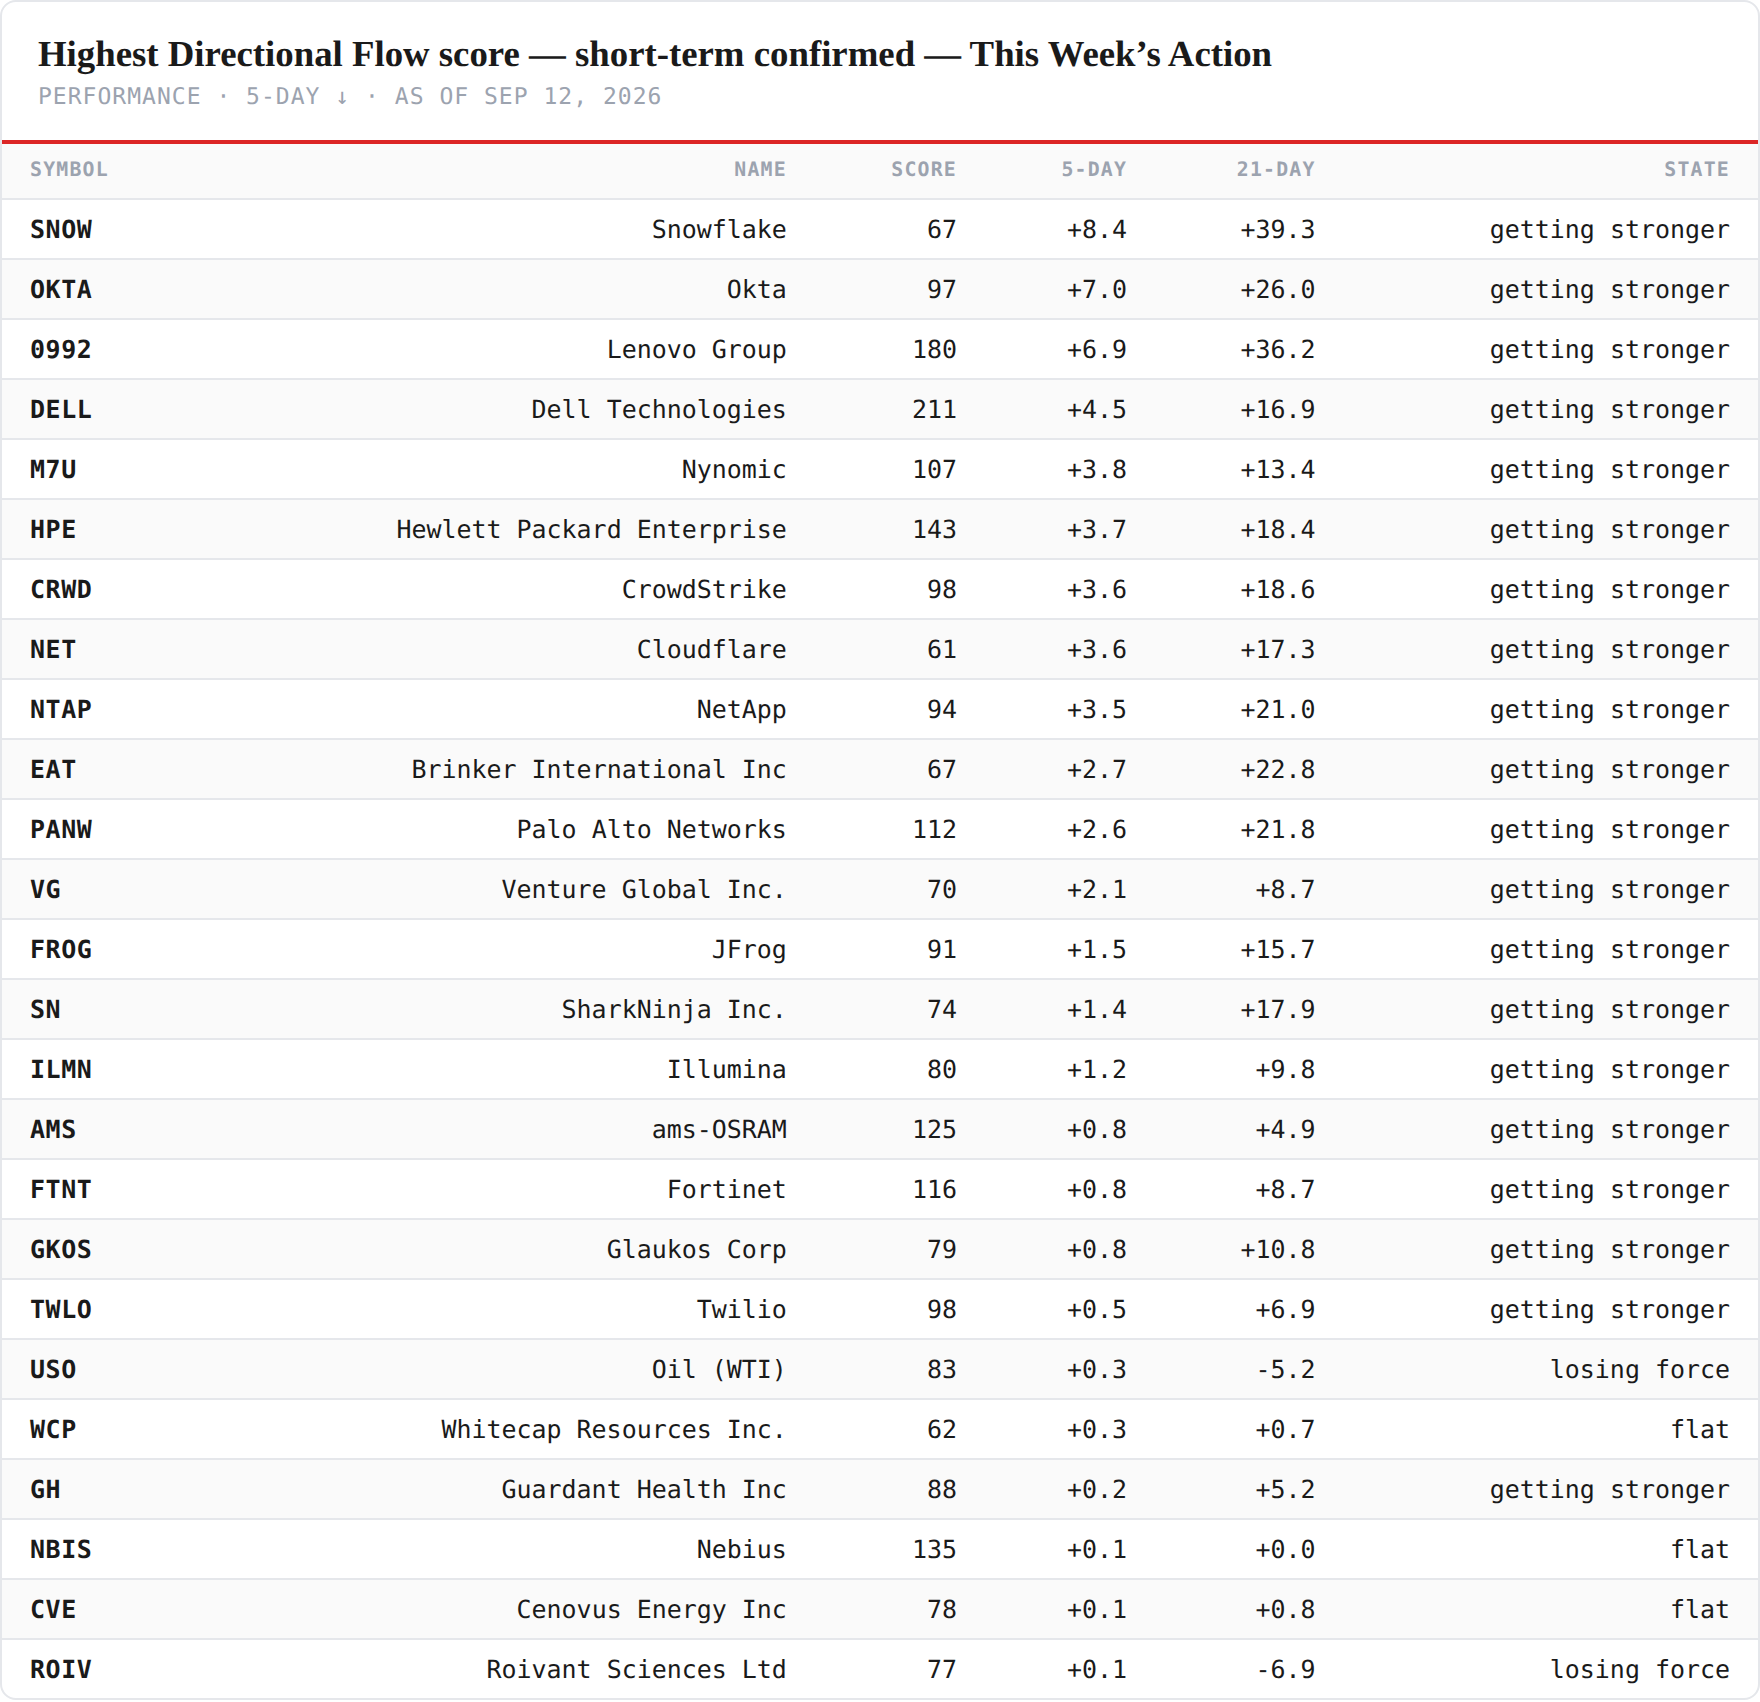
The same list, confirmed on the short term. Dell, Lenovo (+6.9 on five days), HPE, Fortinet, Palo Alto (+2.6), CrowdStrike 98 (+3.6, +18.6 on the month), Okta 97 (+7.0, +26.0), NetApp 94 (+3.5, +21.0 — the storage name the flow does confirm), Twilio 98. Still the incumbent software layer and the hardware assemblers; still no chip designer and no memory name on it. What the confirmed board does not contain is the week's best price list — Aehr, Cohu, FormFactor, Coherent — which sit on the draining side at 205, 89 and 84 with monthly changes of −14.8, −41.8 and −39.9. The test bench was paid from a drain, the same way storage was a fortnight ago.
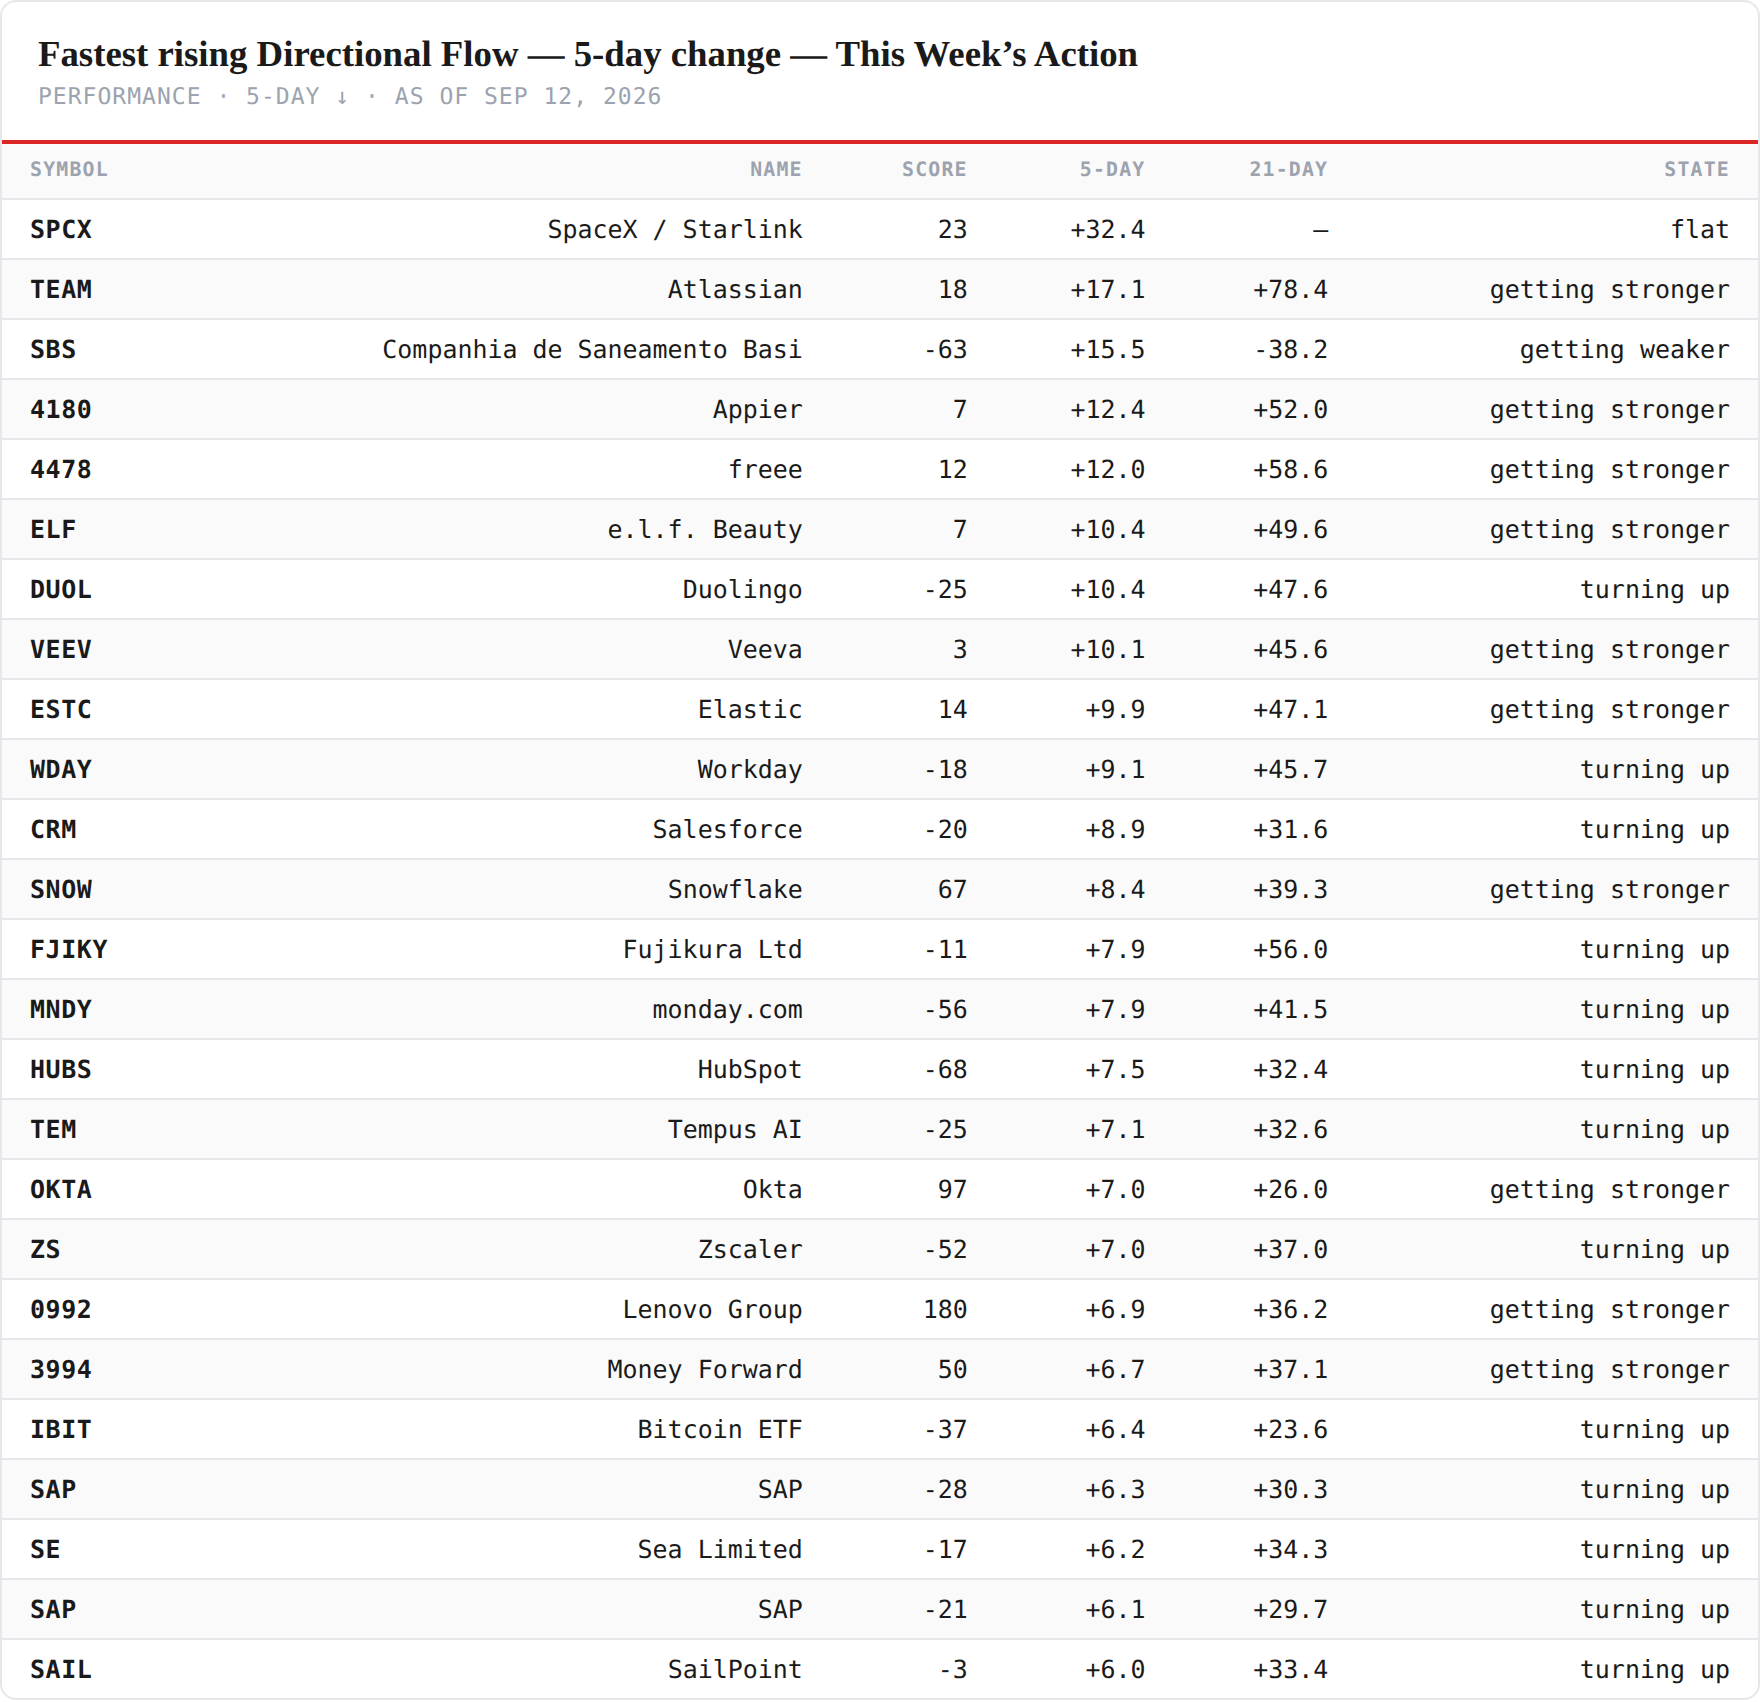
Where new leadership shows up first — the fastest risers. SpaceX +32.4 on five days from a 23 score — a listing too new for a monthly column, and the book's newest line — then Atlassian +17.1 (+78.4 on the month), Appier +12.4, freee +12.0, e.l.f. +10.4, Duolingo +10.4, Veeva +10.1, Elastic +9.9, Workday +9.1, Salesforce +8.9, Snowflake +8.4 (score 67), Fujikura +7.9. Software plus consumer, a third week, one rung further along, and one rocket company. The question this table now has to answer is not whether the flow is building — it is — but whether flow that builds for three weeks while the price is sold for two is a leading indicator or a lagging one. The next scan on the far side of the Fed will say.
And the draining side. Zhipu −28.1 on five days from a 124 score (−104.2 on the month, the deepest in the universe by a distance), Applied Optoelectronics −15.4 from 177, Kioxia −14.0 from 262, SanDisk −11.9 from 261, Powell Industries −11.4, Furukawa Electric −10.8 from 179, Aixtron −10.6, Western Digital −10.0 from 159, Unimicron −9.8 from 225, GlobalFoundries −9.7. The memory-and-optics complex, five weeks running, and this week the drain was paid in full: SanDisk the worst chip on Friday, Western Digital −4.3% on the week, the Japanese optics and materials names the worst lines in the build-out. Read against the price, the table did what it is built to do: it named the names that did not participate in the bounce.