Source page — copy text into Substack/LinkedIn, upload the visuals. noindex · not public
Closelook@Global Stock Markets · Weekly Edition
Global Markets — Taiwan and Korea Fall 11%, China and India Rise 6%, Oil Drops 12%
The week the chip corridor broke and most of the rest of the world did not follow. Taiwan's fund fell 11.7 percent and Korea's 10.4 percent, most of it in one New York session on Thursday, and Korea halted trading on Friday. India rose 6.6 percent, China's large caps 5.7 percent, Mexico 3.1 percent and Spain 2.7 percent. Oil fell 12 percent after the US and Iran signalled openness to talks, and gold rose back above its July low. The world ex-US index closed under 80 and gave up its summer-low support; the all-world index closed under its July low. The US ten-year closed a second week under 5 percent, at 4.87 percent, and France's ten-year now yields less than America's.
Closelooknet is a reader-supported publication — to receive new posts and support the work, become a free or paid subscriber.
1 · This Week's Action
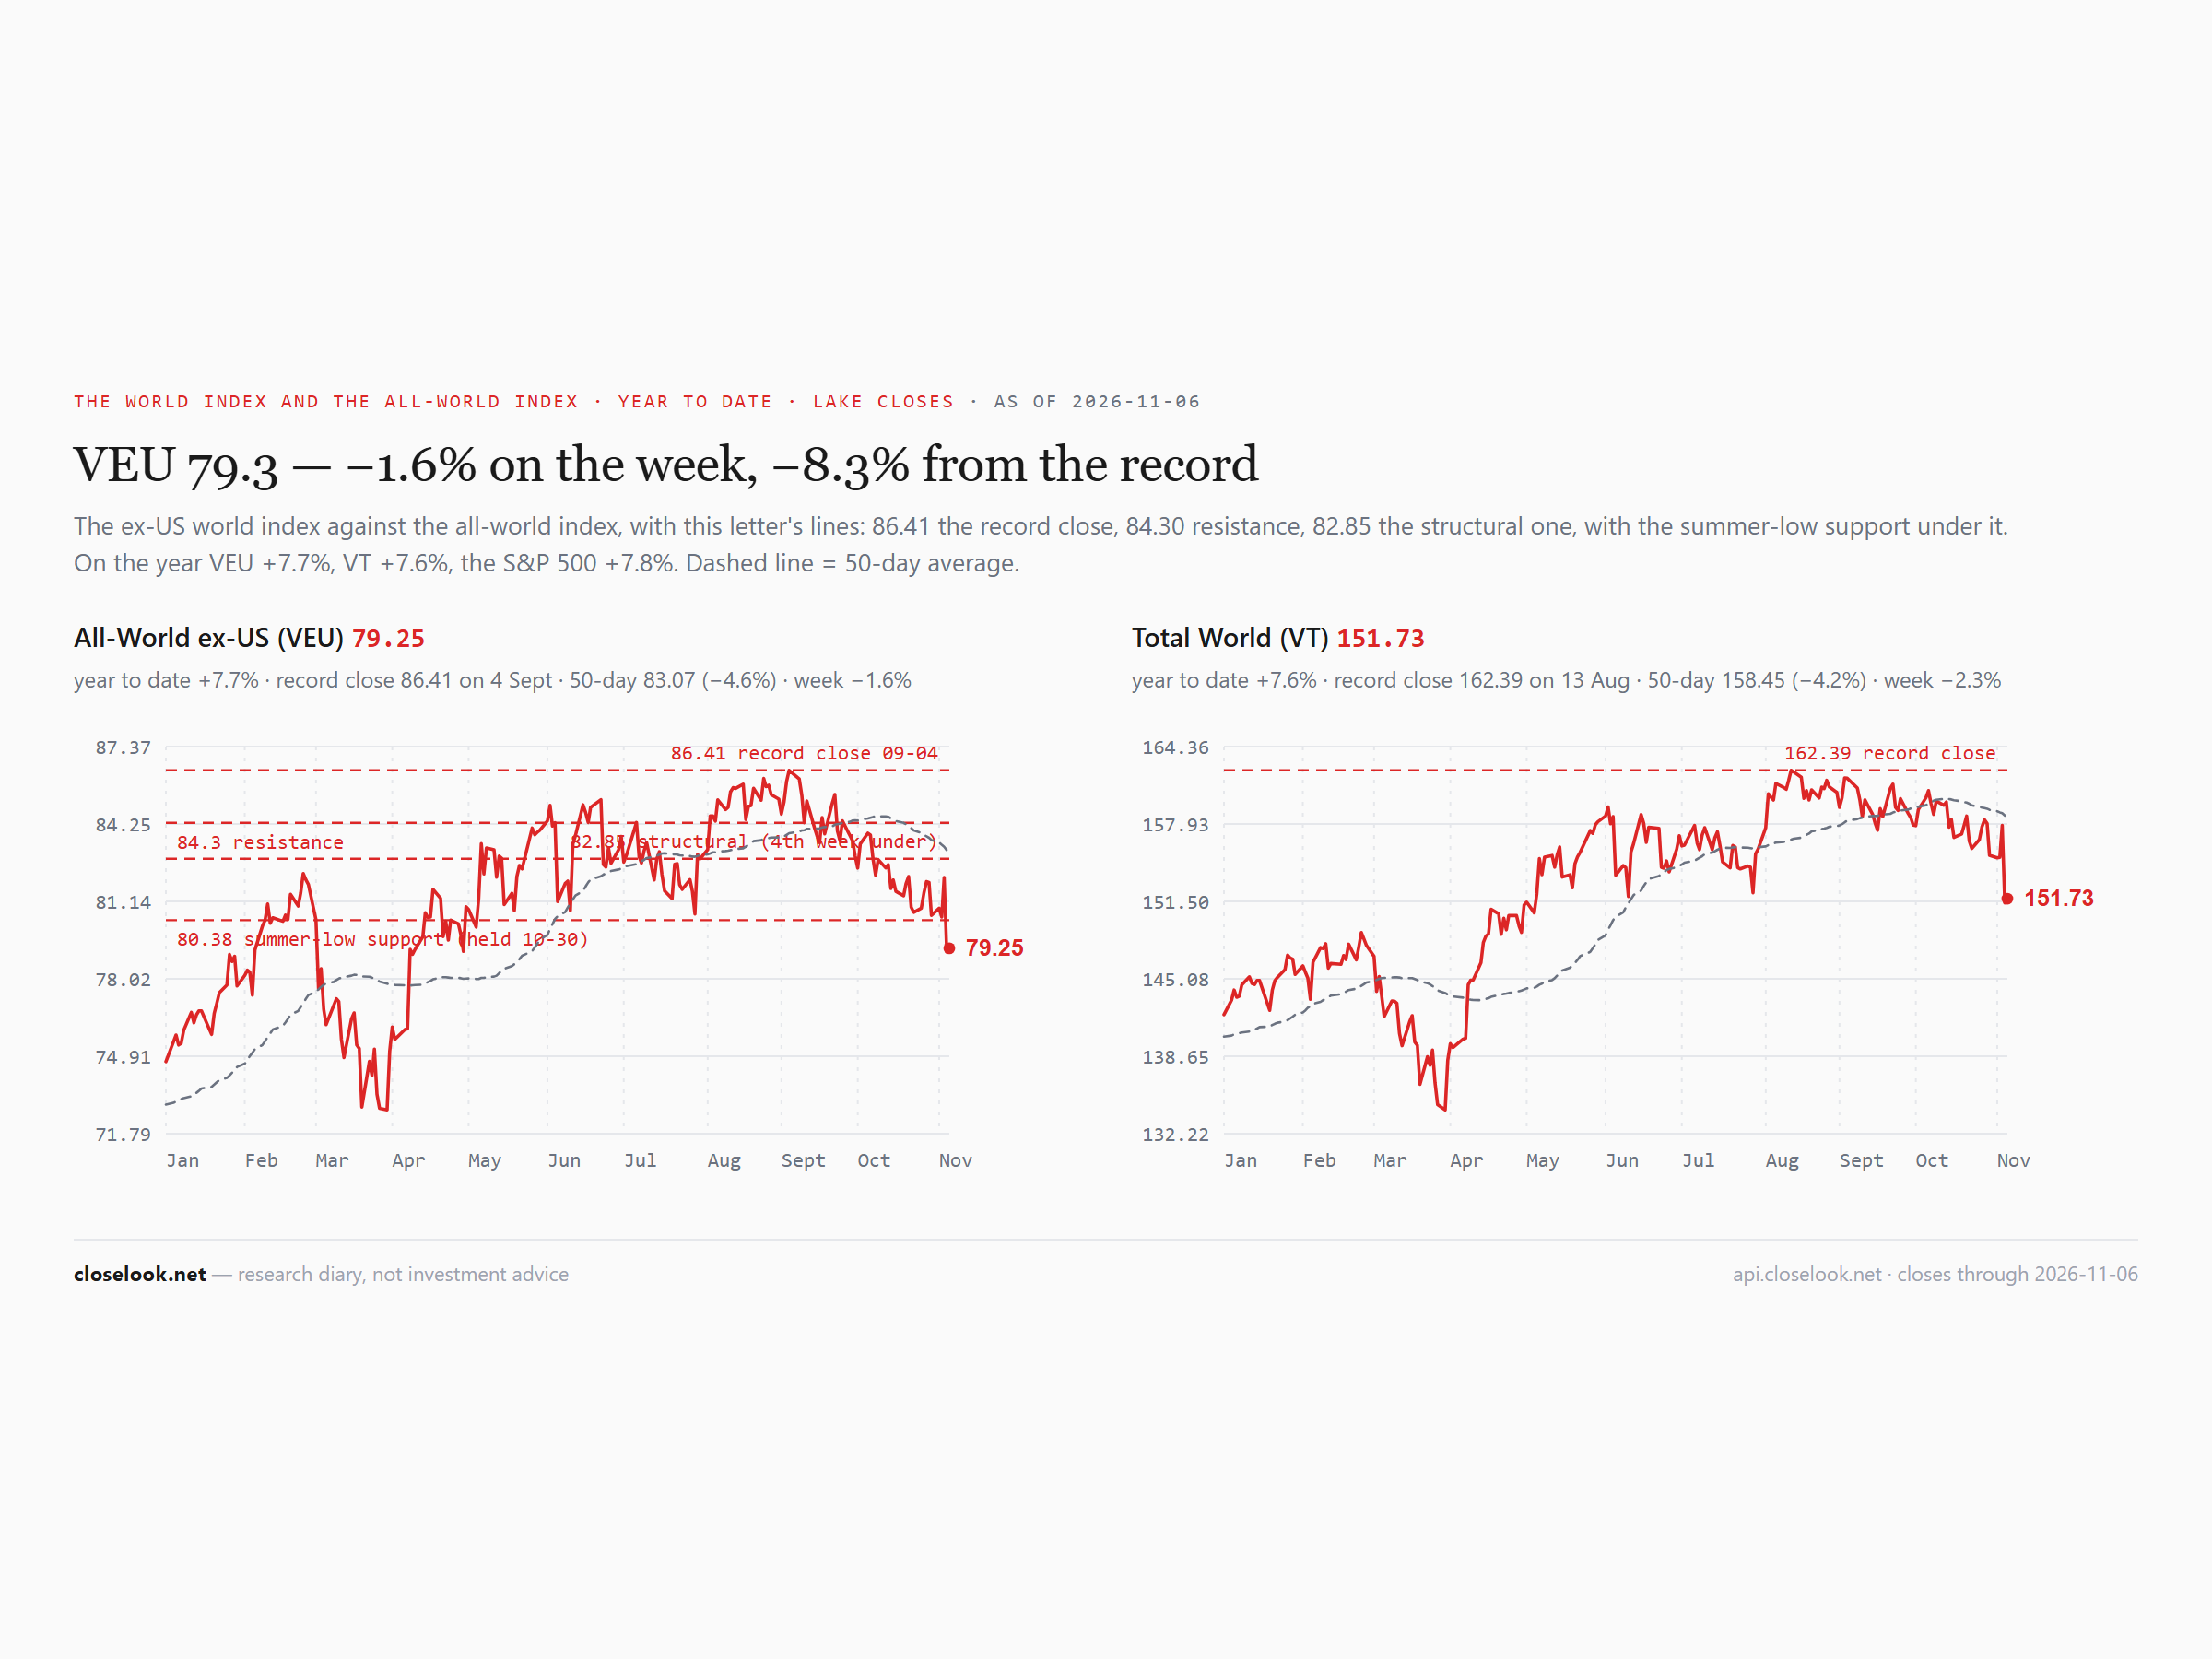
The global view. The ex-US world index closed the week at 79.25, down 1.64% — under 80, and under the summer-low support near 80.3 it had held for two weeks. The path: Monday 80.86, Tuesday 80.51, Wednesday 82.10, Thursday 79.10, Friday 79.25, with an intraday low of 78.84. The index sits 8.3% under its September 4 record of 86.41 and 8.9% above its spring low of 72.75.
The all-world index fell 2.32% to 151.73 — under its July low close of 152.22, and further under the August–October range of 156.82 to 162.39. The S&P 500 fund fell 2.70% to 735.29, 5.6% under its October 6 record; the Nasdaq 100 fund fell 4.98% to 656.10, 13.6% under its own. Wednesday was the best close of the week everywhere; Thursday took it back and more.
America's lead for the year is gone — almost to the decimal. The S&P 500 fund is +7.83% for 2026, the world ex-US +7.74%, the all-world index +7.56%. A week ago America led the world ex-US by 1.3 points; this week by a tenth of one. The house cointegration monitor still lists the VEU/SPY pair as breaking, but the spread has come back to 0.85 standard deviations below its mean, from 1.8.
The week, in one line: the chip corridor broke, and most of the world did not follow it. Taiwan and Korea lost 10 to 12 percent; India, China's large caps, Hong Kong and Mexico rose 3 to 7 percent. Oil fell 12 percent, gold rose almost 5. Twelve of the thirty-three regional funds we can price rose — two more on the board carry a vendor data error this week and are left out. The best-to-worst spread was 18.4 points, from 27.4 a week ago, and this time it was a region, not one country.
The corridor: Thursday in New York, Friday in Asia. The chip index fell from 10,269 to 9,011 on Thursday — 12.2% in one session — after a call for a pause on advanced AI, a Texas governor-elect who wants a moratorium on new data centres, and a Microsoft spending gap tied to a Texas site all landed on the companies that build AI. On Friday Korea's Kospi fell as much as 8.8% and stopped trading for 20 minutes; Japan's Nikkei closed 20.6% under its high, a bear market by the usual definition; Taiwan fell as much as 9%. Back in New York the chip index rose 4.2% on Friday to 9,390, after a jobs report showing 165,000 new payrolls against about 60,000 expected. The week: −12.2% for the chip index, −11.2% for the chip majors fund SMH to 463.96, 30.6% under its June record.
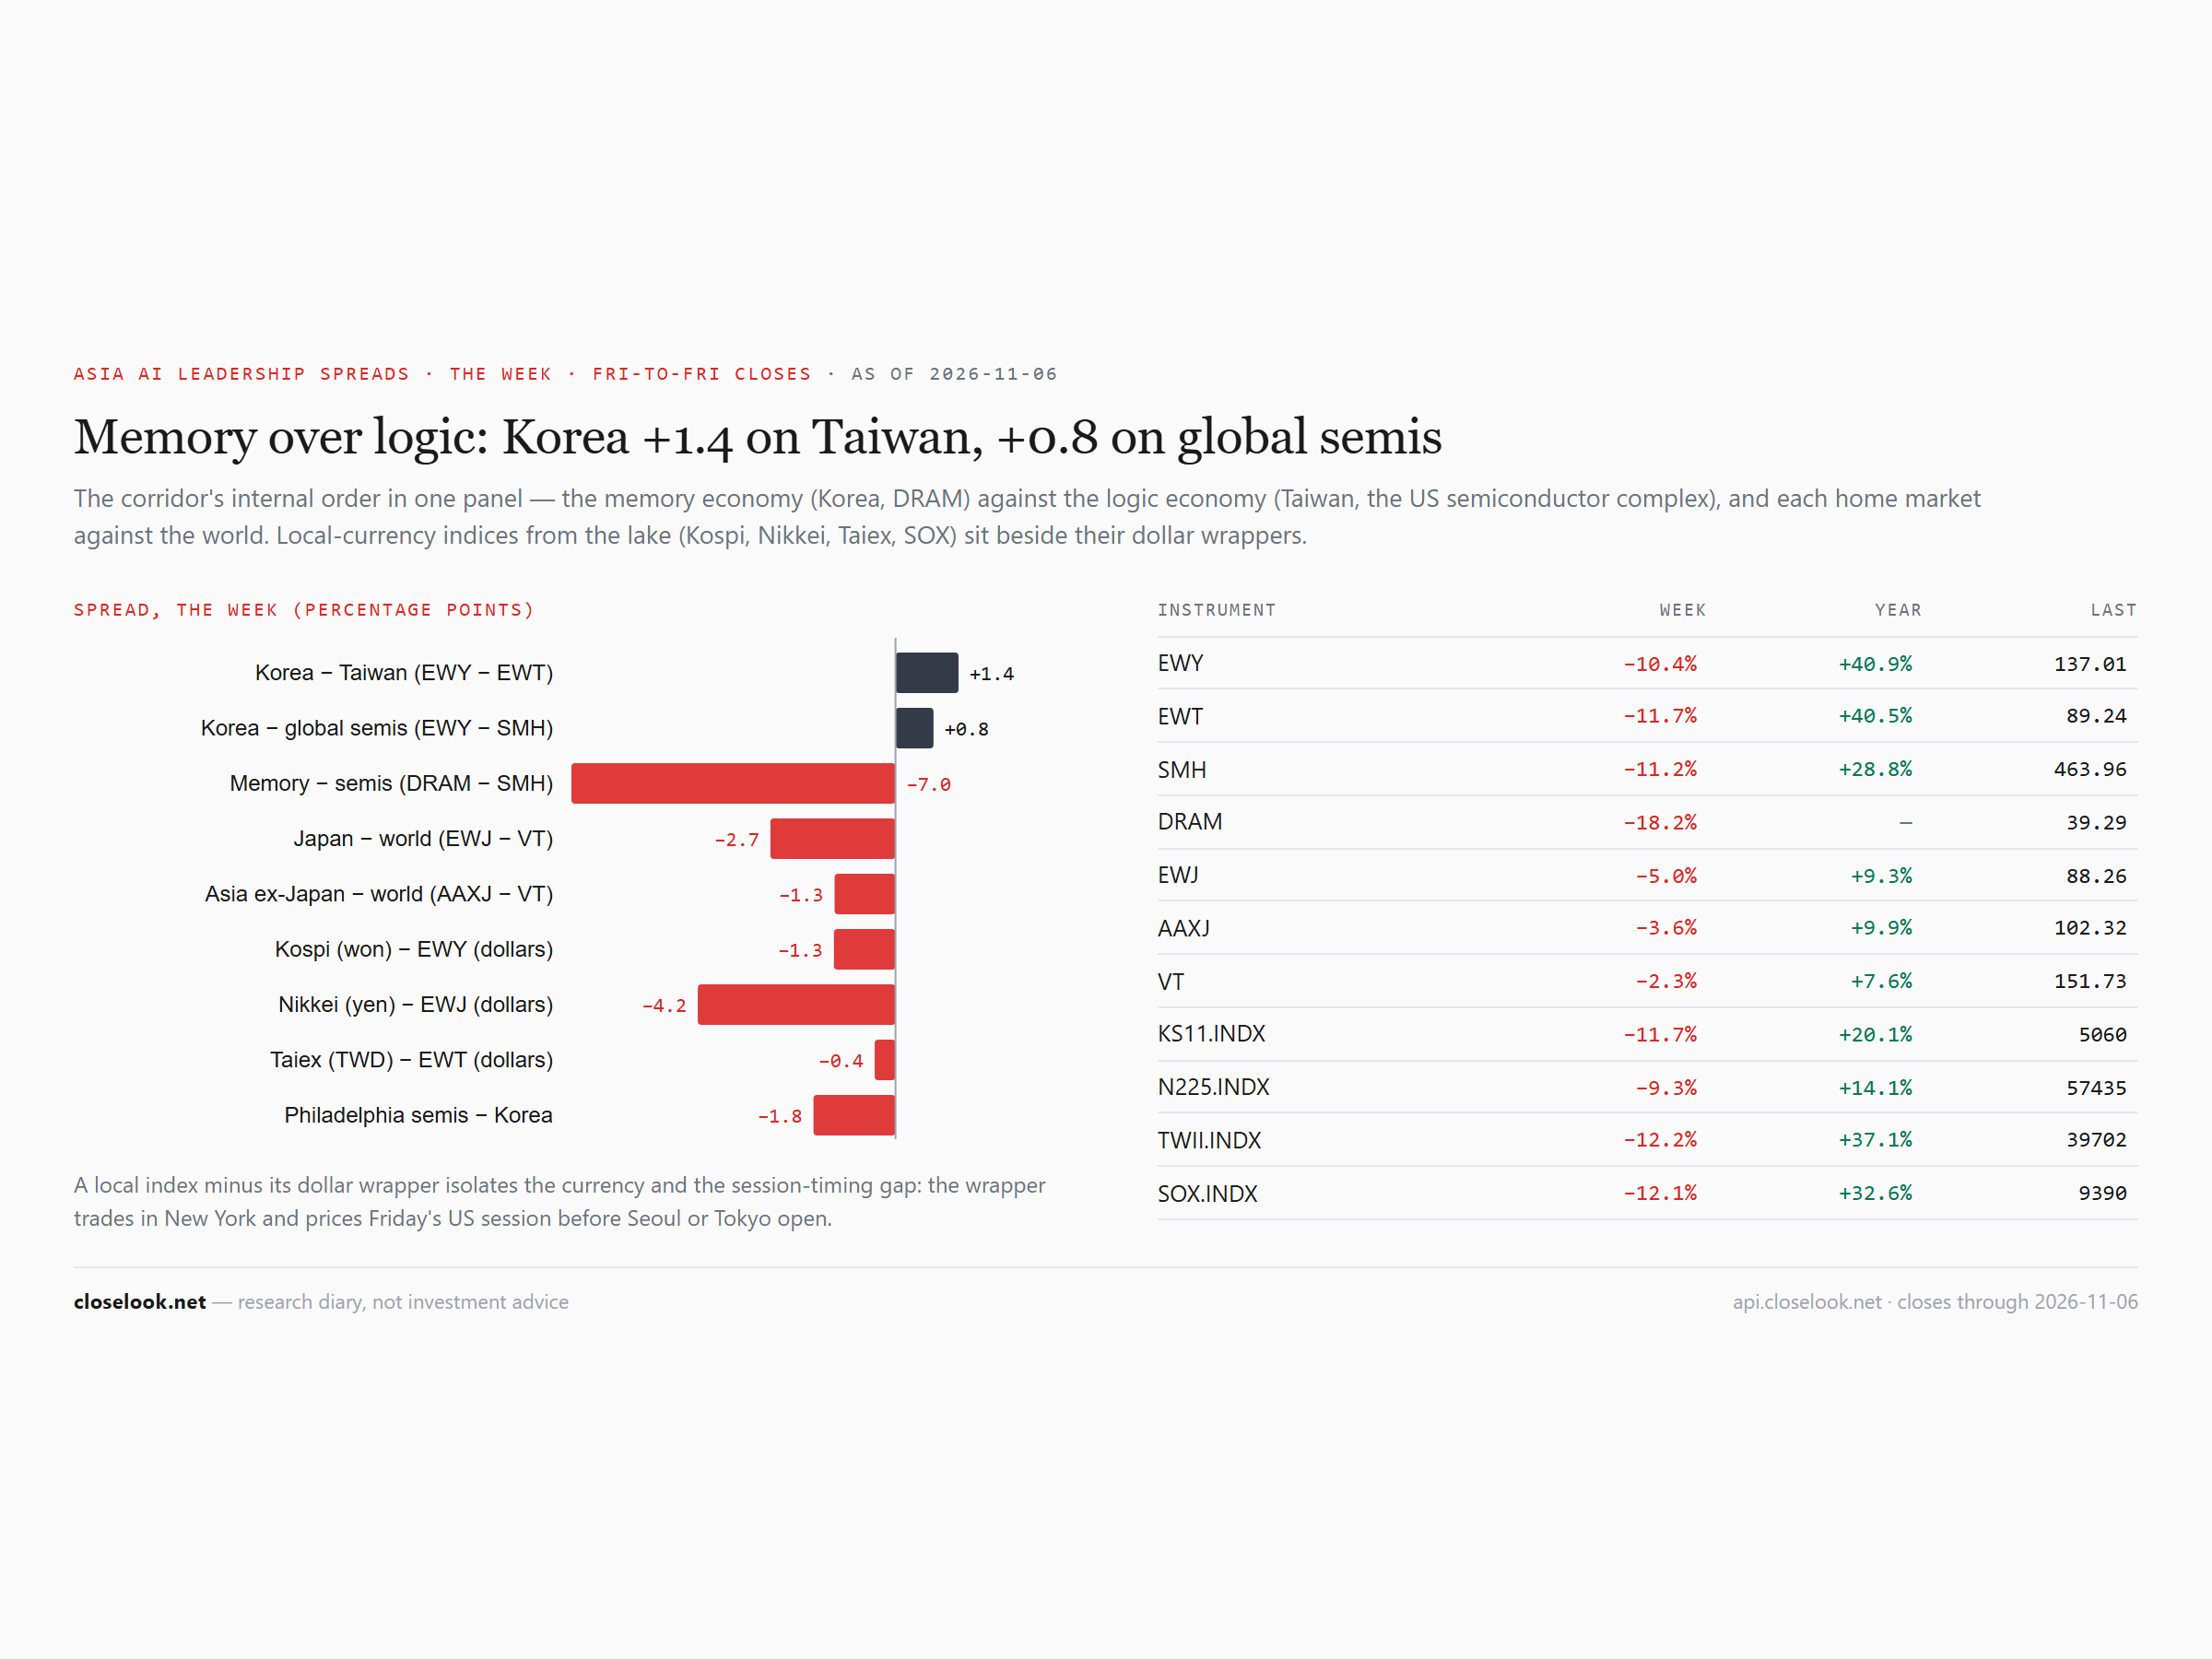
Asia's chip markets, in their own currencies. Korea: the Kospi −11.7% to 5,060, the Kosdaq −11.1% to 644, its lowest close of the past year; the dollar fund EWY −10.4%. Taiwan: the Taiex −12.2% to 39,702; the fund EWT −11.7% to 89.24. Japan: the Nikkei −9.3% to 57,435, the TOPIX −6.5%, the dollar fund −5.0% — the yen weakened from 157.55 to 158.43 per dollar. Hong Kong's Hang Seng +5.1% to 24,482, China's large caps +5.7%, the A-shares +1.5%. India: the Nifty +8.6% to 25,030, the Sensex +8.8%, the dollar fund +6.6%. Australia's ASX 200 rose 1.3%.
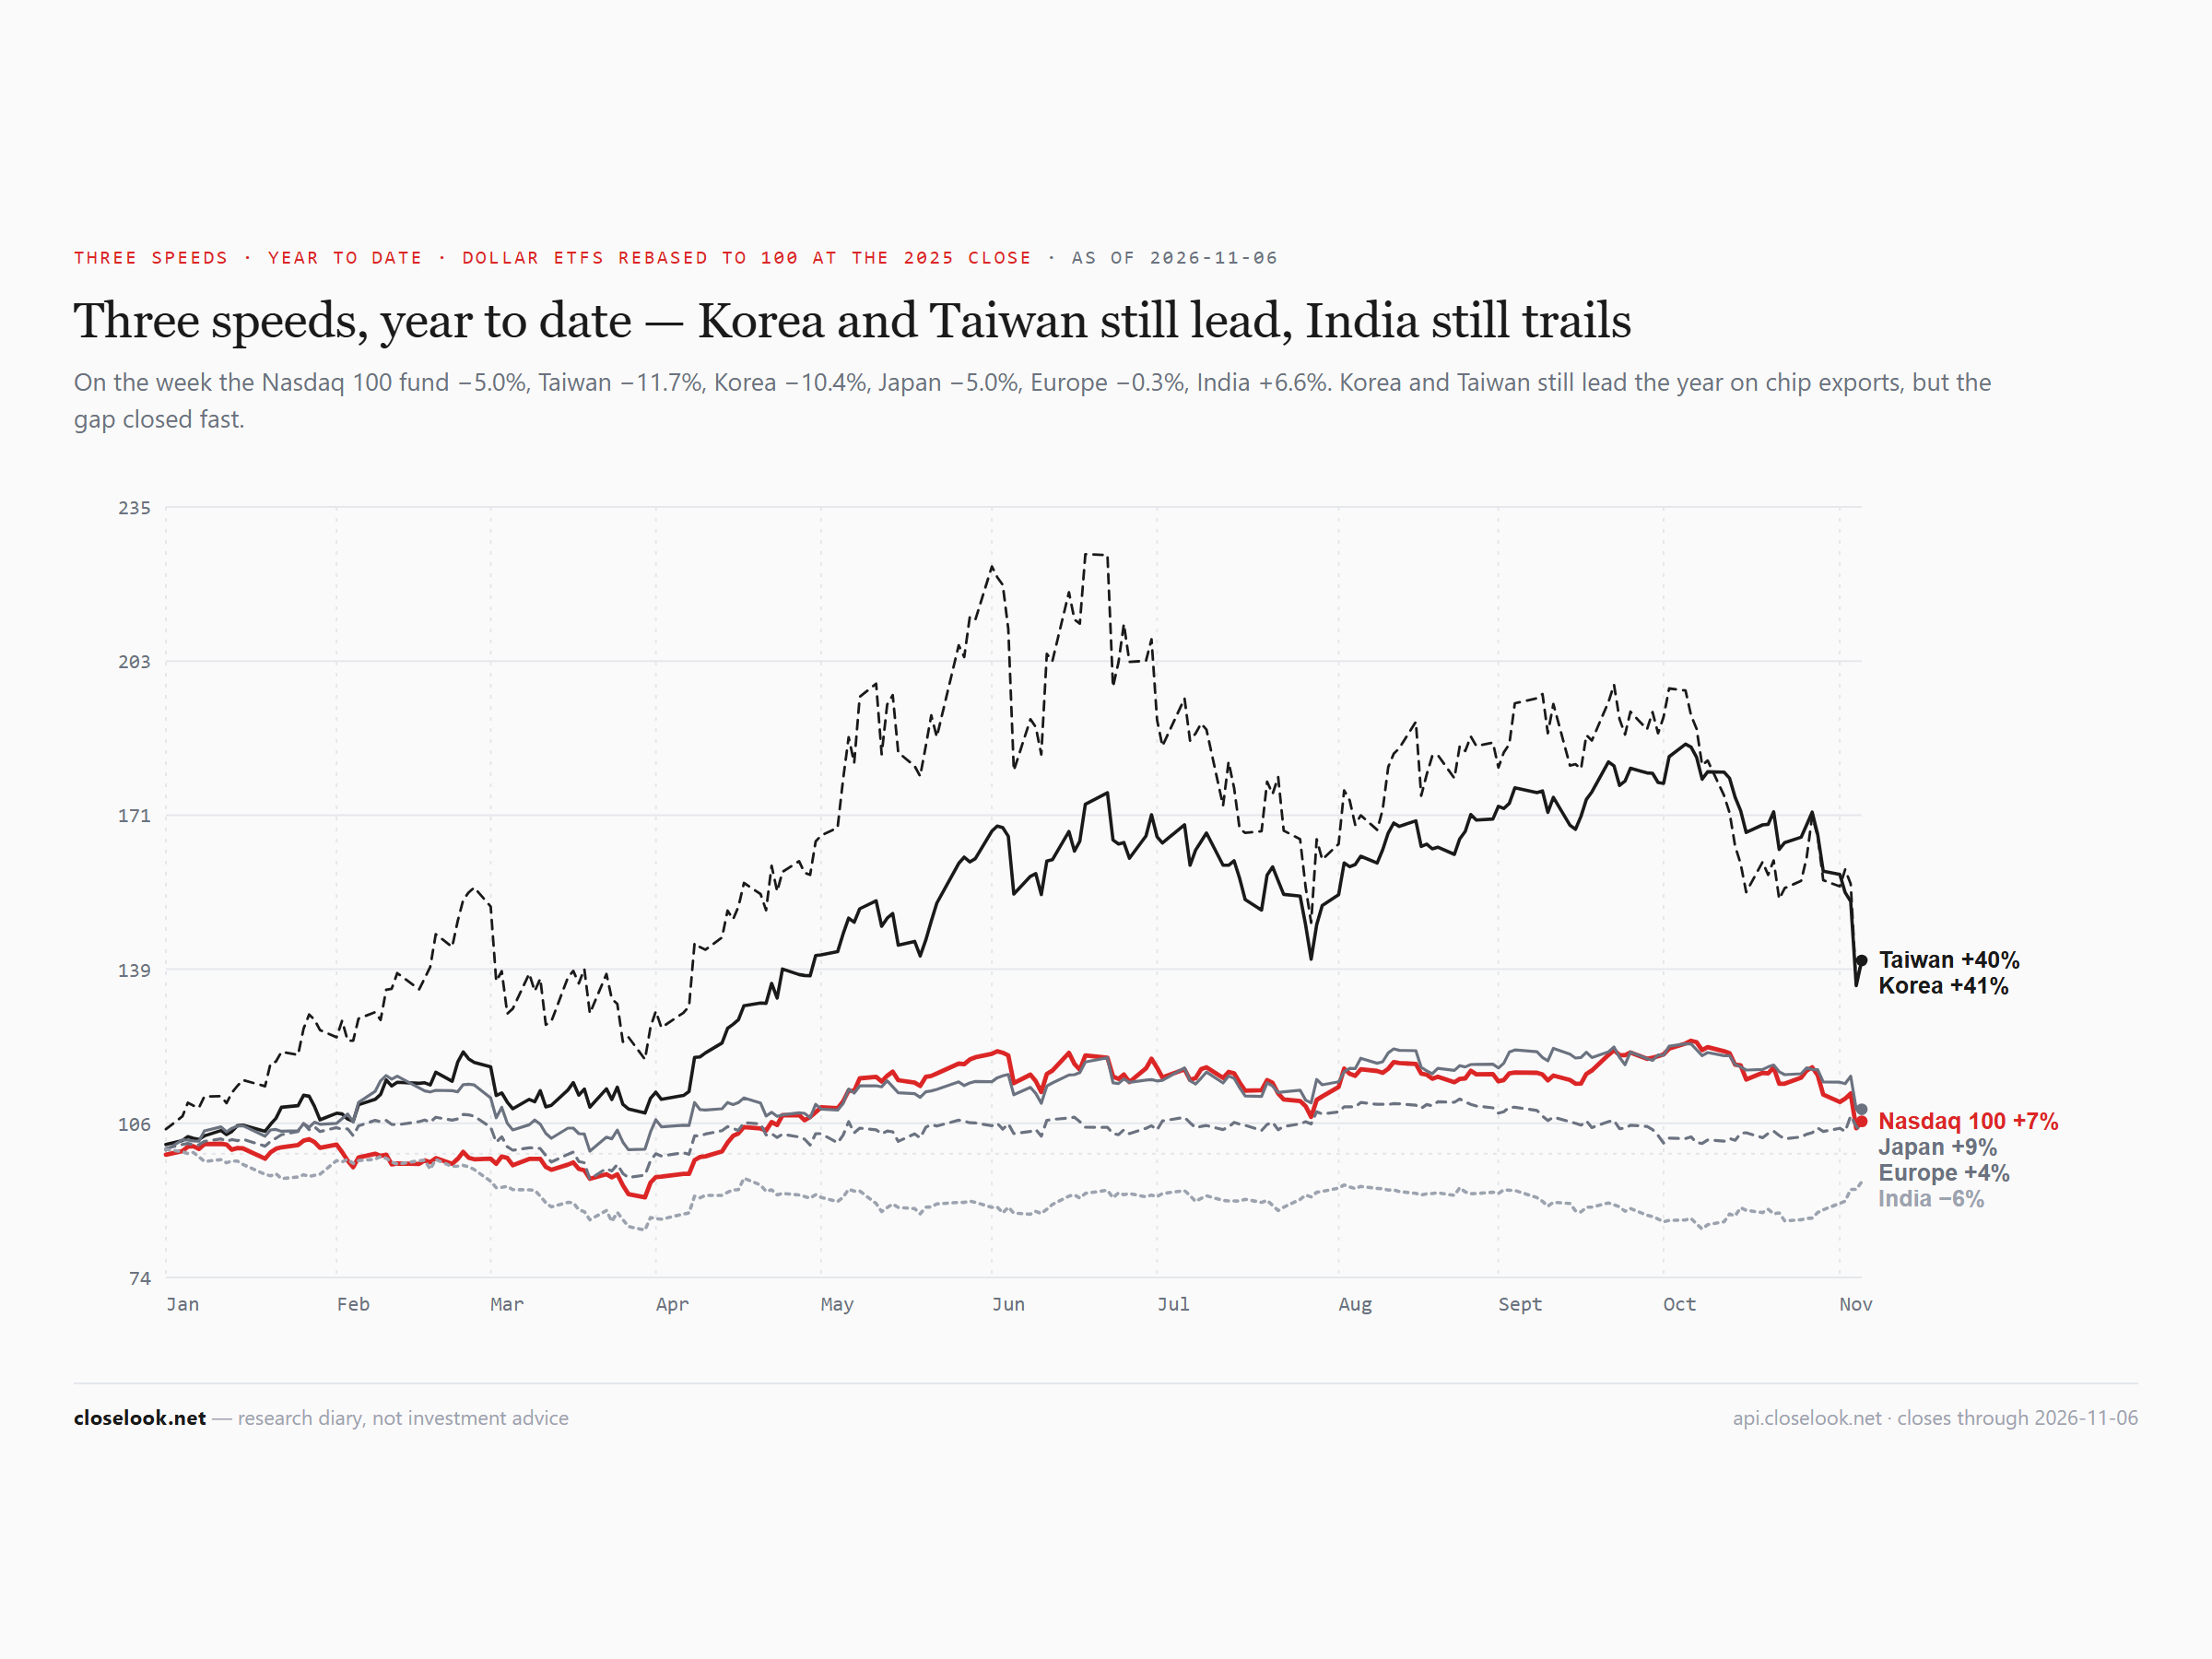
The regional board — twelve green of thirty-three. The top: India +6.64%, China large caps +5.65%, Hong Kong +3.55%, Mexico +3.05%, Spain +2.72%, France +1.54%, the A-shares +1.53%, Indonesia +1.10%. The bottom: Taiwan −11.74%, Korea −10.39%, Argentina −6.96%, Norway −6.36%, Japan −5.00%, international momentum −4.42%, Thailand −3.16%, Southeast Asia −3.02%. Brazil, last week's 24% loser, fell another 1.48% to 31.98; the Latin America fund ended flat.
| Symbol | Name | Last | 5D | 1M | 3M | 6M | YTD |
|---|---|---|---|---|---|---|---|
| INDA | iShares MSCI India | 50.89 | +6.64% | +8.90% | +1.54% | +1.72% | -5.85% |
| FXI | iShares China Large-Cap | 34.95 | +5.65% | +3.49% | -2.78% | -6.78% | -8.72% |
| EWH | iShares MSCI Hong Kong | 23.32 | +3.55% | +7.86% | +3.69% | -4.39% | +9.74% |
| EWW | iShares MSCI Mexico | 76.74 | +3.05% | +5.57% | +0.14% | -3.50% | +10.69% |
| EWP | iShares MSCI Spain | 57.86 | +2.72% | -1.67% | -7.13% | +0.35% | +7.33% |
| EWQ | iShares MSCI France | 42.89 | +1.54% | +2.58% | -9.89% | -8.20% | -4.67% |
| ASHR | Xtrackers Harvest CSI 300 Chin | 30.5 | +1.53% | -6.58% | -12.13% | -15.28% | -7.15% |
| EIDO | iShares MSCI Indonesia | 10.07 | +1.10% | -15.59% | -20.14% | -33.40% | -46.15% |
| ENZL | iShares MSCI New Zealand | 45.15 | +0.77% | +0.79% | -5.34% | -1.82% | -0.26% |
| EWM | iShares MSCI Malaysia | 26.99 | +0.45% | -0.48% | -3.95% | -11.19% | -1.35% |
| EWL | iShares MSCI Switzerland | 64.62 | +0.39% | +8.99% | +1.41% | +3.39% | +7.77% |
| EWO | iShares MSCI Austria | 39.59 | +0.13% | -5.49% | -10.55% | -1.62% | +11.62% |
| FEZ | EURO STOXX 50 | 65.03 | +0.00% | -2.64% | -8.69% | -4.33% | +0.99% |
| VWO | Vanguard FTSE Emerging Markets | 55.29 | -0.40% | -8.79% | -7.79% | -8.99% | +2.85% |
| EWG | iShares MSCI Germany | 41.58 | -0.72% | +0.22% | -4.46% | -4.35% | -2.16% |
| EFAV | iShares MSCI EAFE Min Vol Fact | 95.13 | -1.16% | +4.50% | +2.02% | +3.17% | +10.30% |
| EWA | iShares MSCI Australia | 29.17 | -1.25% | +2.17% | -3.28% | -3.15% | +11.38% |
| EWU | iShares MSCI United Kingdom | 47.22 | -1.28% | +1.83% | -2.24% | -0.46% | +7.37% |
| EPOL | iShares MSCI Poland | 42.79 | -1.41% | -3.84% | -2.88% | +6.50% | +21.60% |
| EWN | iShares MSCI Netherlands | 63.38 | -1.48% | -6.96% | -7.51% | -3.77% | +11.13% |
| EWZ | iShares MSCI Brazil | 31.98 | -1.48% | -25.63% | -10.70% | -19.85% | +0.66% |
| VEU | Vanguard FTSE All-World ex-US | 79.25 | -1.64% | -5.44% | -6.07% | -5.04% | +7.74% |
| VSS | Vanguard FTSE All-World ex-US | 145.15 | -1.96% | -7.15% | -7.64% | -10.35% | +1.27% |
| VEA | Vanguard FTSE Developed Market | 67.9 | -2.22% | -4.51% | -5.85% | -4.19% | +8.69% |
| VT | Vanguard Total World Stock | 151.73 | -2.32% | -5.58% | -5.12% | -2.15% | +7.56% |
| ASEA | Global X - FTSE Southeast Asia | 19.24 | -3.02% | -8.82% | -9.37% | -3.12% | +4.97% |
| THD | iShares MSCI Thailand | 66.3 | -3.16% | -7.80% | -9.03% | -8.34% | +11.11% |
| IMTM | iShares MSCI Intl Momentum Fac | 48.71 | -4.42% | -8.73% | -8.22% | -8.02% | +1.54% |
| EWJ | iShares MSCI Japan | 88.26 | -5.00% | -11.14% | -7.24% | -3.73% | +9.31% |
| ENOR | iShares MSCI Norway | 35.24 | -6.36% | +0.21% | +2.25% | -5.48% | +22.46% |
| ARGT | Global X - MSCI Argentina | 73.67 | -6.96% | -17.86% | -20.41% | -21.60% | -19.41% |
| EWY | iShares MSCI South Korea | 137.01 | -10.39% | -26.50% | -16.52% | -24.71% | +40.93% |
| EWT | iShares MSCI Taiwan | 89.24 | -11.74% | -24.12% | -12.49% | -5.91% | +40.47% |
Sorted by Weighted Alpha (leaders → laggards) · Barchart, close of week.
The cross-asset backdrop — the metals rose, oil fell, the dollar held its high. Five green of twelve: silver +5.09% to 46.87, gold +4.71% to 372.52, the dollar +0.45% to 29.13 — level with its high close of the year — the belly +0.11% and the long bond +0.10% to 81.92. The red: oil −12.10% to 148.41, the Nasdaq top-30 fund −5.91%, the Nasdaq 100 −4.98%, the US top-20 fund −3.38%, the S&P −2.70%, the bitcoin fund −1.11% and copper miners −0.99%. The volatility index closed at 25.64, from 19.42 a week ago, after 28.18 on Thursday; the week ran from 16.57 to 28.36.
| Symbol | Name | Last | 5D | 1M | 3M | 6M | YTD |
|---|---|---|---|---|---|---|---|
| SLV | iShares Silver | 46.87 | +5.09% | -15.47% | -16.08% | -33.17% | -27.24% |
| GLD | Gold Shares | 372.52 | +4.71% | -2.55% | -4.40% | -13.56% | -6.00% |
| UUP | Invesco DB US Dollar Index Bul | 29.13 | +0.45% | +0.80% | +3.33% | +6.51% | +7.77% |
| IEF | iShares 7-10 Year Treasury Bon | 91.86 | +0.11% | +3.06% | -1.17% | -3.31% | -4.47% |
| TLT | iShares 20+ Year Treasury Bond | 81.92 | +0.10% | +6.00% | -0.73% | -4.83% | -6.01% |
| COPX | Global X - Copper Miners | 71.25 | -0.99% | -17.42% | -17.24% | -14.74% | -0.75% |
| IBIT | iShares Bitcoin | 42.88 | -1.11% | -11.57% | +17.51% | -7.17% | -13.64% |
| SPY | S&P 500 | 735.29 | -2.70% | -5.62% | -4.33% | +0.20% | +7.83% |
| TOPT | iShares Top 20 U.S. Stocks | 32.88 | -3.38% | -7.80% | -3.01% | -0.45% | +5.28% |
| QQQ | Invesco QQQ | 656.1 | -4.98% | -13.63% | -8.19% | -5.70% | +6.80% |
| QTOP | iShares Nasdaq Top 30 Stocks | 33.75 | -5.91% | -16.19% | -9.90% | -8.24% | +5.60% |
| USO | United States Oil LP | 148.41 | -12.10% | +2.42% | +24.85% | +10.80% | +114.59% |
Sorted by Weighted Alpha (leaders → laggards) · Barchart, close of week.
The tech ETFs — three of twenty-one green, and the AI funds at the bottom. The red was led by the chips and the AI baskets: the WisdomTree AI fund −13.09%, SMH −11.20%, cybersecurity −9.89%, the fabless fund −9.37%, defence technology −8.75%, XSD −8.01%, quantum −7.82%, cloud −7.74%. Software (IGV) fell 5.19% to 98.88 — back under 100. The green was small: video games +6.32%, lithium and batteries +1.84%, fintech +1.32%. Last week the chips ended flat because Monday to Wednesday paid for Friday. This week nothing paid for Thursday.
| Symbol | Name | Last | 5D | 1M | 3M | 6M | YTD |
|---|---|---|---|---|---|---|---|
| ESPO | VanEck Video Gaming and eSport | 102.27 | +6.32% | +4.74% | +6.20% | +11.60% | -1.29% |
| LIT | Global X - Lithium & Battery T | 60.91 | +1.84% | -14.30% | -15.88% | -33.45% | -6.09% |
| FINX | Global X - FinTech | 24.2 | +1.32% | -2.56% | -7.18% | -7.02% | -17.76% |
| FDN | First Dow Jones Internet Index | 260.58 | -2.12% | -12.20% | -8.07% | -2.35% | -3.19% |
| DTCR | Global X - Data Center & Digit | 24.87 | -2.74% | -10.48% | -11.12% | -17.95% | +17.87% |
| NLR | VanEck Uranium and Nuclear | 88.44 | -3.61% | -19.18% | -22.33% | -40.74% | -28.79% |
| BOTZ | Global X - Robotics & Artifici | 31.05 | -3.63% | -14.16% | -15.94% | -22.14% | -14.30% |
| DAPP | VanEck Digital Transformation | 13.63 | -3.81% | -28.45% | -21.80% | -38.63% | -17.54% |
| IGV | iShares Expanded Tech-Software | 98.88 | -5.19% | -11.05% | -0.54% | +12.59% | -6.44% |
| AIQ | Global X - Artificial Intellig | 56.89 | -5.40% | -15.15% | -8.17% | -5.66% | +11.86% |
| SNSR | Global X - Internet of Things | 43.96 | -5.54% | -12.70% | -9.12% | -5.60% | +18.95% |
| GRID | First NASDAQ Clean Edge Smart | 154.21 | -6.26% | -16.33% | -16.91% | -22.01% | +0.78% |
| ARKK | ARK Innovation | 75.46 | -6.55% | -16.61% | -0.36% | -5.18% | -1.90% |
| CLOU | Global X - Cloud Computing | 25.85 | -7.74% | -11.05% | -1.56% | +15.76% | +14.28% |
| QTUM | Defiance Quantum | 123.37 | -7.82% | -21.62% | -17.33% | -14.12% | +12.50% |
| XSD | S&P Semiconductor | 415.88 | -8.01% | -25.53% | -20.09% | -21.82% | +29.32% |
| SHLD | Global X - Defense Tech | 58.2 | -8.75% | -3.10% | -14.13% | -14.36% | -10.17% |
| SMHX | VanEck Fabless Semiconductor | 46.9 | -9.37% | -27.60% | -20.19% | -13.91% | +23.32% |
| CIBR | First Nasdaq Cybersecurity | 91.04 | -9.89% | -15.81% | -5.55% | +29.74% | +27.42% |
| SMH | VanEck Semiconductor | 463.96 | -11.20% | -26.65% | -18.81% | -15.61% | +28.83% |
| WTAI | WisdomTree Artificial Intellig | 31.53 | -13.09% | -30.86% | -22.42% | -20.34% | +8.20% |
Sorted by Weighted Alpha (leaders → laggards) · Barchart, close of week.
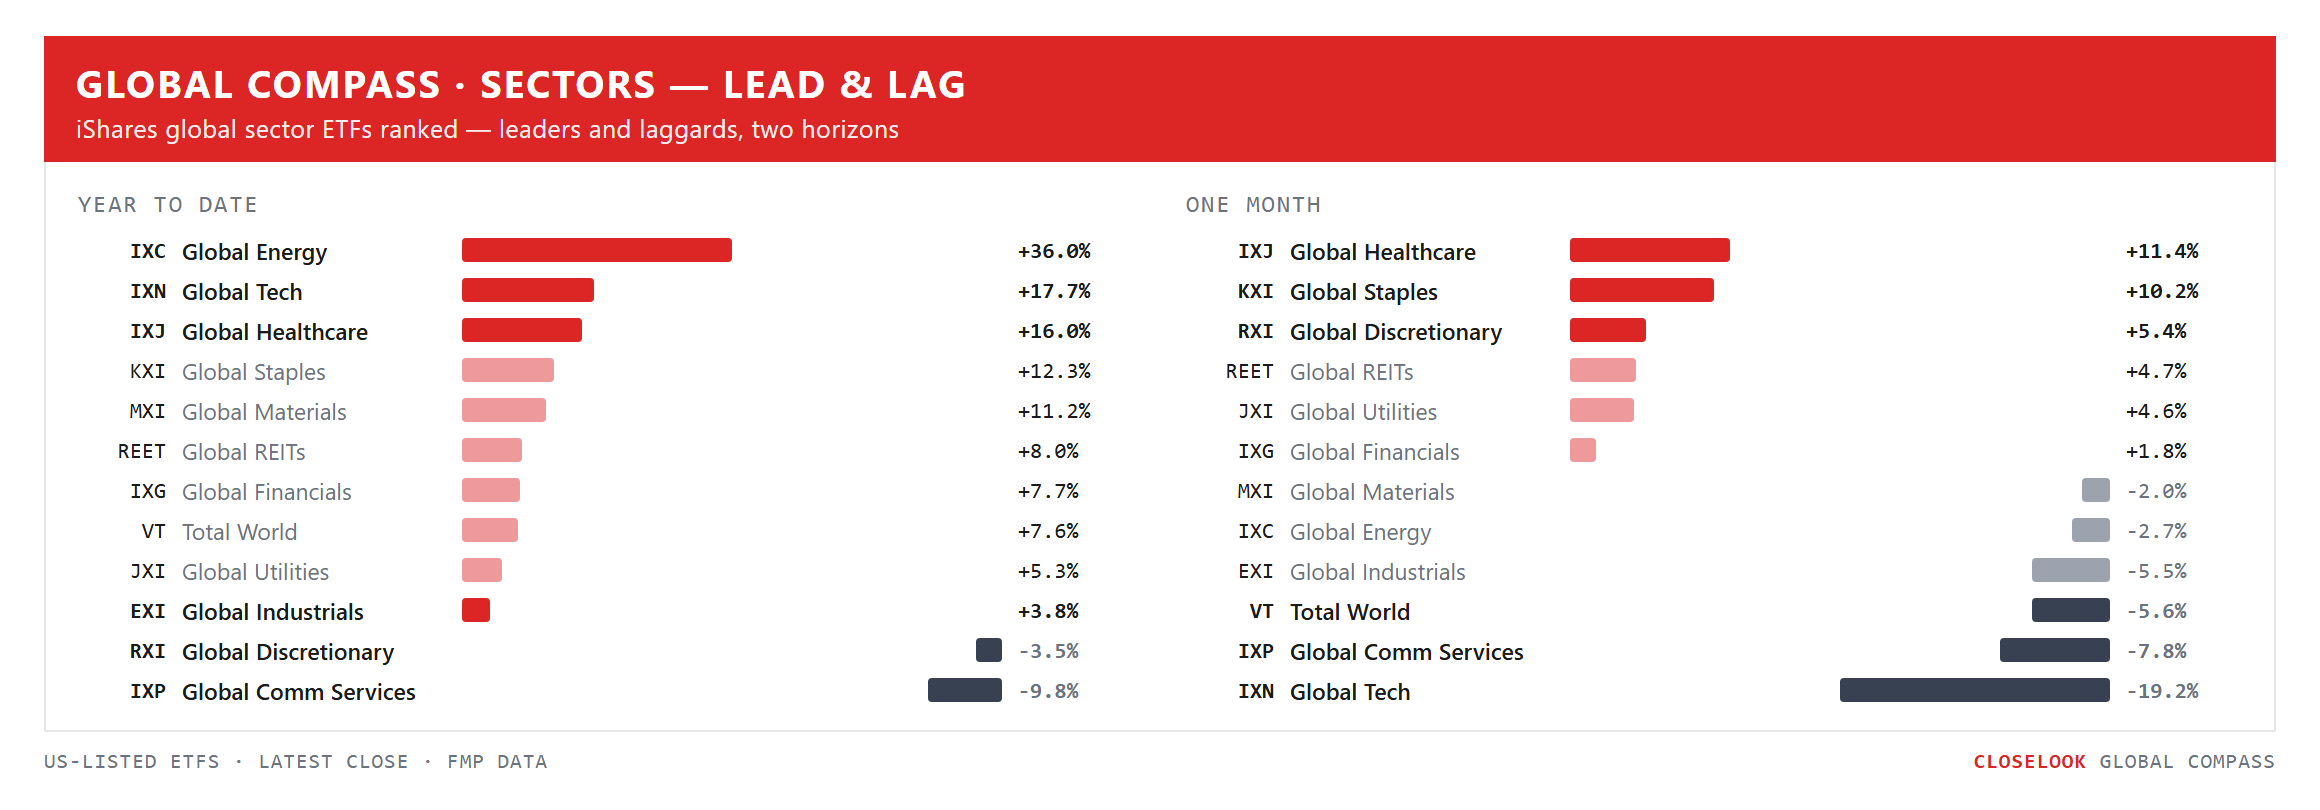
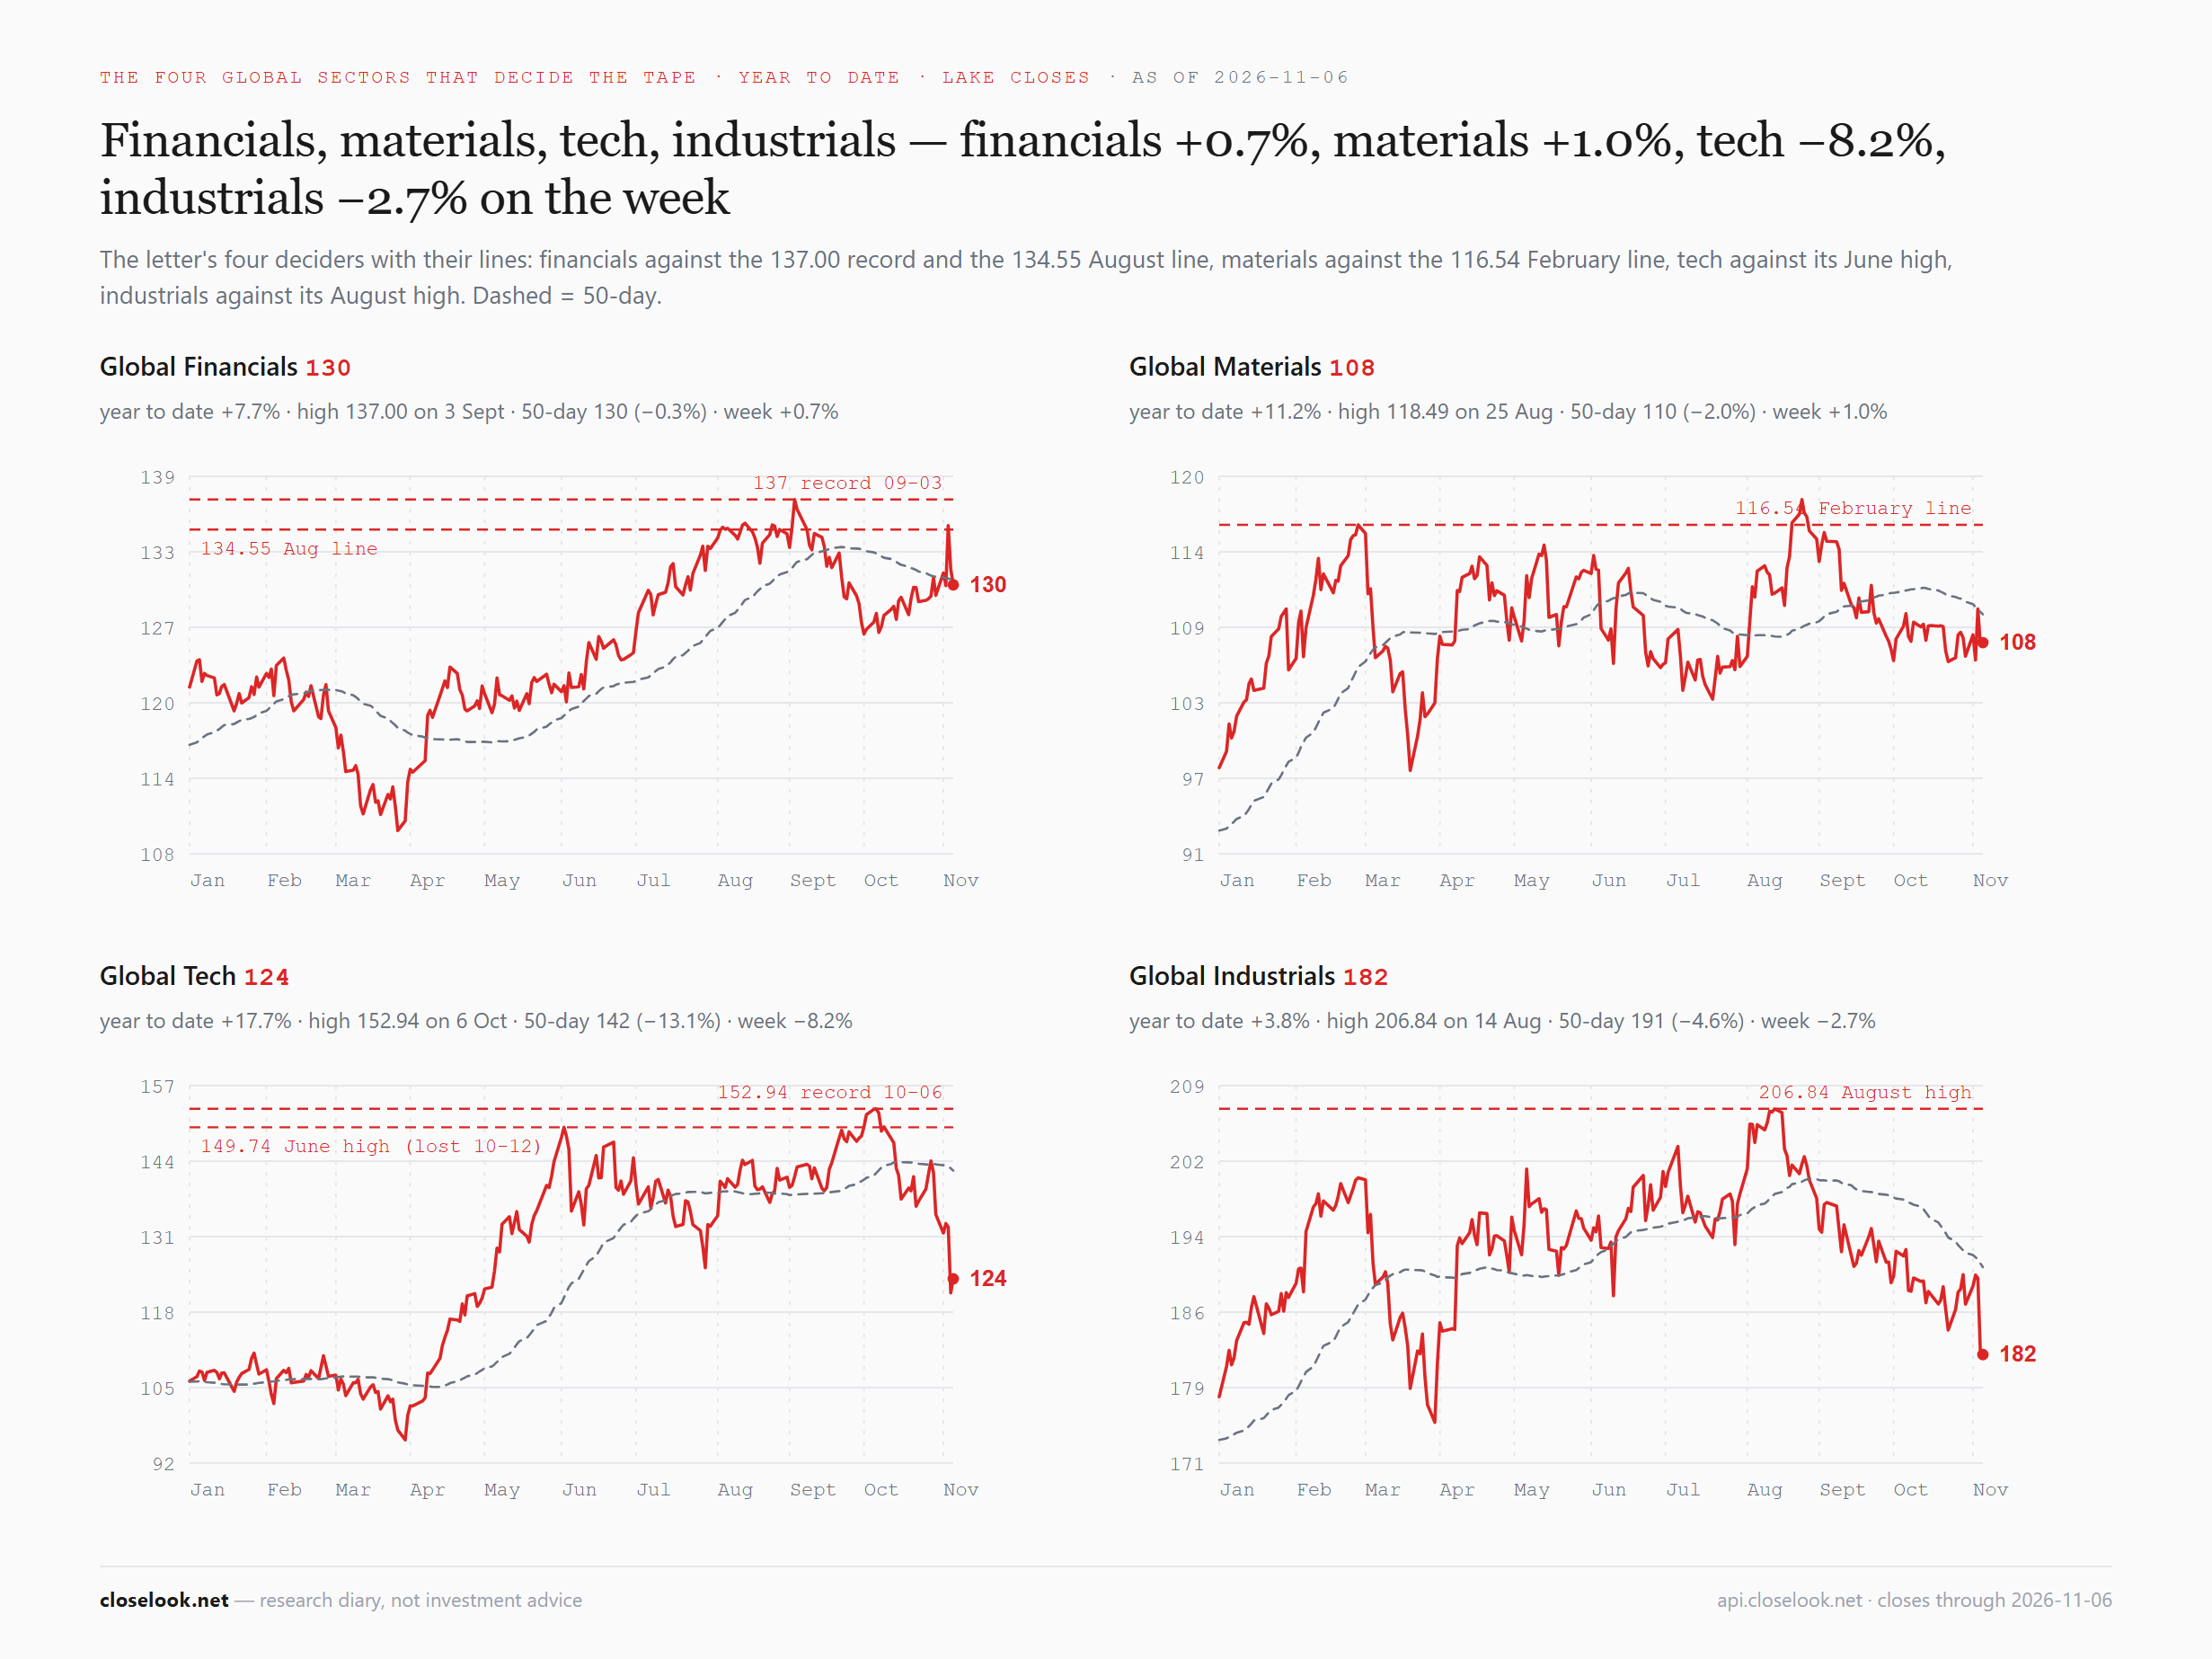
The global sectors — seven of eleven green, and energy and tech at the bottom. Discretionary +3.49%, communication +2.64%, real estate +1.97%, materials +0.98%, financials +0.67%, staples +0.58%, health care +0.27%. The red: utilities −0.13%, industrials −2.72%, technology −8.25% to 123.58 and energy −11.15% to 57.03 — from a record close of 64.19 a week ago. Seven sectors up and the world index down 2.3%: once again the two that fell are the two that weigh.
| Symbol | Name | Last | 5D | 1M | 3M | 6M | YTD |
|---|---|---|---|---|---|---|---|
| RXI | iShares Global Consumer Discre | 197.96 | +3.49% | +5.37% | -2.63% | -1.73% | -3.55% |
| IXP | iShares Global Comm Services | 109.39 | +2.64% | -7.85% | -7.05% | -12.72% | -9.76% |
| REET | iShares Global REIT | 26.95 | +1.97% | +4.70% | -4.06% | -2.28% | +8.02% |
| MXI | iShares Global Materials | 107.5 | +0.98% | -2.02% | -3.14% | -4.56% | +11.24% |
| IXG | iShares Global Financials | 130.05 | +0.67% | +1.83% | -3.36% | +6.18% | +7.67% |
| KXI | iShares Global Consumer Staple | 72.58 | +0.58% | +10.17% | +4.79% | +5.13% | +12.27% |
| IXJ | iShares Global Healthcare | 112.96 | +0.27% | +11.43% | +11.54% | +21.65% | +15.98% |
| JXI | iShares Global Utilities | 82.81 | -0.13% | +4.58% | +0.45% | -4.79% | +5.29% |
| VT | Vanguard Total World Stock | 151.73 | -2.32% | -5.58% | -5.12% | -2.15% | +7.56% |
| EXI | iShares Global Industrials | 182.02 | -2.72% | -5.51% | -10.53% | -9.33% | +3.81% |
| IXN | iShares Global Tech | 123.58 | -8.25% | -19.20% | -11.32% | -4.11% | +17.70% |
| IXC | iShares Global Energy | 57.03 | -11.15% | -2.68% | +5.36% | +4.72% | +36.01% |
Sorted by Weighted Alpha (leaders → laggards) · Barchart, close of week.
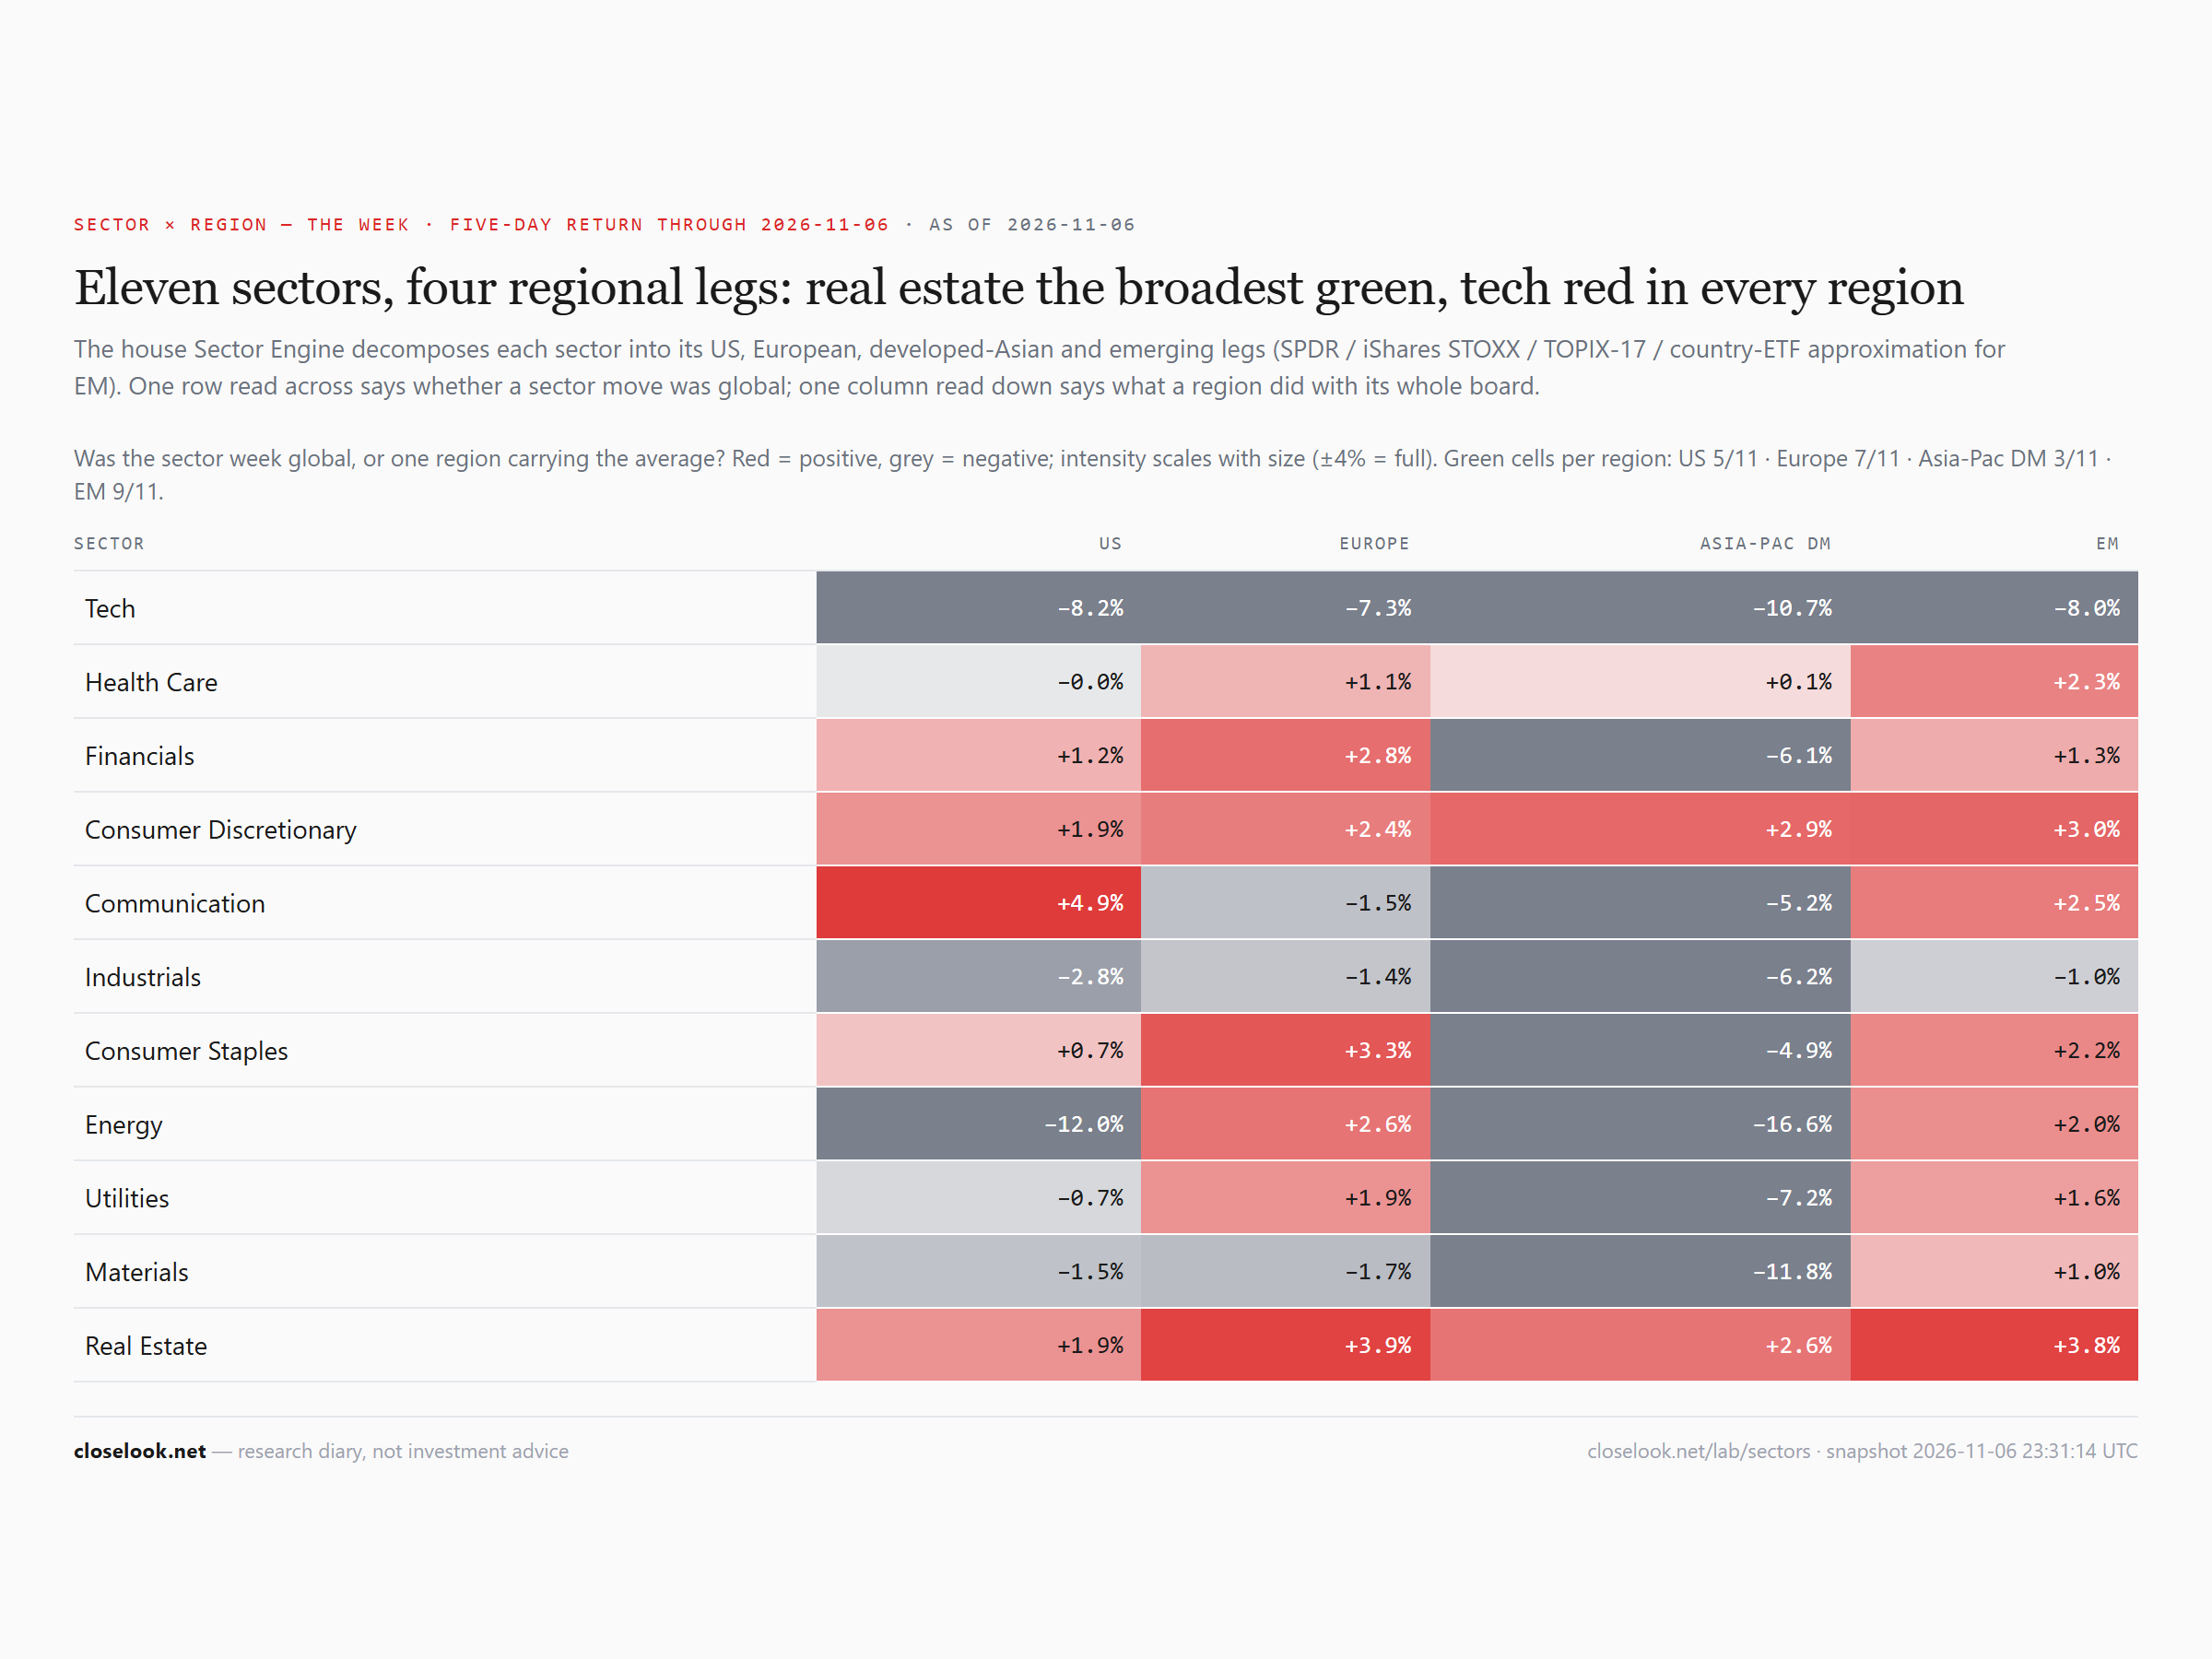
Was the sector week global, or one region carrying it? Technology fell in every region: America −8.2%, Europe −7.3%, developed Asia −10.7%, emerging markets −8.0%. That is the week's one global fact. Energy split by region: America −12.0% and developed Asia −16.6%, against Europe +2.6% and the emerging markets +2.0%. Communication services: America +4.9%, Europe −1.5% — a US-minus-Europe spread of +6.4 points, a reversal of last week's −8.4. Health care rose most in the emerging markets, +2.3%.
The Global Compass
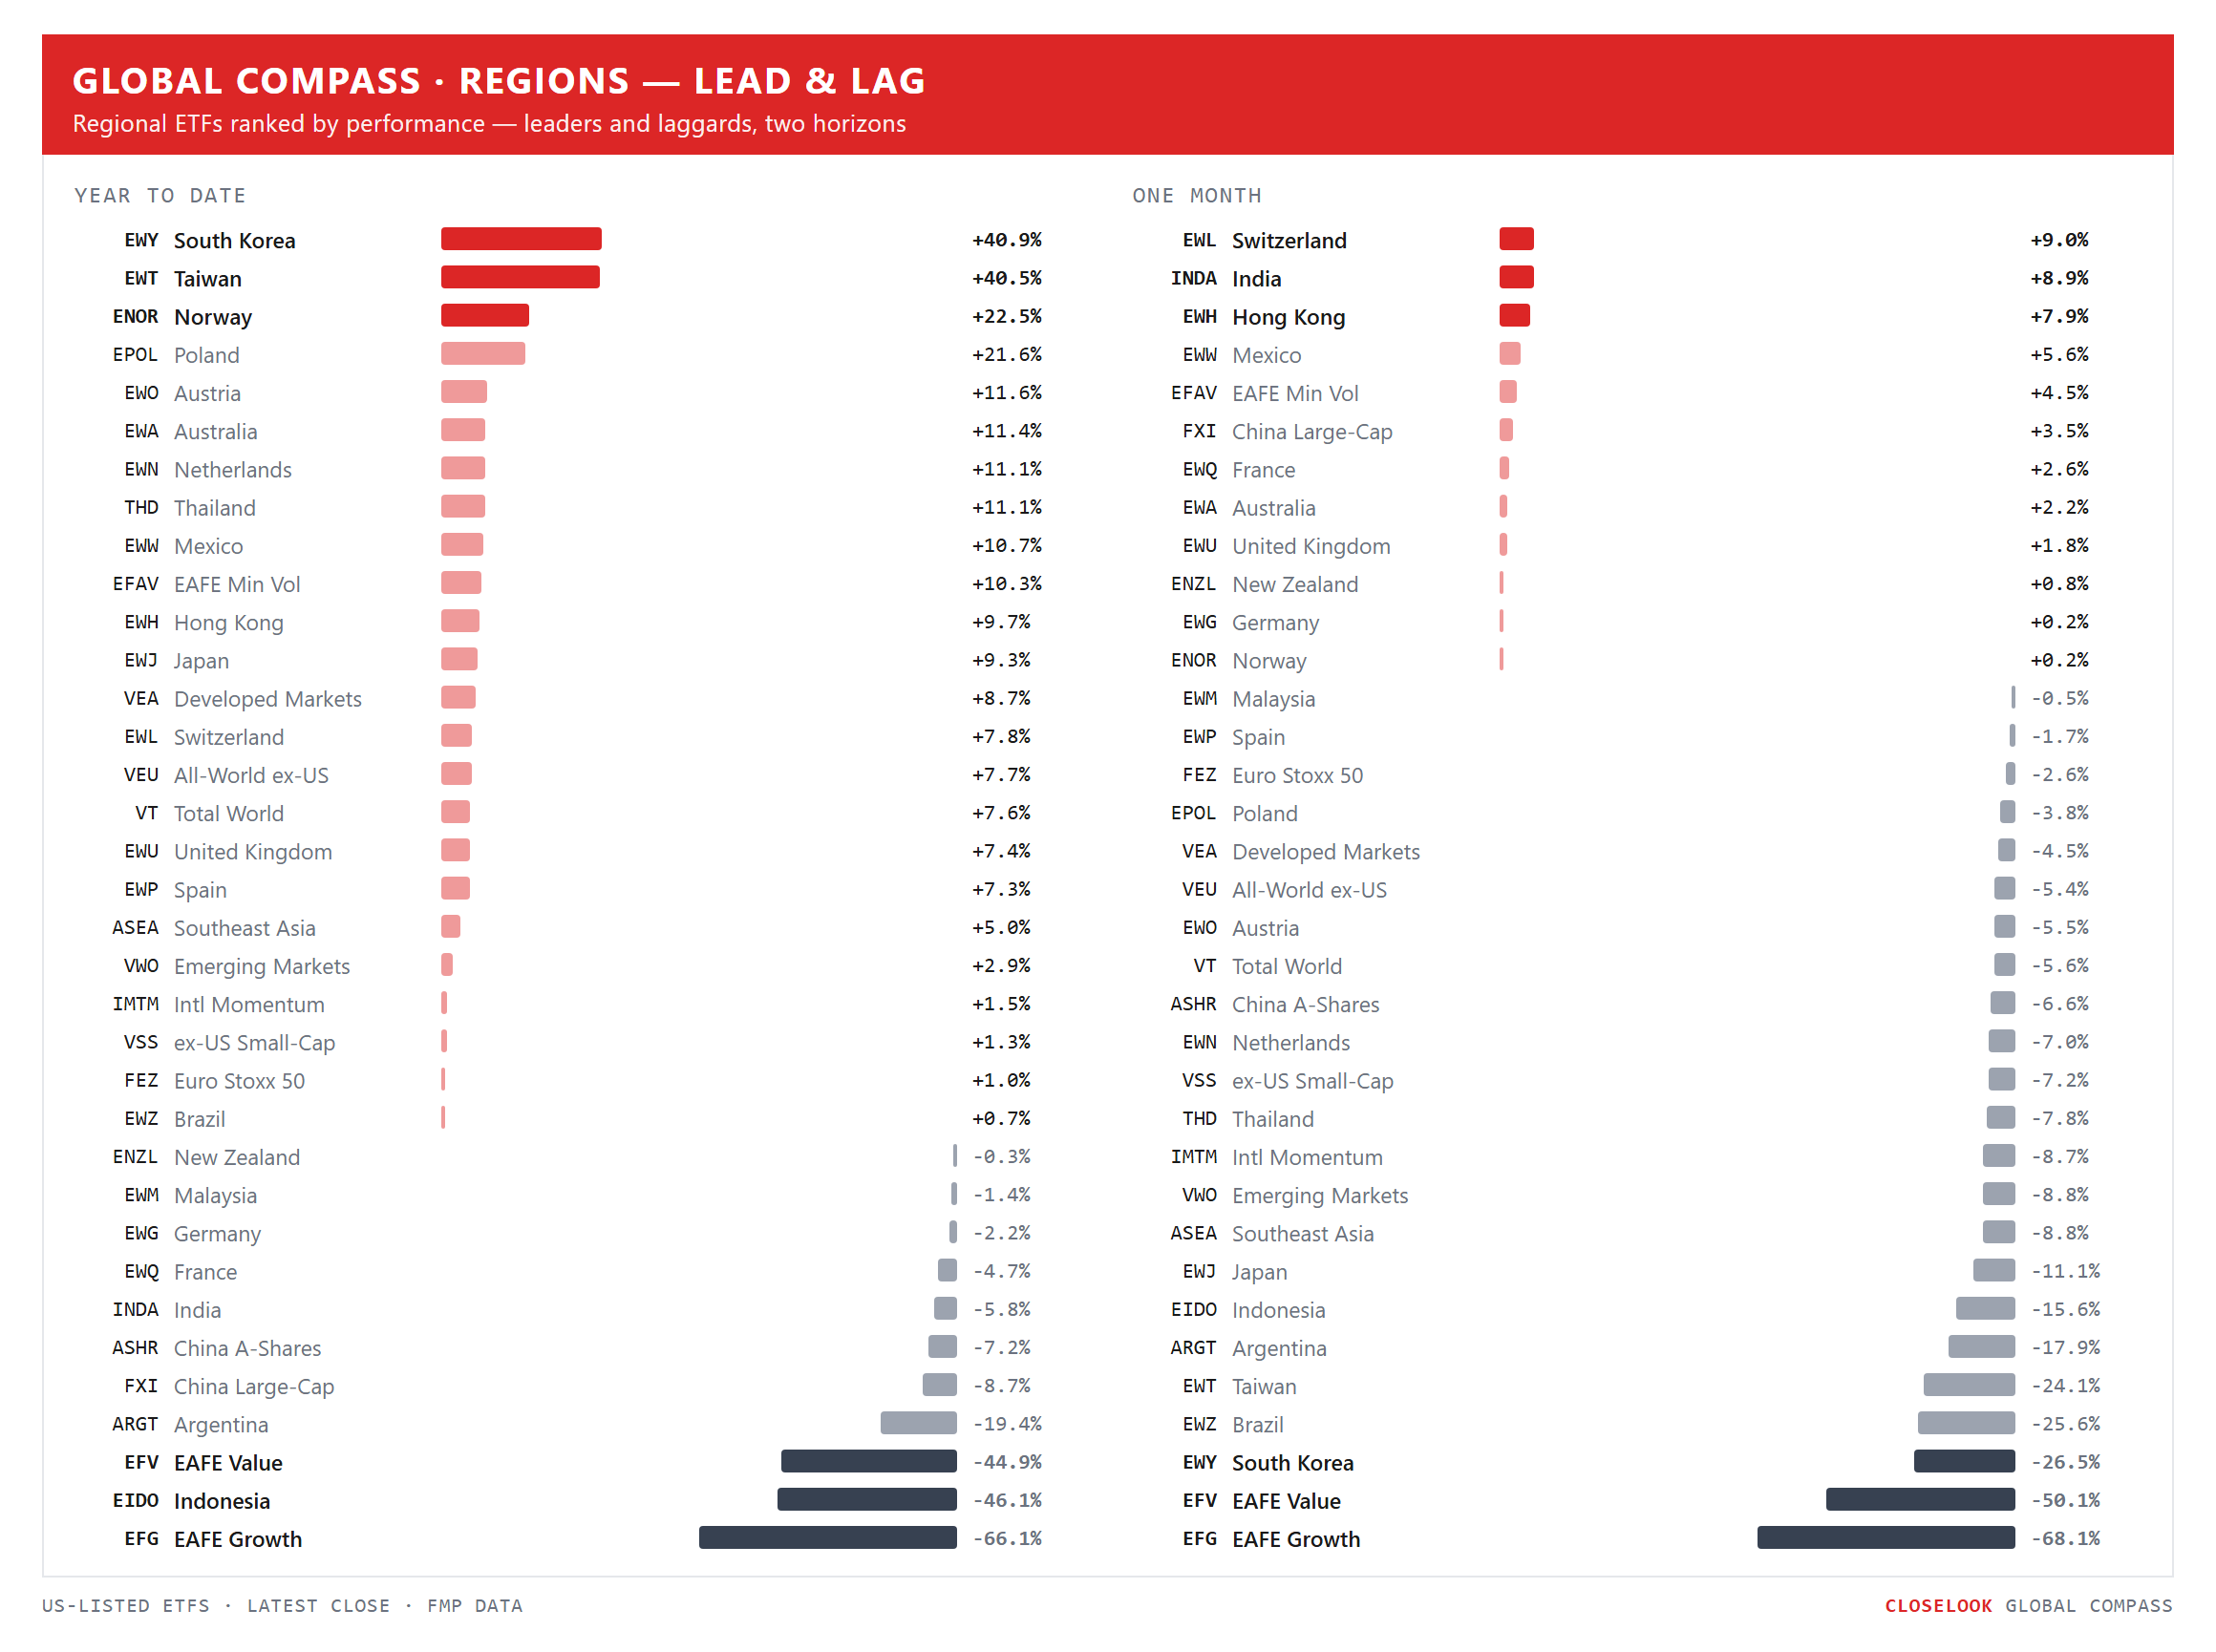
Regions: emerging over developed, for the first time in four weeks. VWO −0.40% against VEA −2.22%. The emerging basket carries India and China, two of the week's winners, and Taiwan, its worst; the developed basket carries Japan and Korea without China and India to offset them.
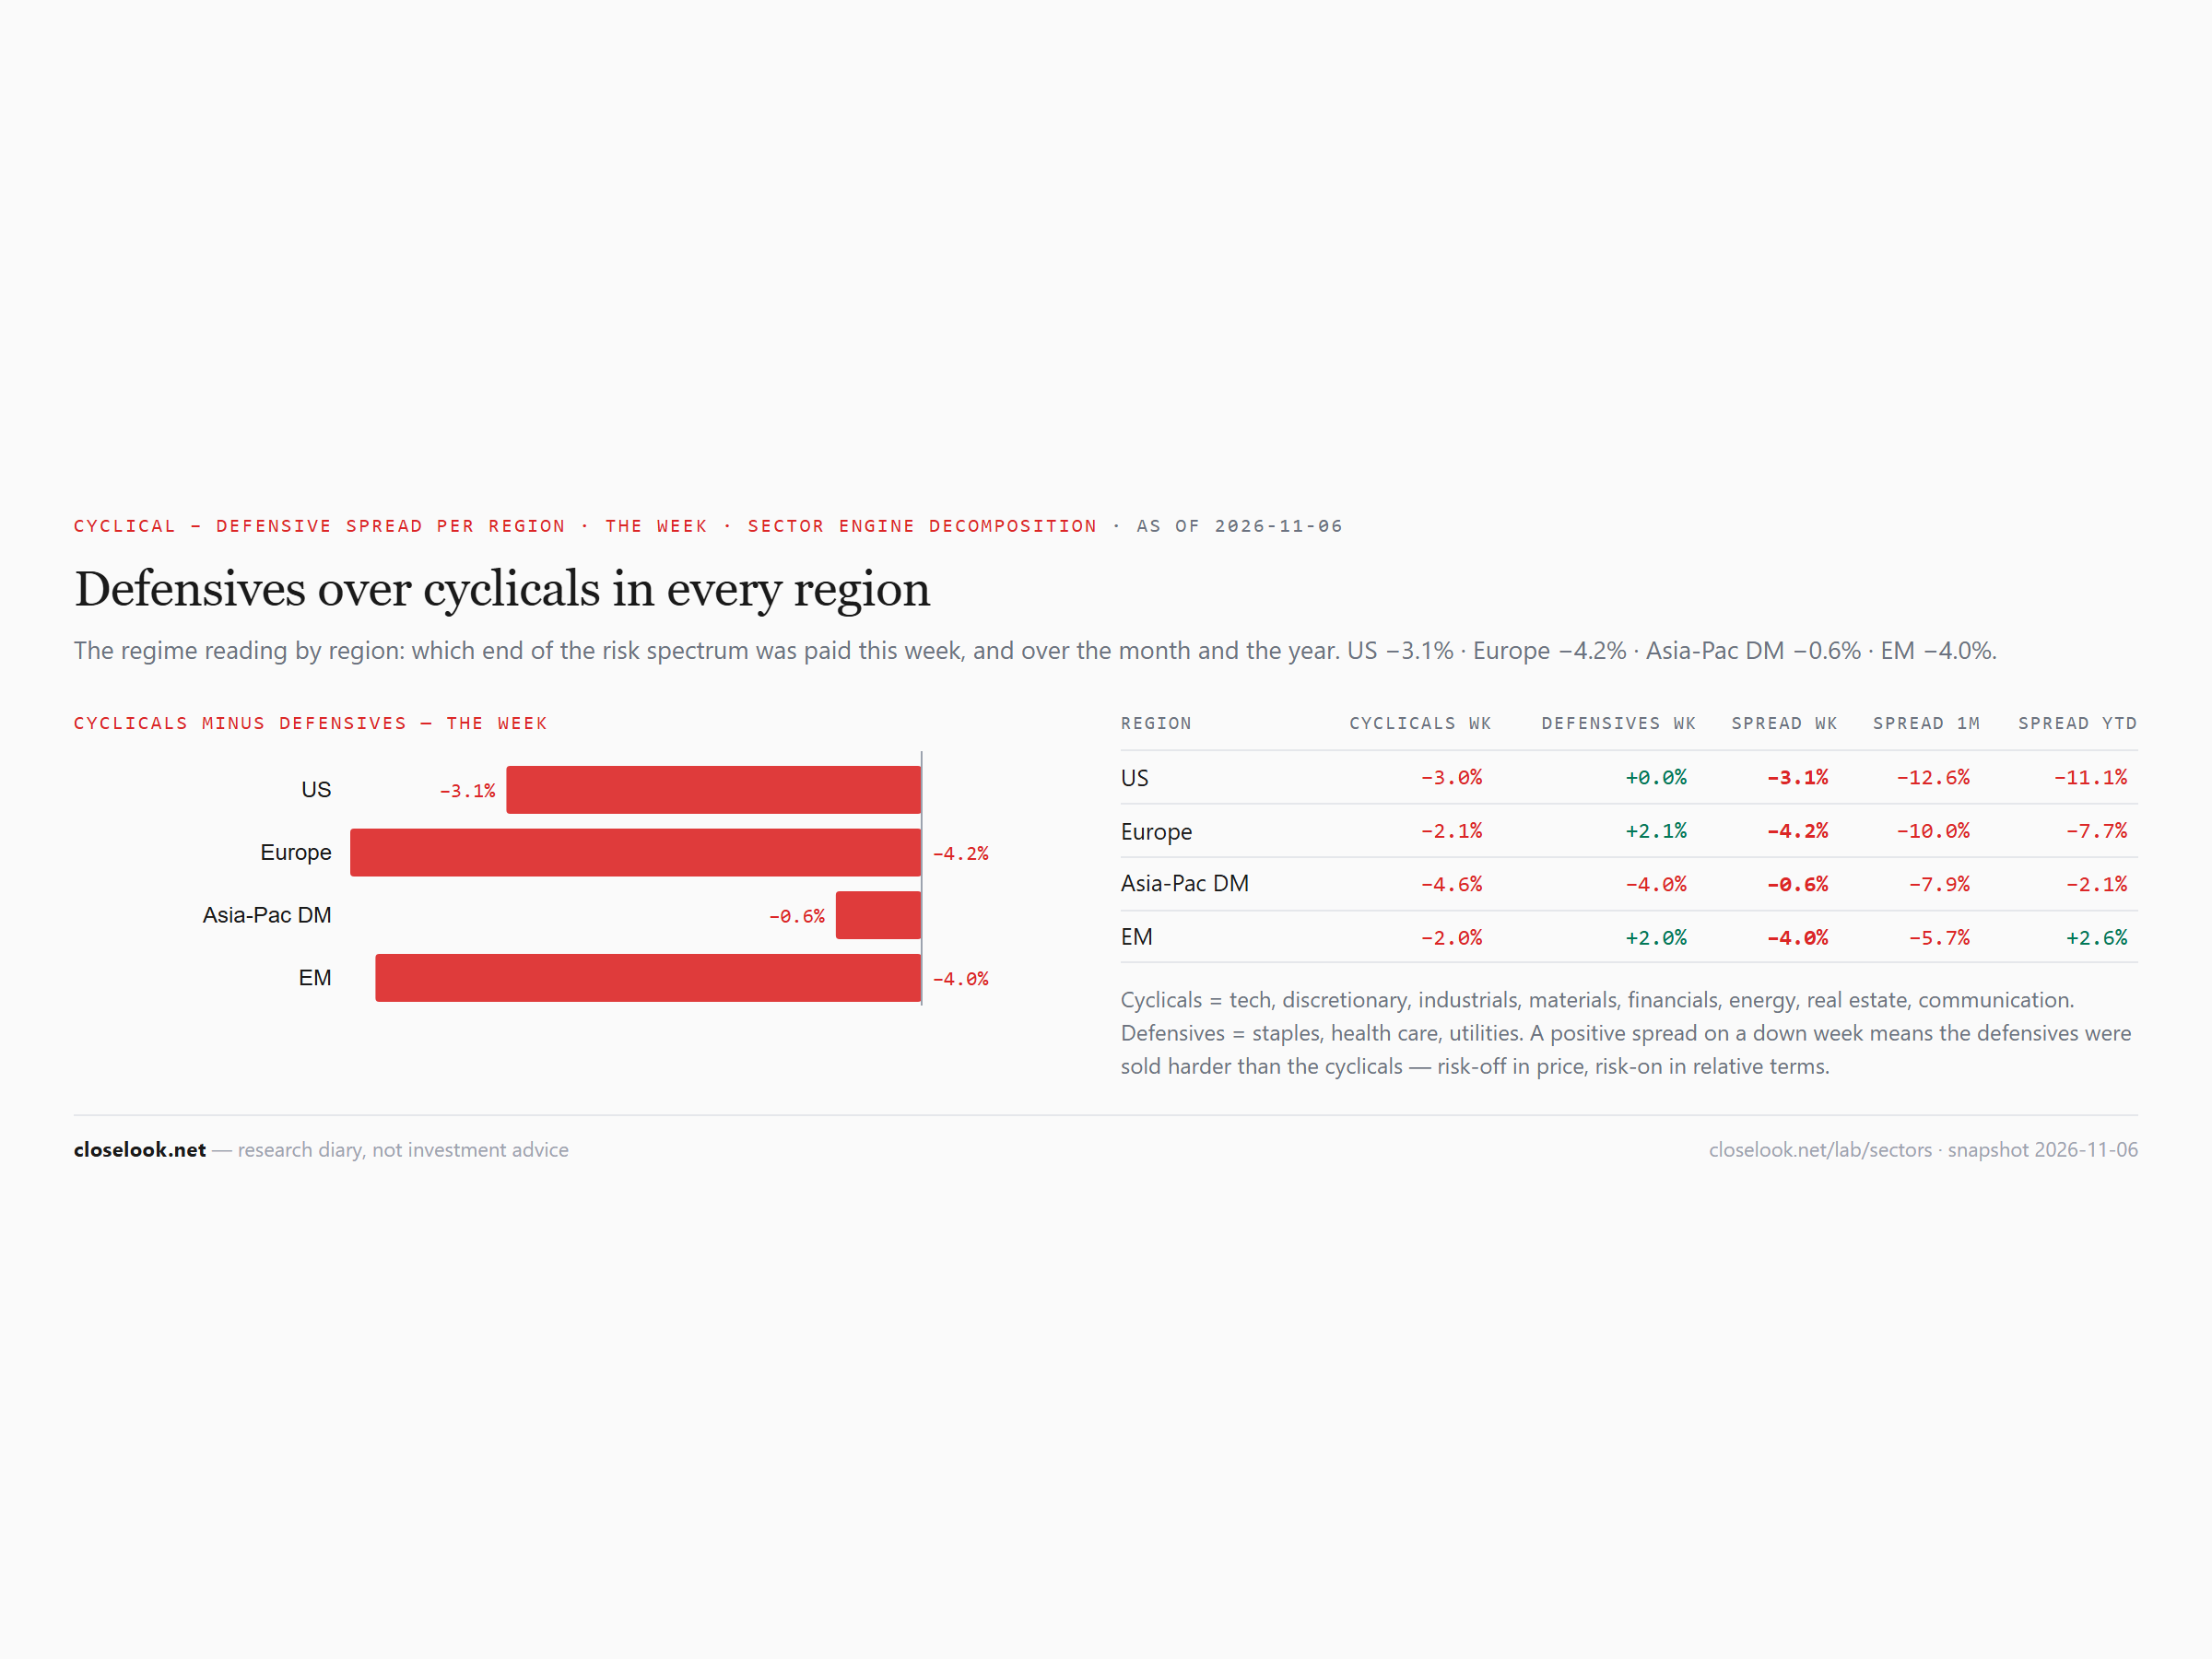
Sectors: defensives over cyclicals in all four regions, a fifth week. The engine's cyclical-minus-defensive spread was −3.1 points in the US, −4.2 in Europe, −0.6 in developed Asia and −4.0 in the emerging markets. Last week three regions leaned defensive; this week all four did. On the month the US spread is −12.6 points, and on the year −11.1.
Sectors: the leaders' bench. Technology 123.58, 19.2% under its October 6 record. Industrials 182.02, 12.0% under August. Financials 130.05, 5.1% under the September 3 record. Materials 107.50, 9.3% under its August high.
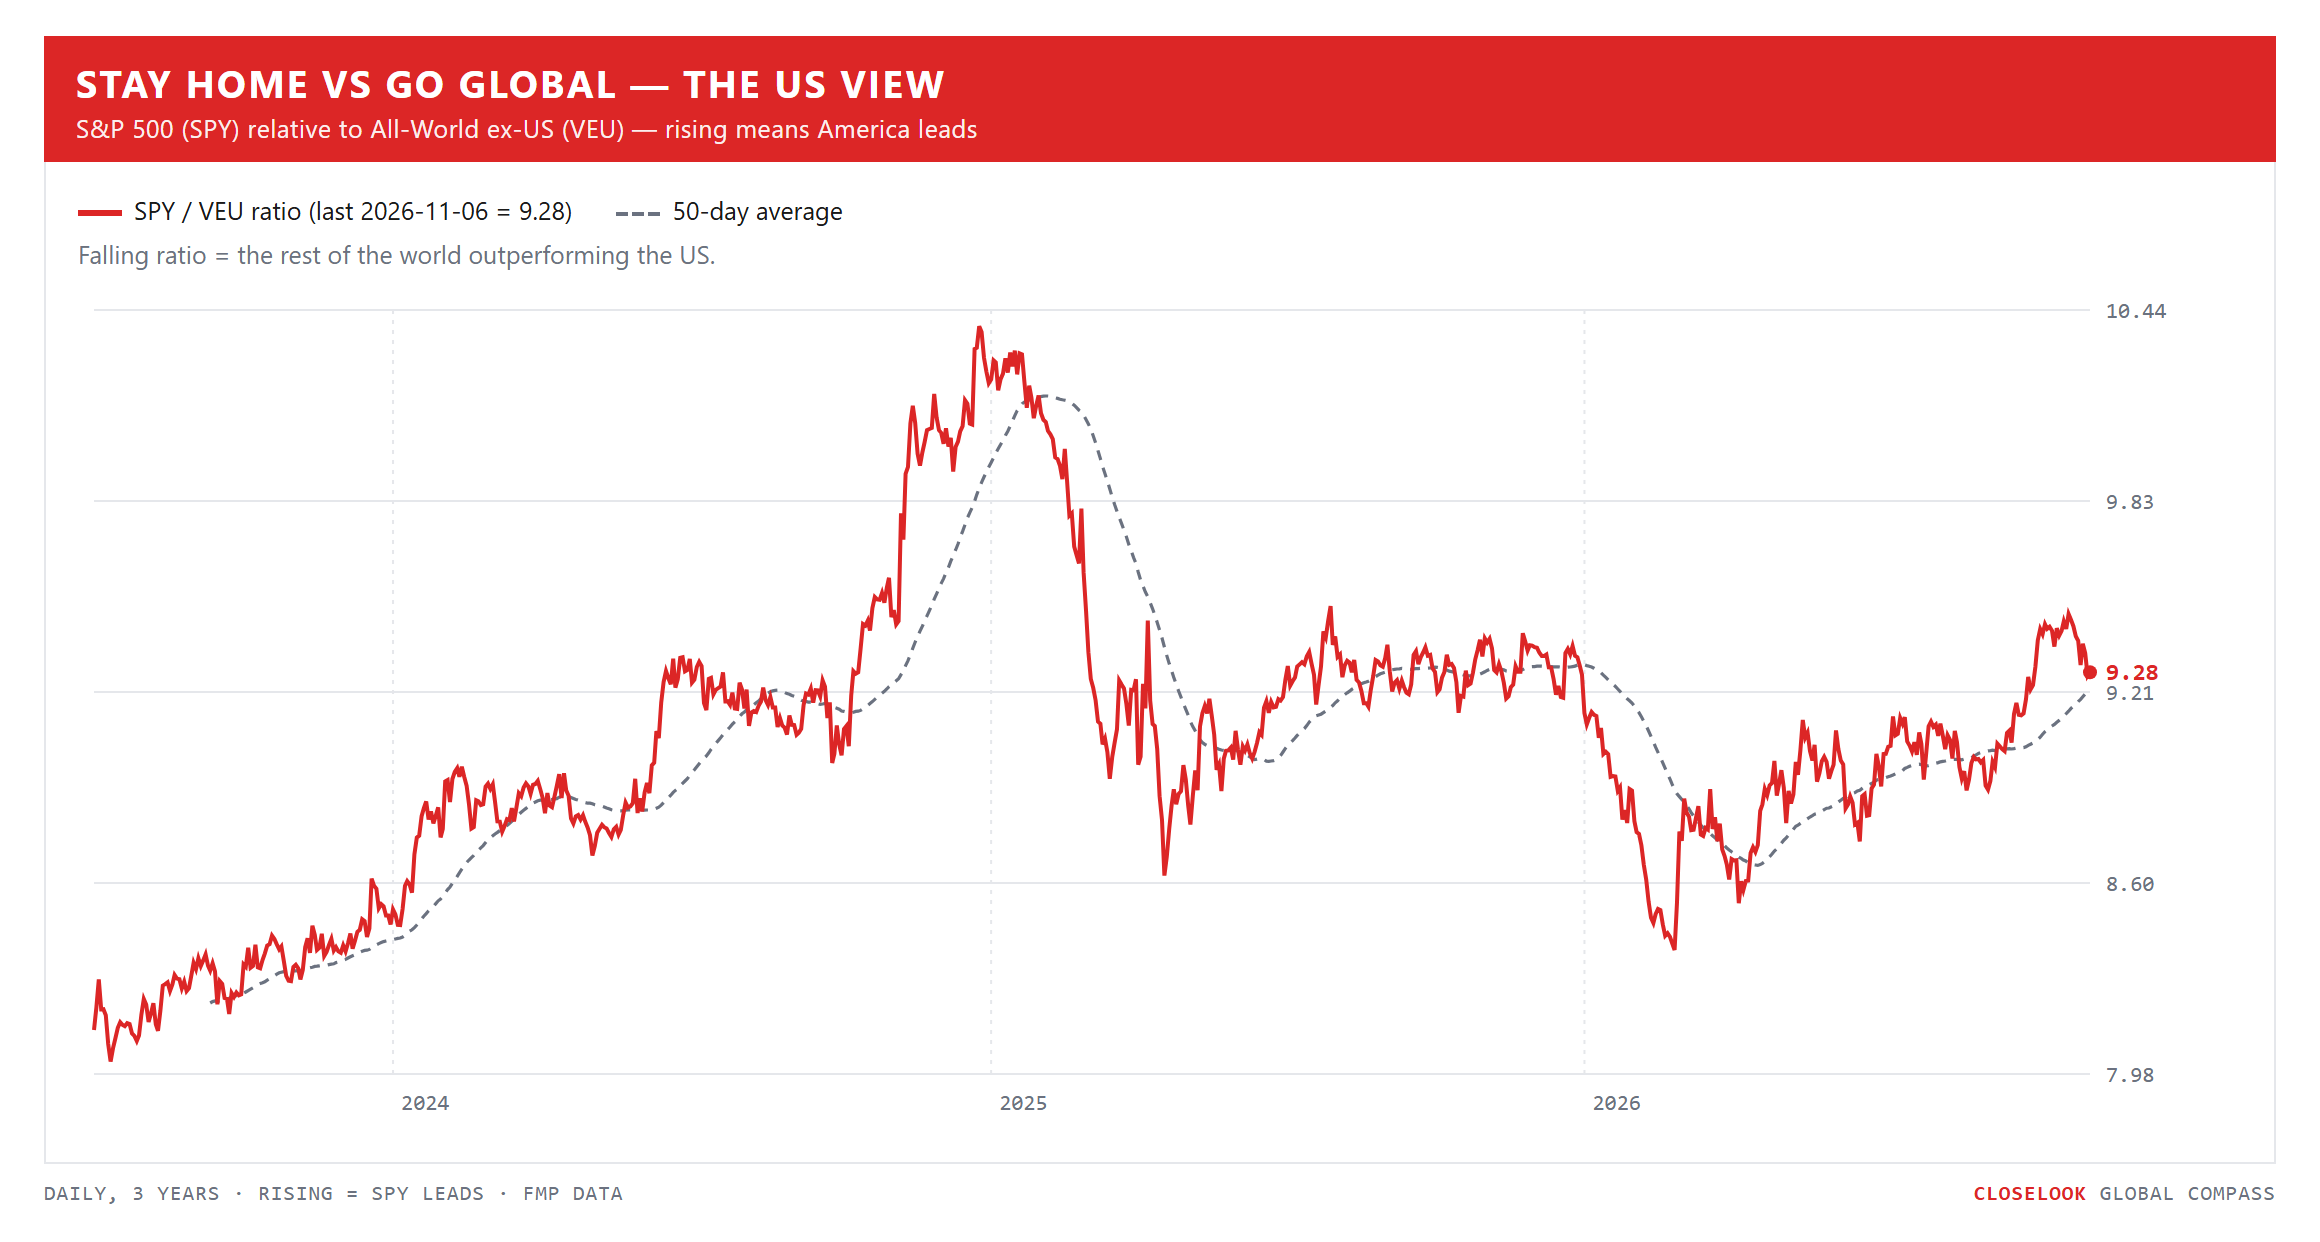
Stay home vs go global — the US view. This week the world beat America again: VEU −1.64%, VT −2.32%, SPY −2.70%. On the year the three now sit within three tenths of a point of each other: +7.83% for America, +7.74% for the world ex-US, +7.56% for the world.
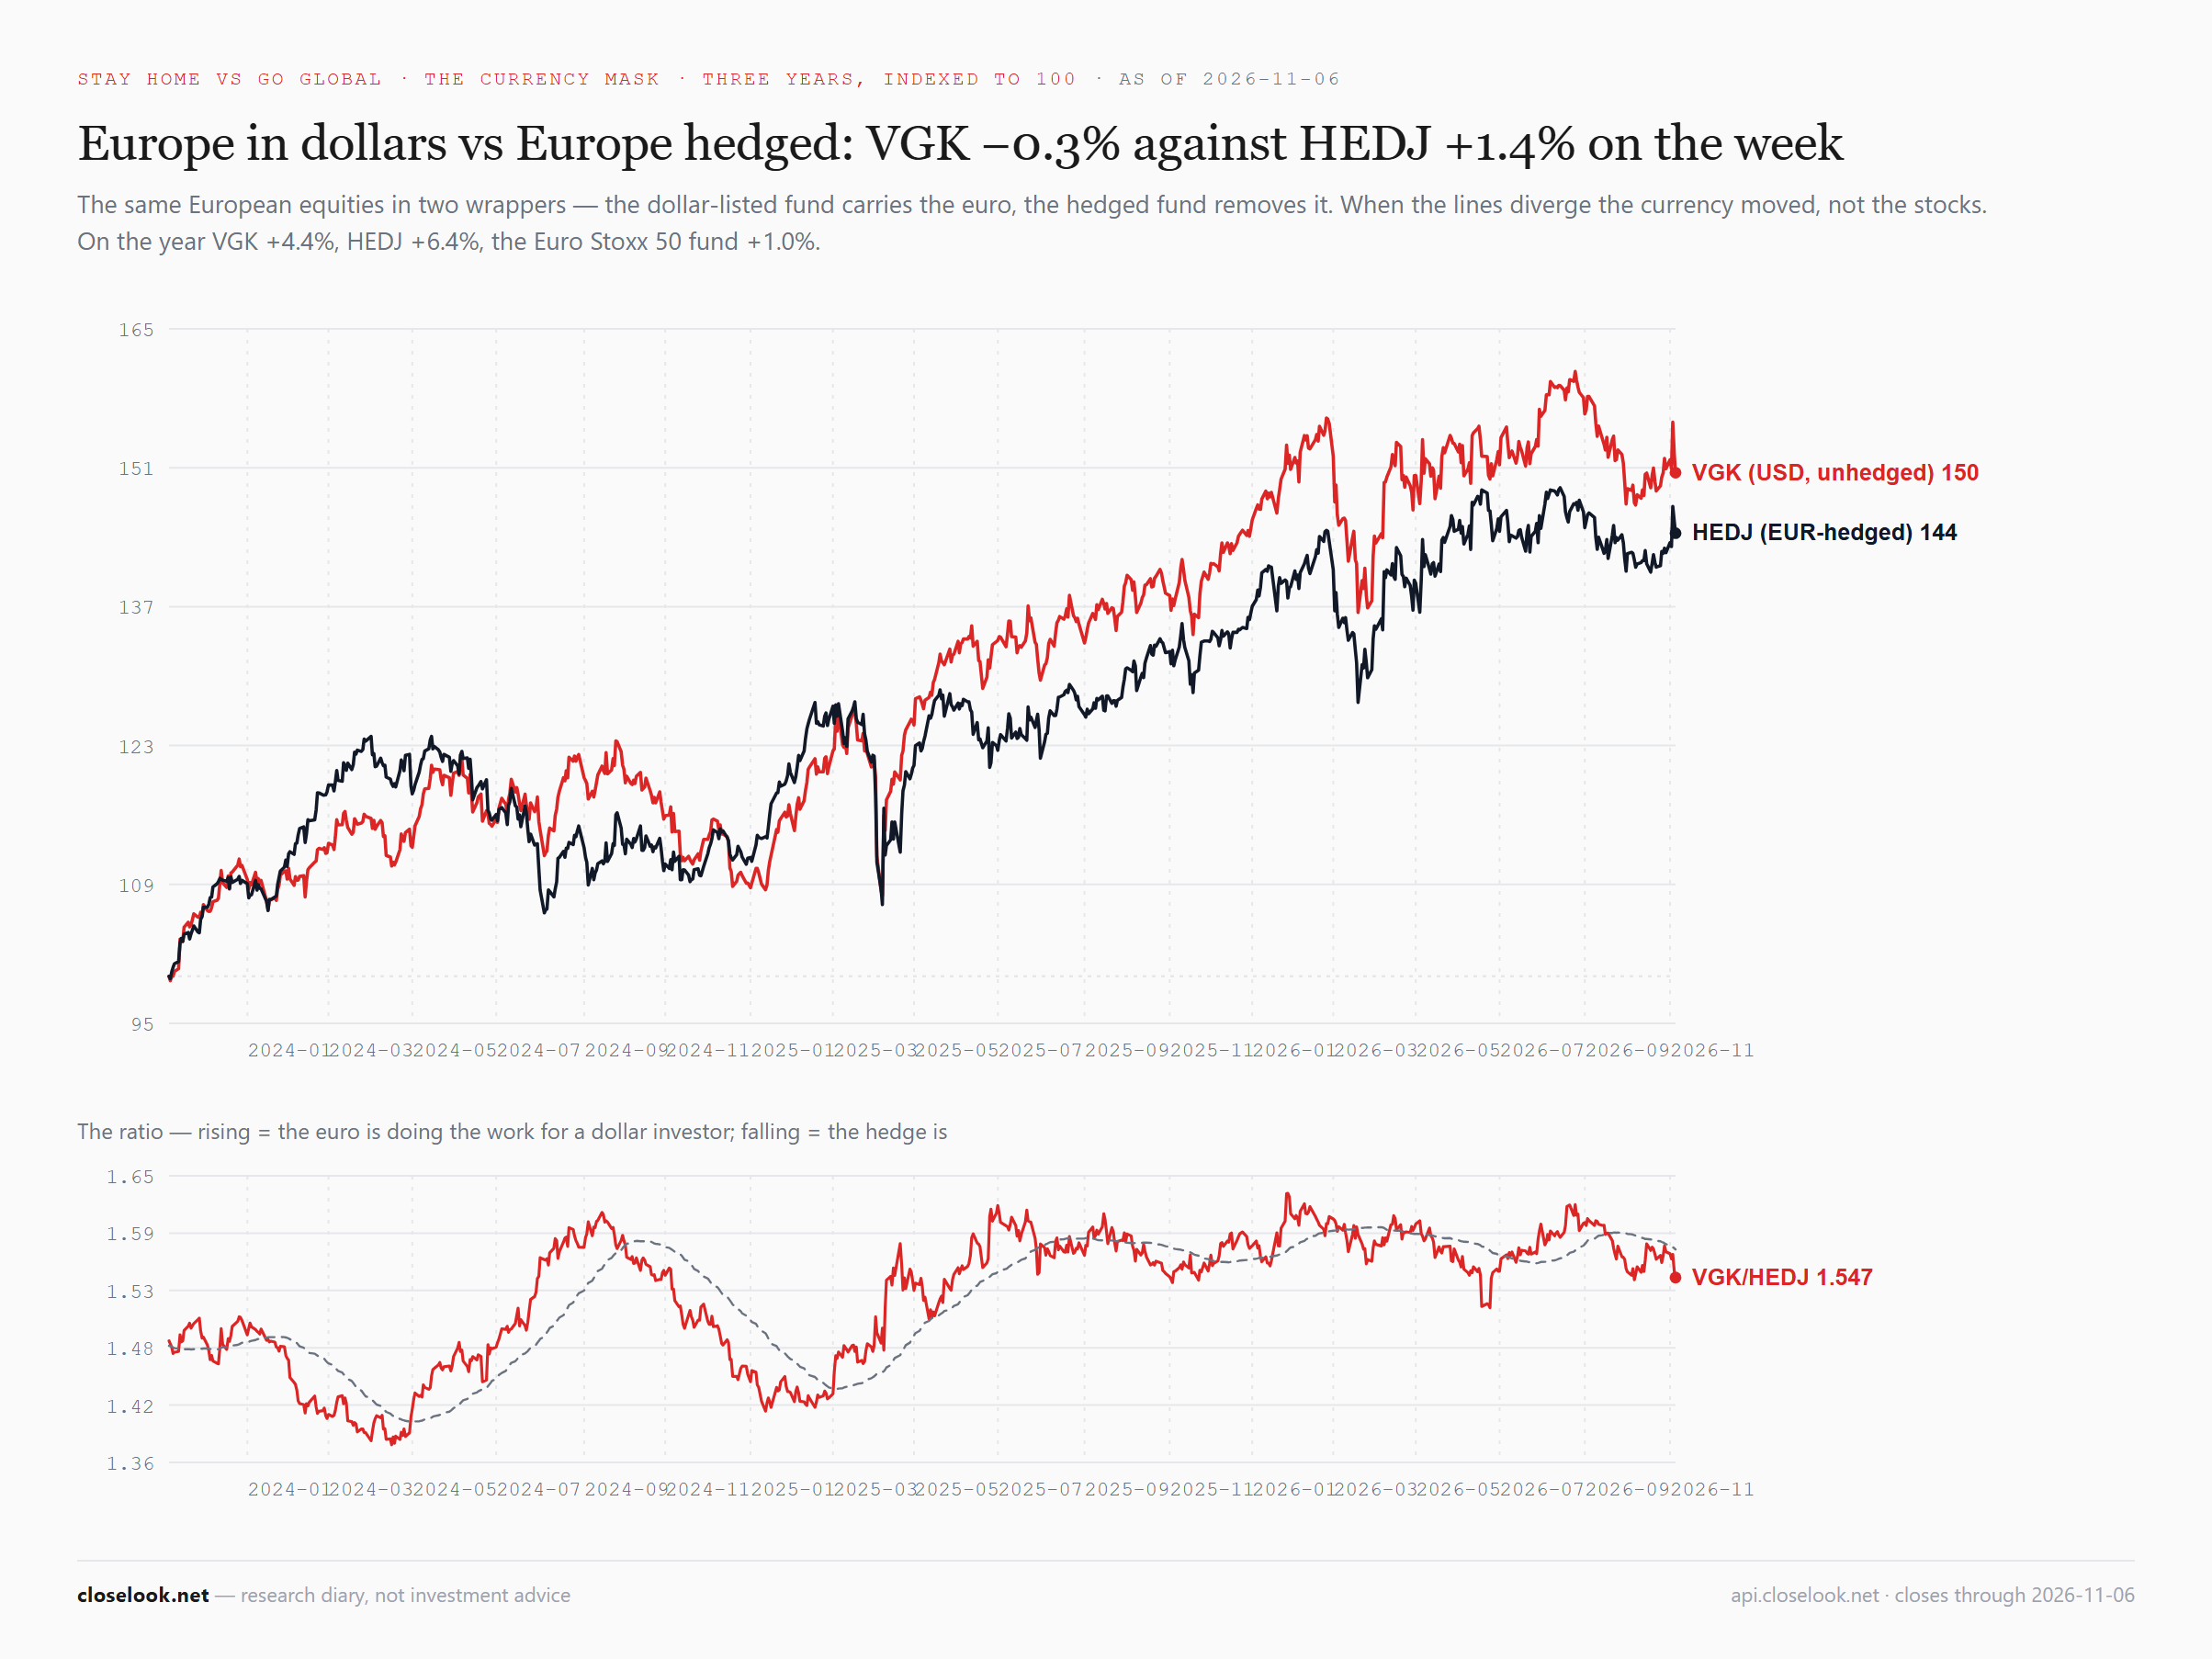
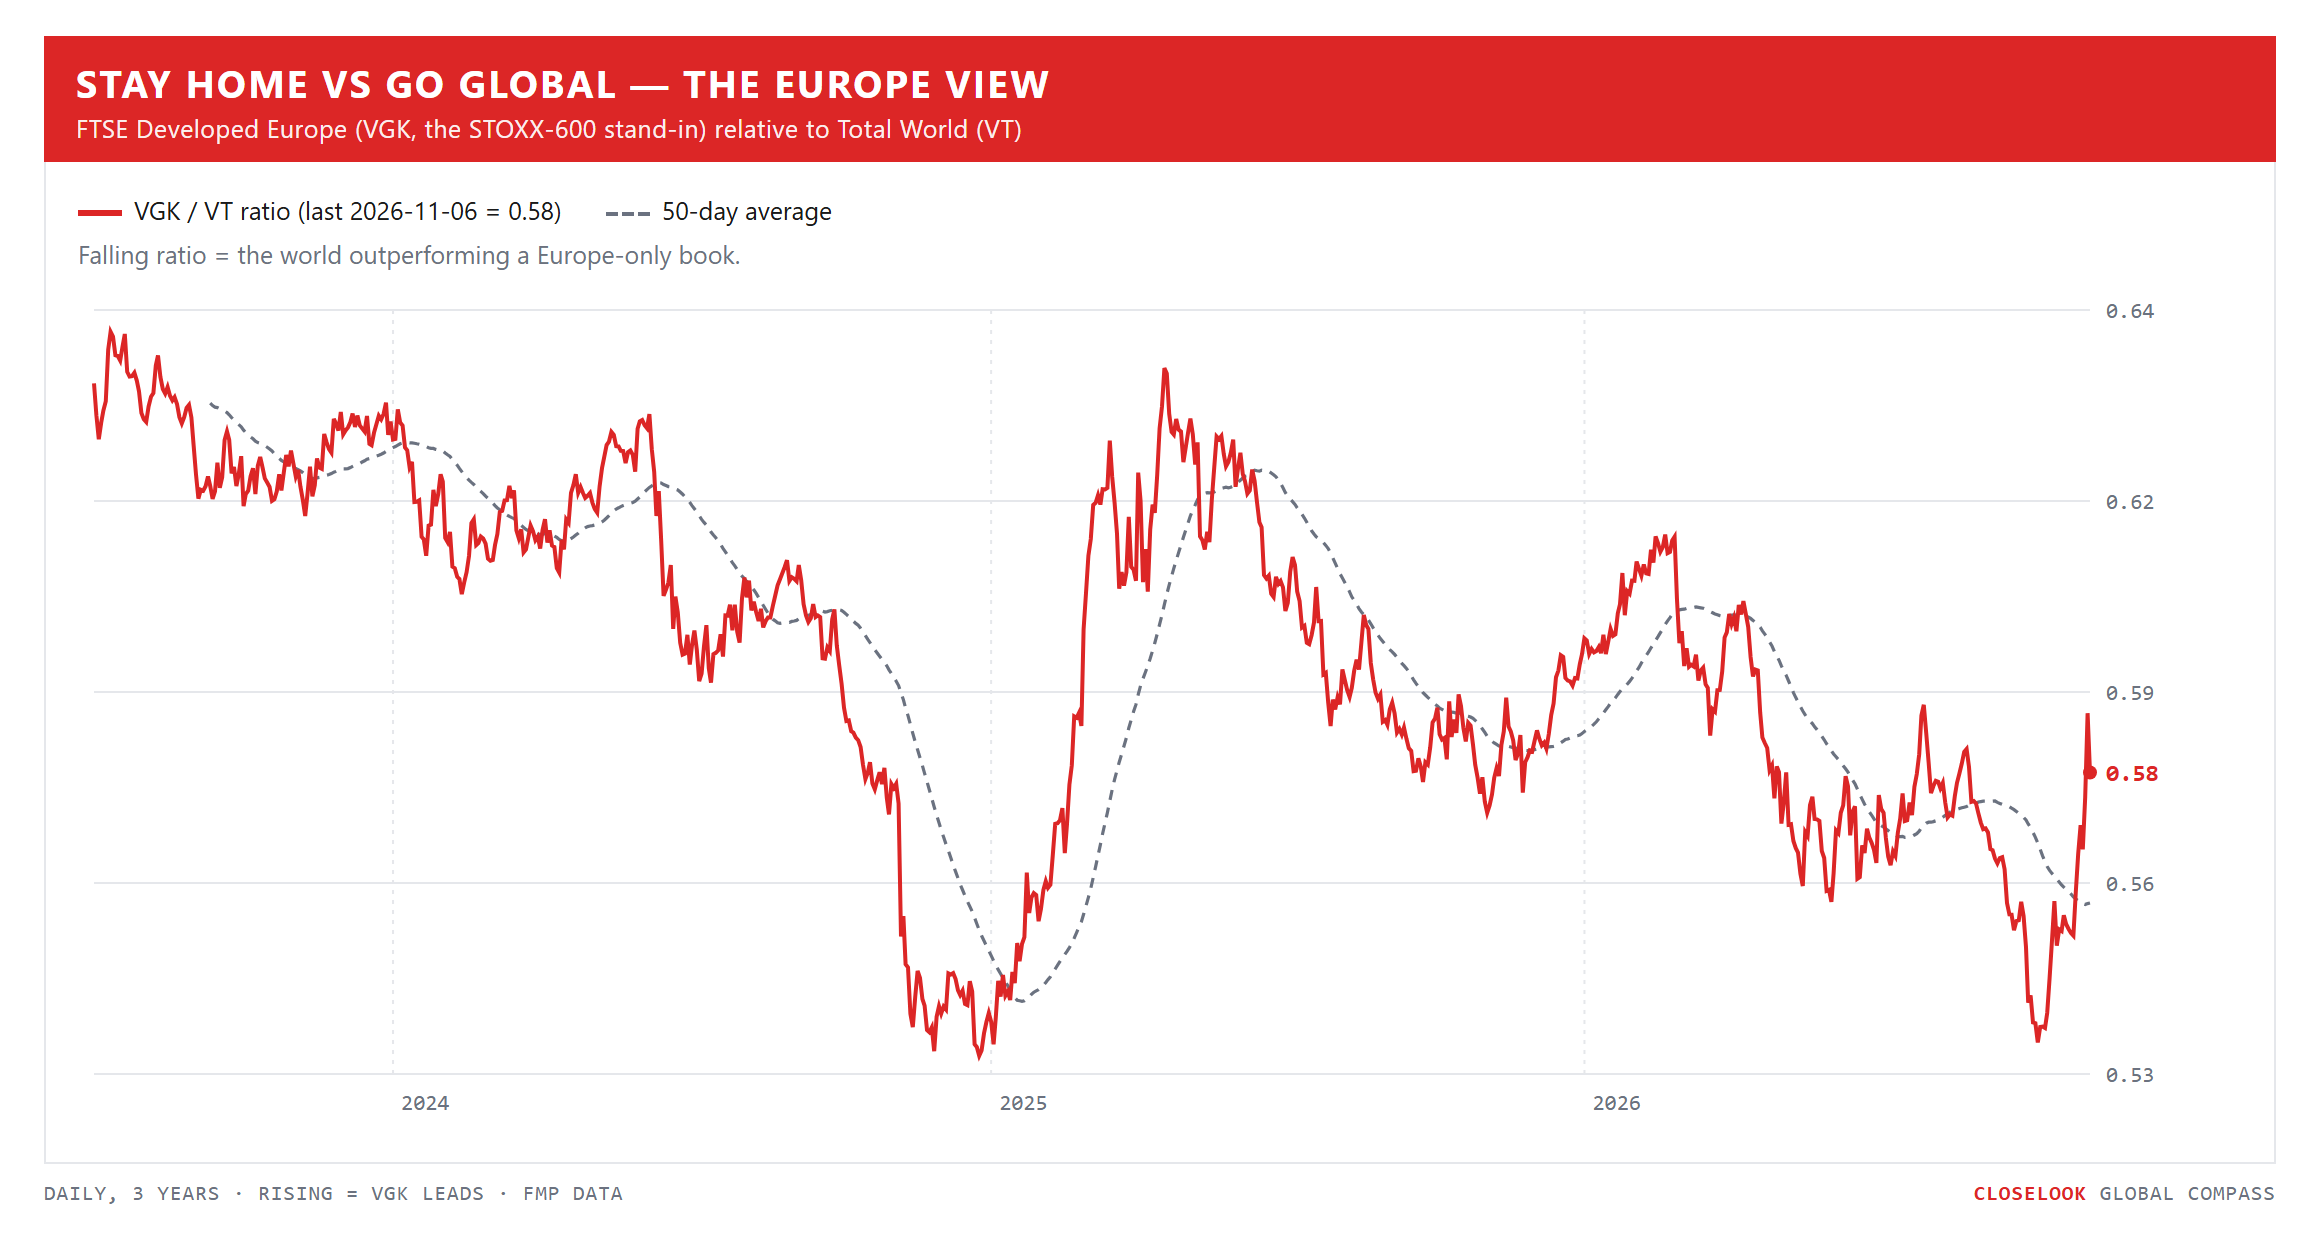
Stay home vs go global — the Europe view: flat in euros, lower in dollars. In local terms: the STOXX 600 +0.24% to 648.33, the DAX +0.01% to 25,820, the CAC +1.62% to 8,099, the Euro Stoxx 50 +0.64% to 6,170 — and outside the euro the FTSE 100 −0.93% to 10,630 and Switzerland's SMI −0.10% to 14,797, after a record close of 15,023 on Wednesday. Spain's IBEX rose 3.84%. The dollar-listed Europe fund fell 0.26%, the euro-hedged one rose 1.36%; the euro ended at 1.1147. The French fund rose 1.54% to 42.89, 4.0% above the low of the year it made on 12 October.
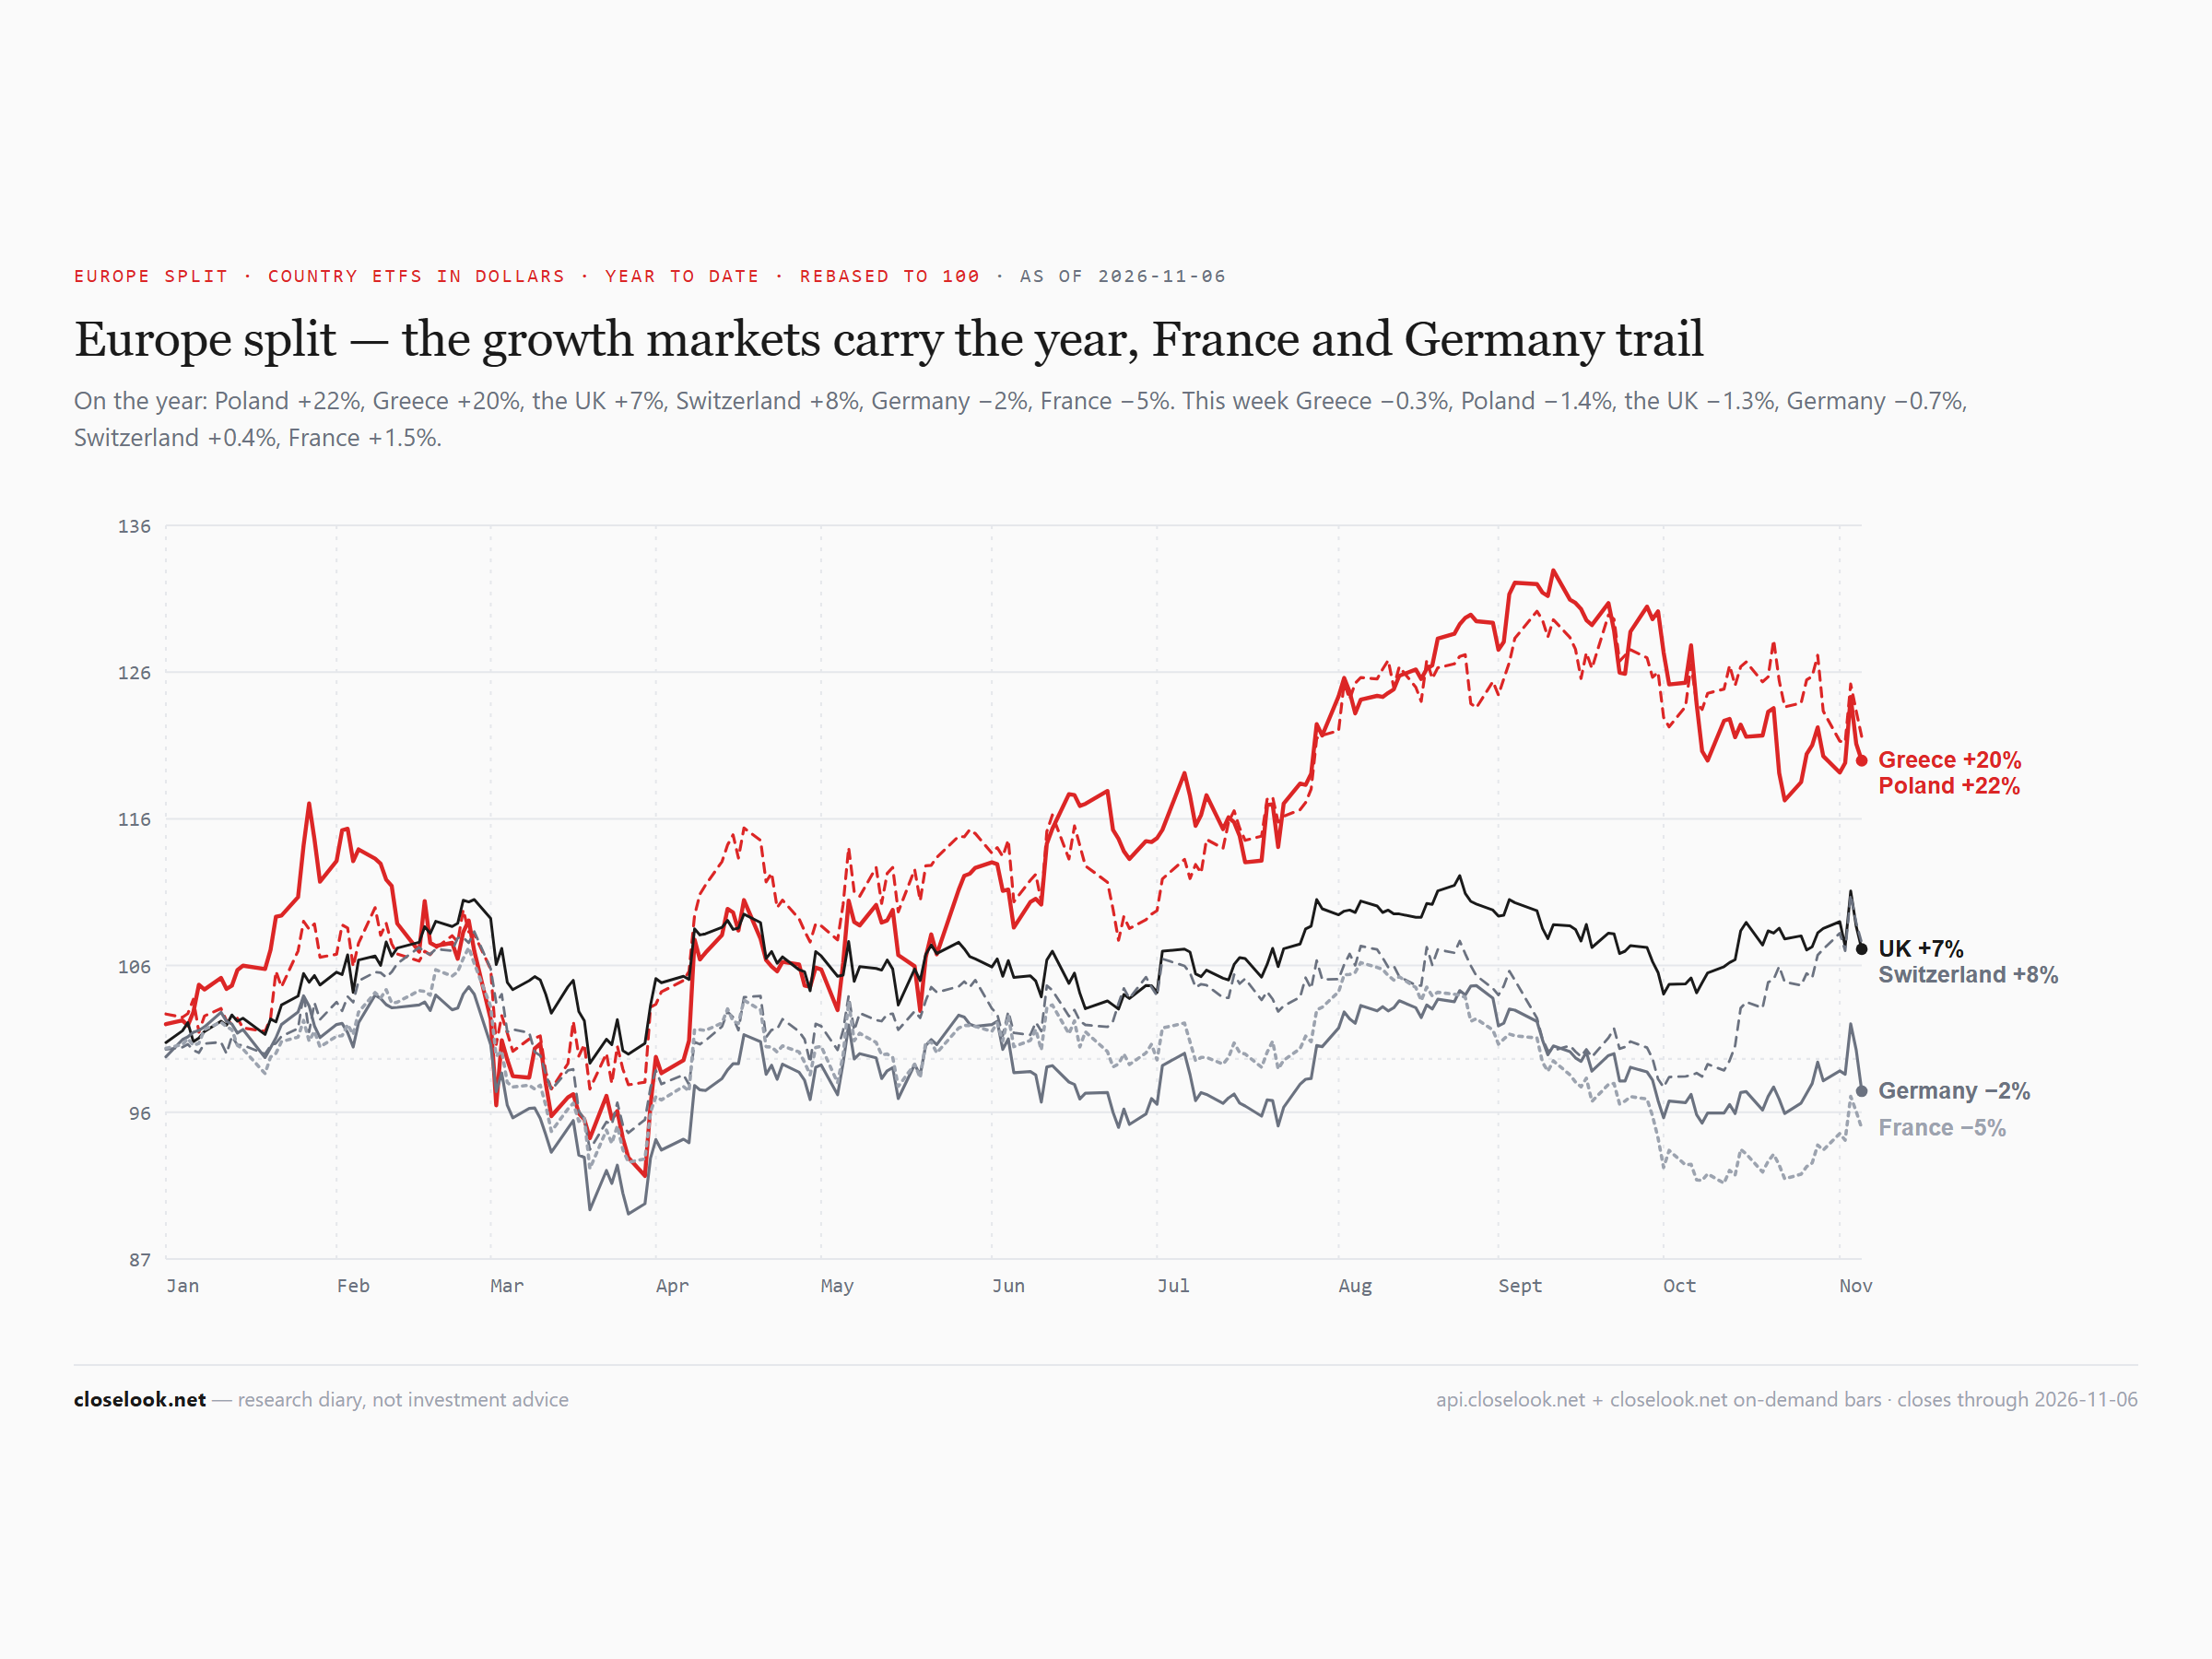
Europe split — the south and France up, the chip and oil markets down. Spain +2.7%, France +1.5%, Switzerland +0.4%, Austria +0.1%, against Germany −0.7%, Britain −1.3%, Poland −1.4%, the Netherlands −1.5% and Norway −6.4%. The Netherlands is Europe's chip-equipment market; Norway is its oil market. The two lost for the same reasons the corridor and the oil funds did.
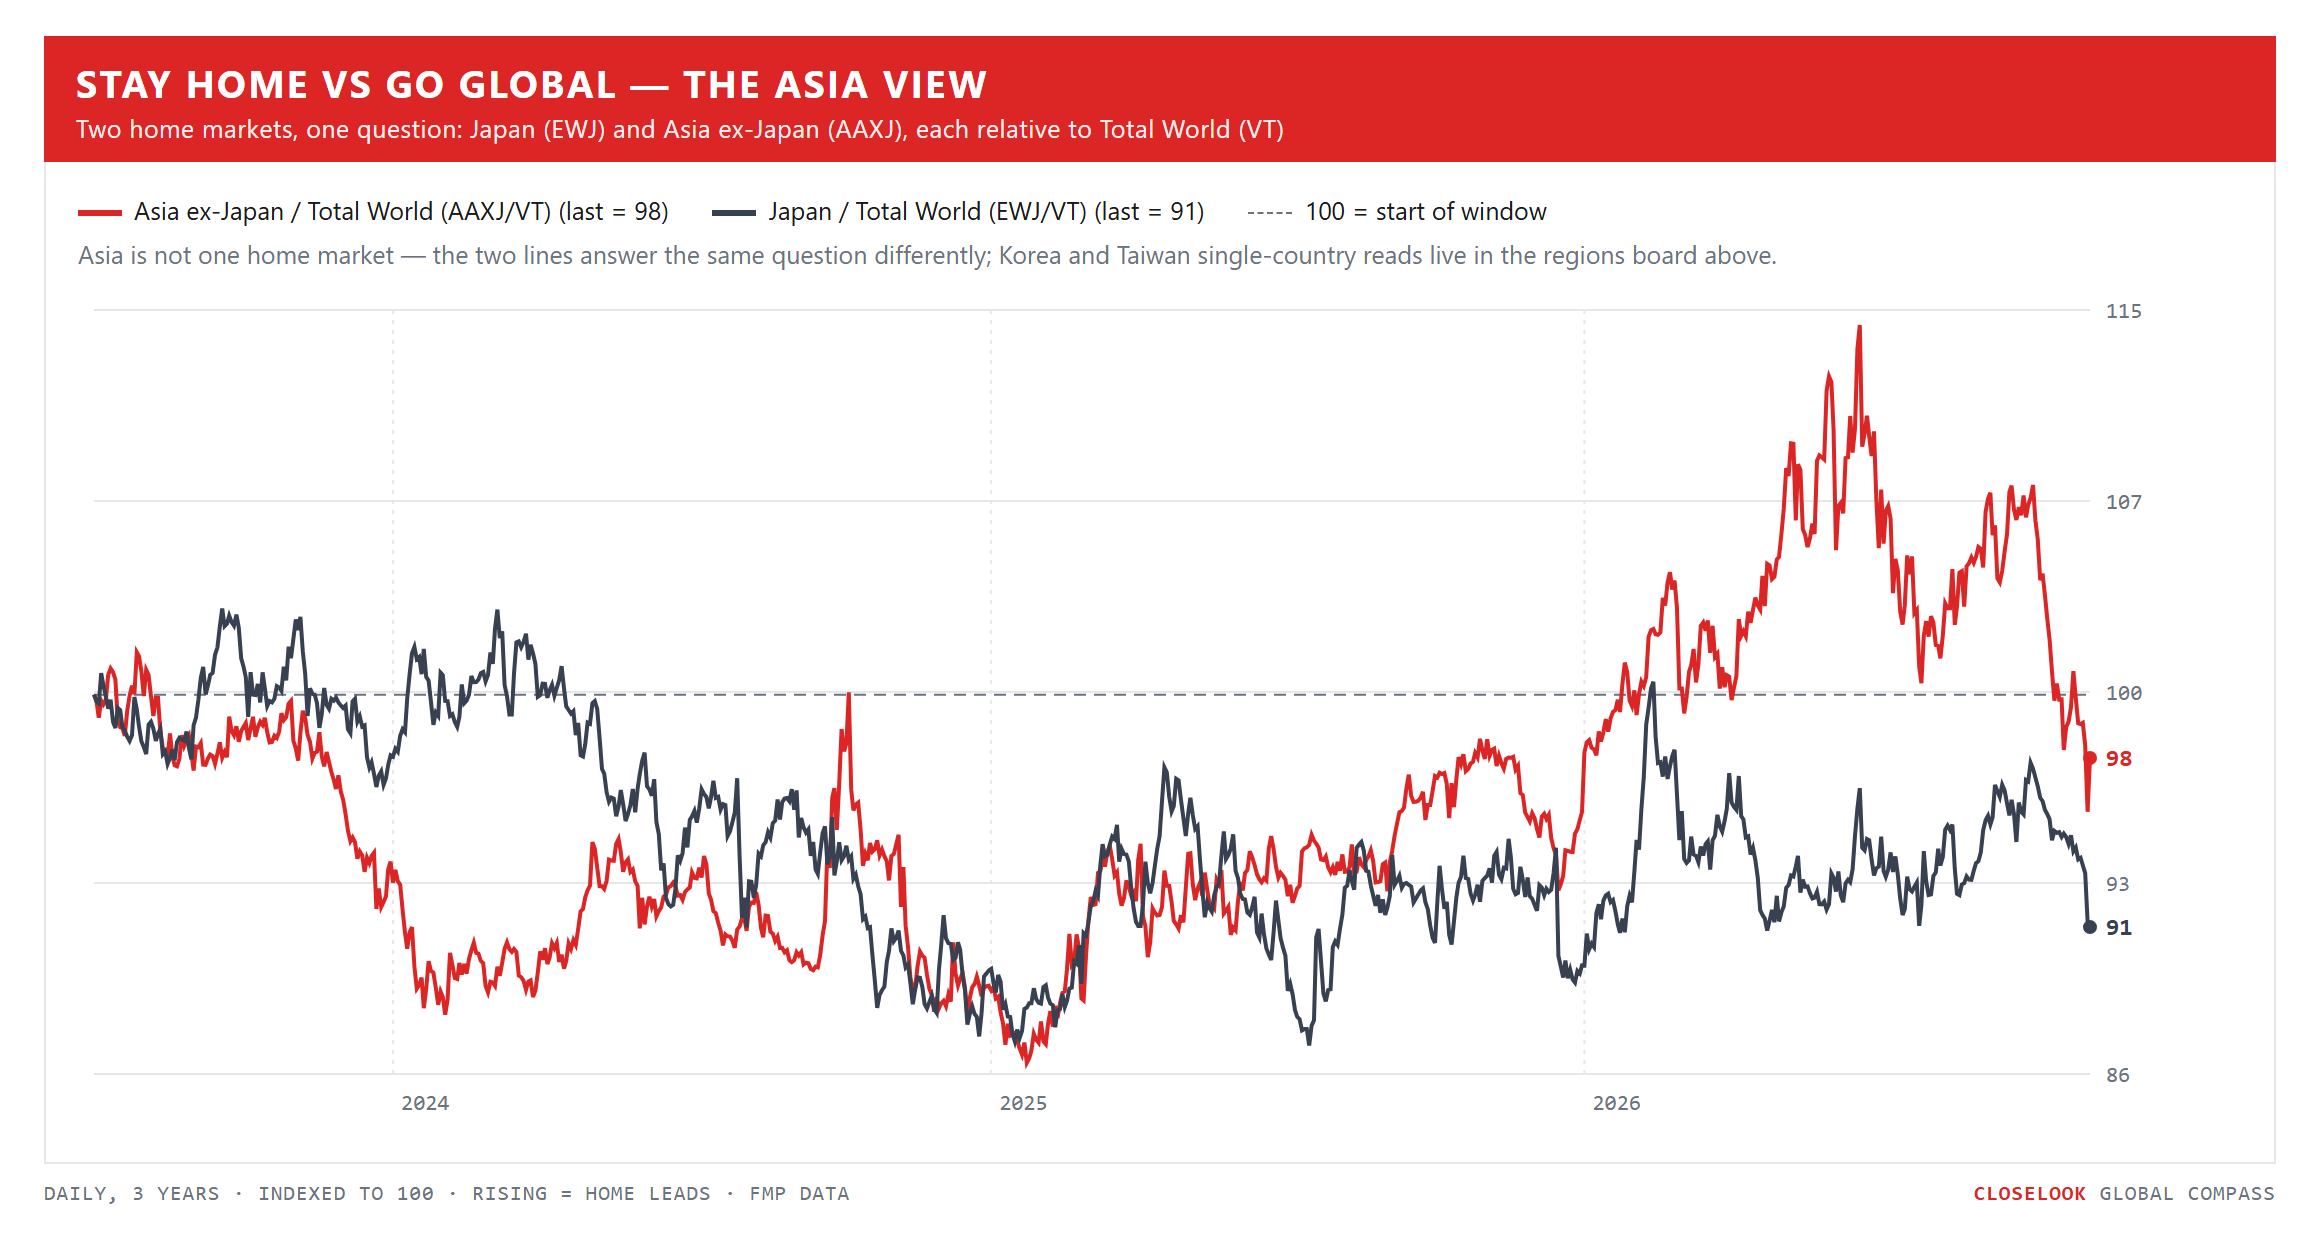
Stay home vs go global — the Asia view: the chip markets against the rest. Korea: EWY −10.39%, the Kospi −11.7%. Taiwan: EWT −11.74%, the Taiex −12.2%. Japan: the dollar fund −5.00%, the Nikkei −9.3%. China and Hong Kong +1.5 to +5.7%. India: the dollar fund +6.64%. Asia ex-Japan as a whole fell 3.63%. Last week the markets that own the AI hardware rose into Wednesday and fell on Friday. This week they fell on Thursday and Friday, and the markets that own almost none rose all week.
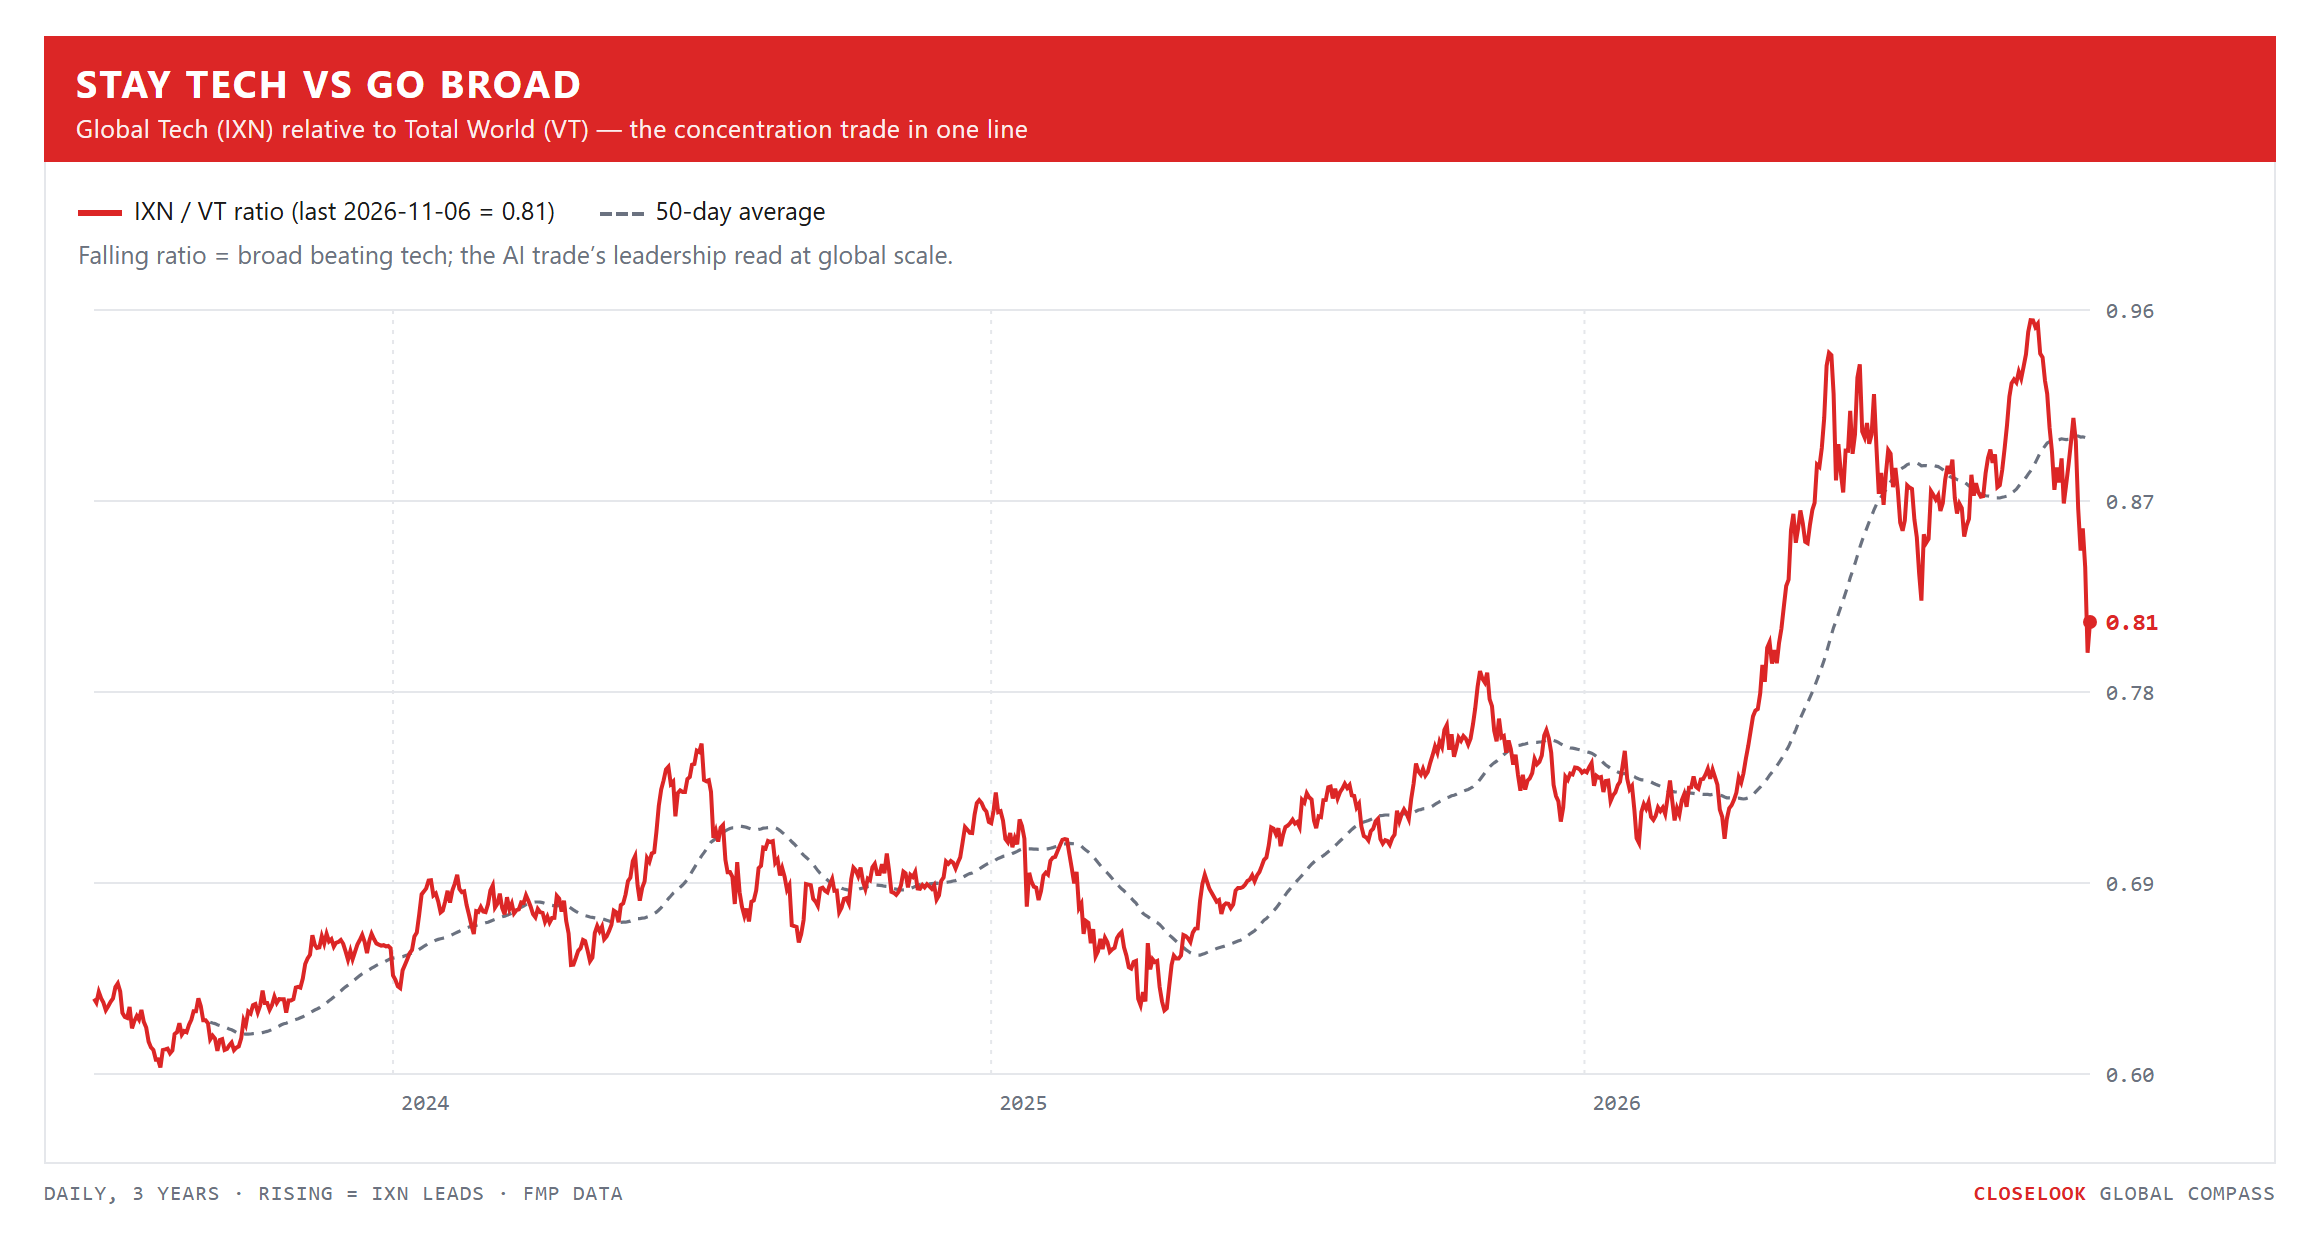
Stay tech vs go broad — broad won, everywhere, by more. The equal-weight S&P −1.04% against the S&P's −2.70% and the Nasdaq 100's −4.98%; the world −2.32% against global tech's −8.25%. Small caps fell 2.03%. On the year tech still leads, but by far less: global tech +17.7% against the world's +7.6% — a week ago it was +28.3% against +10.1%.
Momentum vs defensive — min-vol at a record, then lower. International min-vol closed at a record 97.61 on Wednesday and ended the week 1.16% lower at 95.13; global min-vol made its own record, 131.37, the same day and ended at 128.23. International momentum fell 4.42% to 48.71. On the year min-vol leads, +10.3% against +1.5%.
The Closelook letters — where this one sits. The house thesis, compressed: the stock market is a growing system at the aggregate level in which most constituents slowly fade while a small group massively outperforms — and that group changes; it never stays static. Own the aggregate, know the current winner group, watch for the rotation. For most of 2026 the winner group sat in the chip corridor — Taiwan, Korea, the memory makers, the equipment makers. This week the corridor fell 10 to 12 percent and the money went to places that own almost none of it: India, China, Mexico, Spain. One week does not make a rotation. It is the first week this year that looked like one. This letter reads the map; Sunday's US letter reads the tape and the AI indices' patterns; Sunday evening's Hypergrowth letter reads the names.
2 · The State
The mechanism, named: the builders were sold for reasons that had nothing to do with their results. Put the week in order. Monday: Brent fell 6.5% to $106.01 after the US and Iran signalled openness to talks; the S&P closed 0.5% lower while the average stock rose. Tuesday: Korea and Taiwan sold their chip makers again, 3.6% each, with Japan closed; Americans voted in the midterms; AMD reported after the close. Wednesday: the Kospi swung 7% in one session on AMD and the election results and closed 0.6% higher. Democrats swept Congress. The Dow rose 2.3% and Apple rose to a record, while the market sold what the vote may slow — data-centre power stocks fell up to 15%. Thursday: Korea fell 5.3% with a sell curb and Advantest 14.7% after Qualcomm's report; in New York the pause call, the Texas moratorium and the Microsoft spending gap took the chip index down 12.2% and the S&P 4.4%. Friday: Korea halted, Japan entered a bear market, Taiwan fell 9% intraday — and New York bounced on the jobs report.
The pattern under the dates. Last week the selling came one region at a time, each with its own reason. This week it came for one group, the companies that build AI, from three directions at once: politics (a moratorium on data centres in the state that hosts many of them), an argument (a call to pause the most advanced AI), and money (a spending gap at one of the largest buyers). None of the three is an earnings miss. AMD fell 13.5% on Thursday two days after strong results. What did not sell all week: India, China, Mexico, Spain, gold, silver and the bonds.
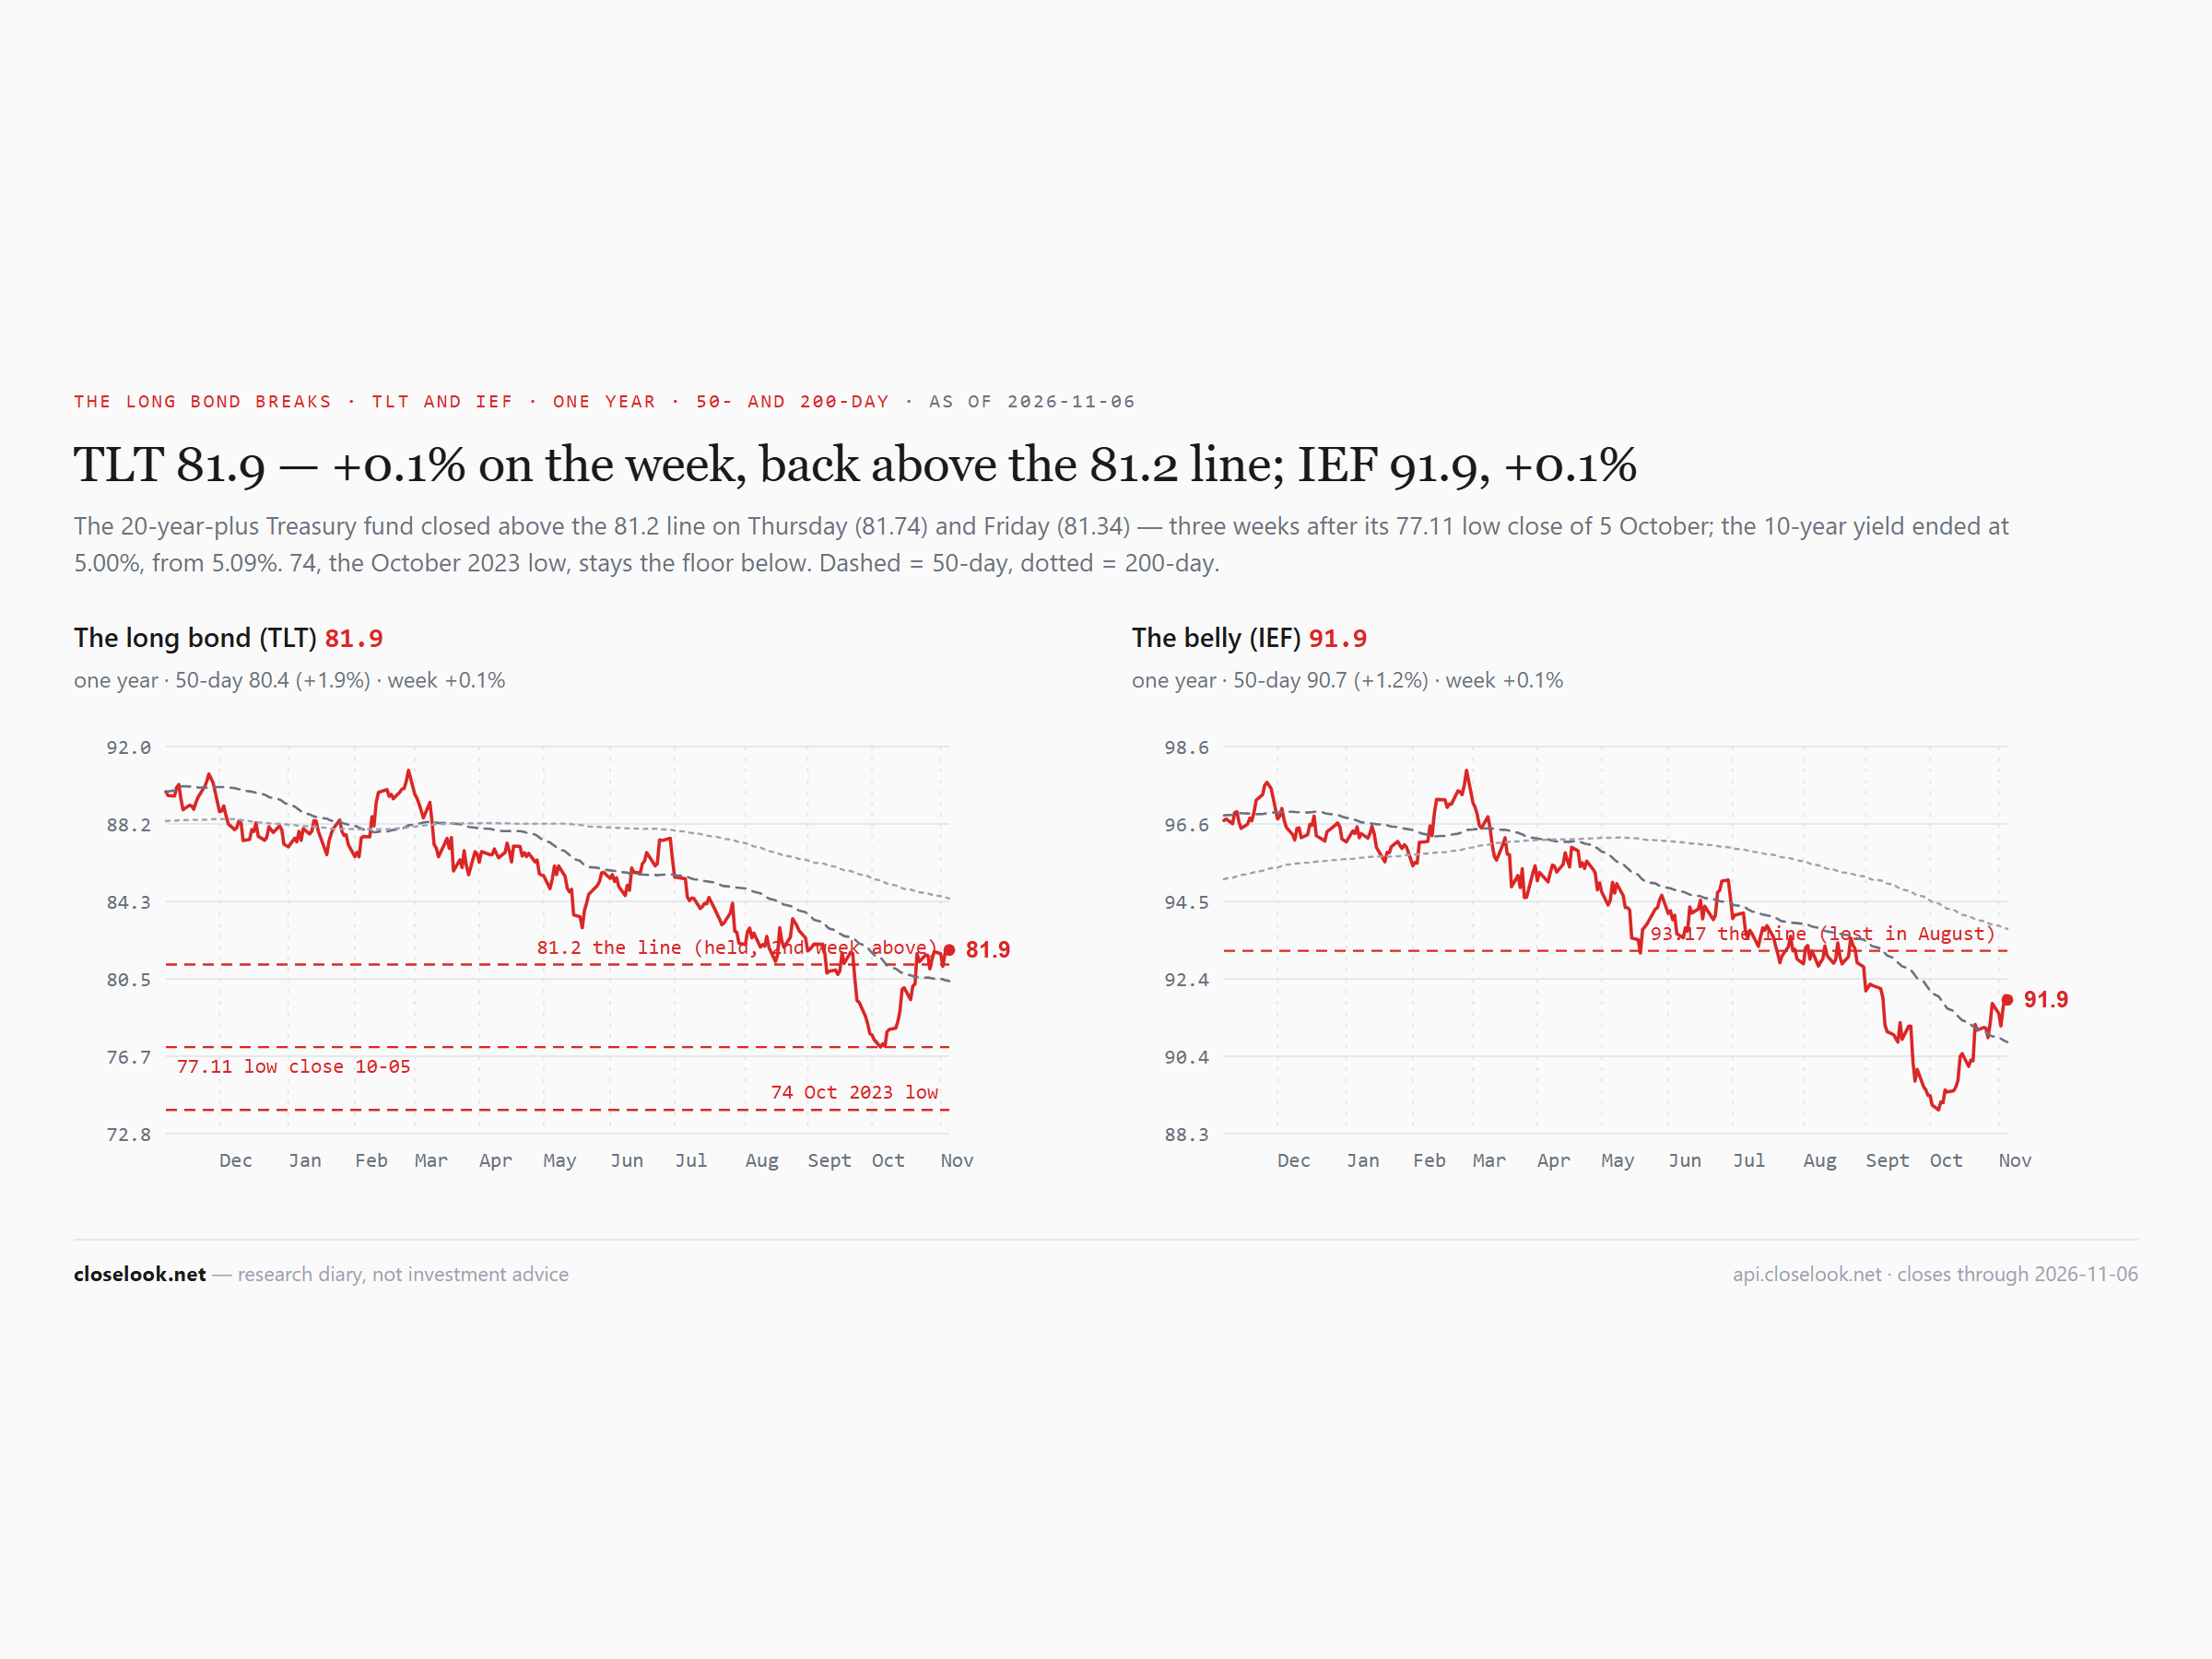
The rate peak, held a second week. The US ten-year closed the week at 4.87% on the house sovereign board, down 7 basis points on the week and 44 basis points under the 5.31% close of 5 October. Last week this letter wrote that a close back above 5.31% would say the peak was not one. It is further from it. The long bond rose 0.10% to 81.92, a third week above the 81.2 line; IEF closed at 91.86, still under 93.17.
The odd part, again: a strong jobs report and lower yields. October's payrolls came in at 165,000 against about 60,000 expected, with unemployment at 4.1%. The Fed held its range at 3.75–4.00% on 28 October and meets next on 9 December, with new projections; on 29 October, before this report, the futures put a December hike near 80%. A strong report and a lower ten-year in the same week is the bond market saying it fears the AI sell-off and the oil price more than it fears the Fed — or that it already has the hike in the price.
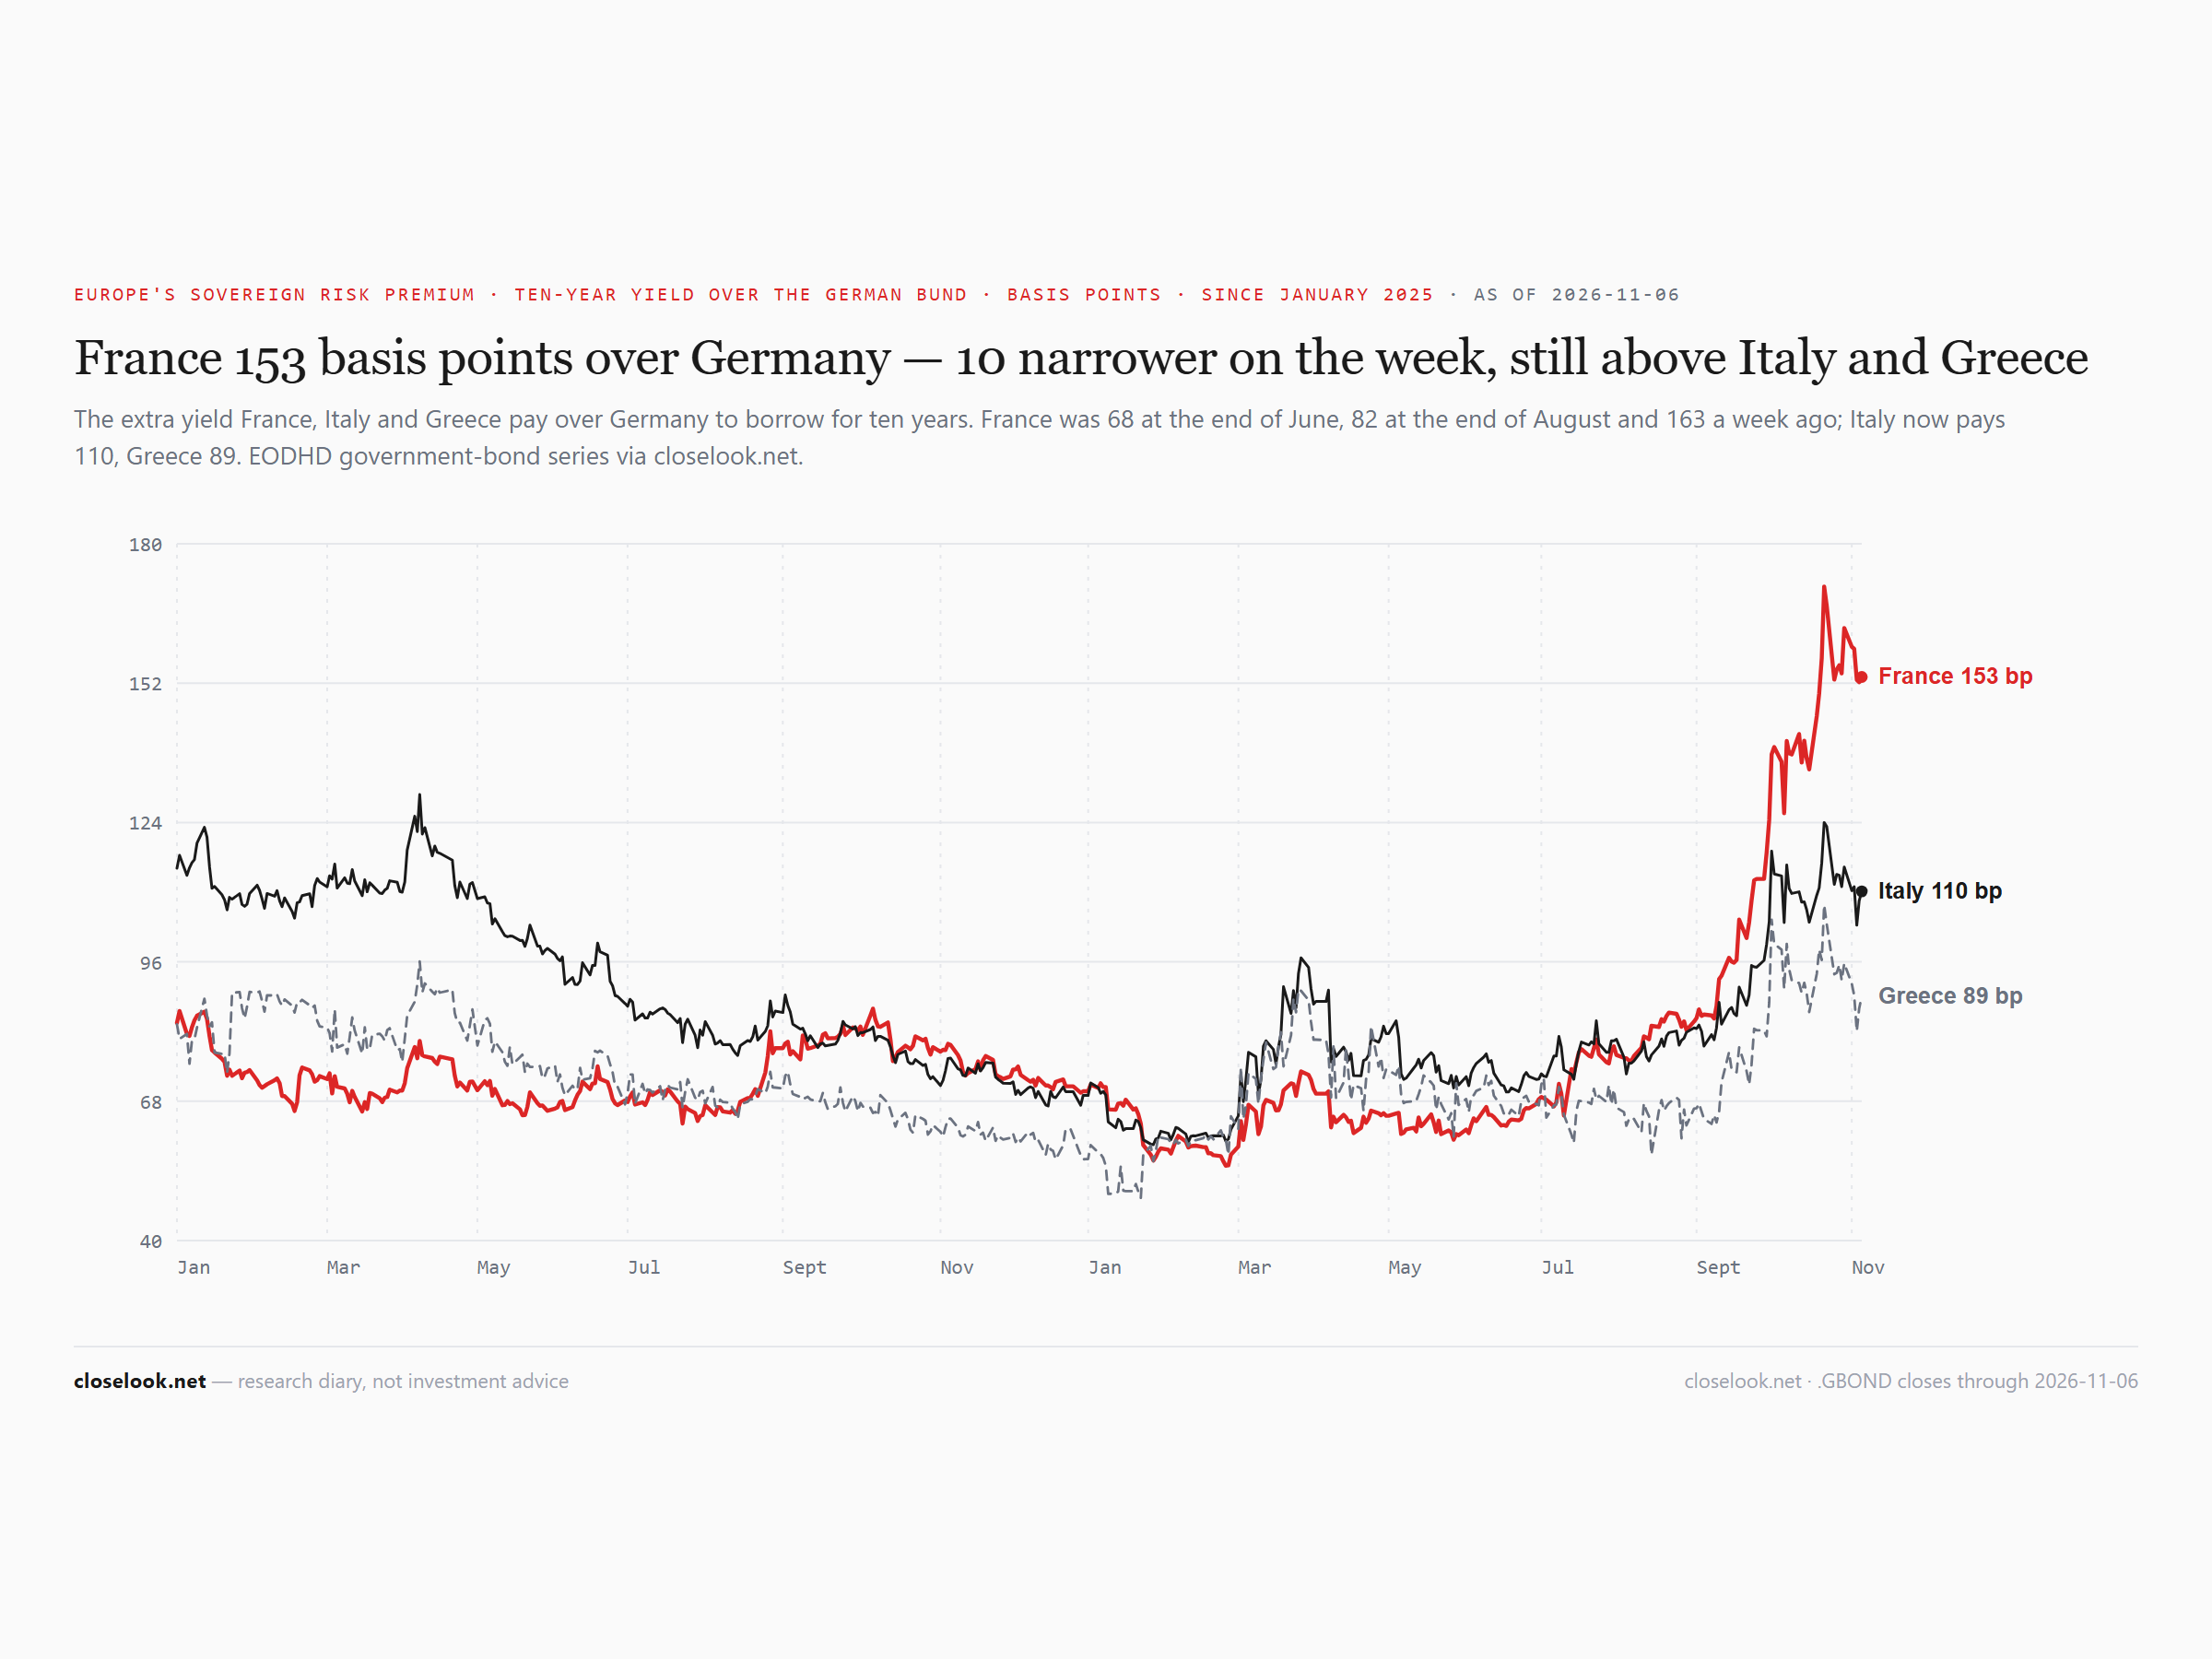
France now yields less than America. The French ten-year closed Friday at 4.77%, under the US ten-year's 4.87% — a week ago France paid 4.97% against America's 4.93%. France's premium over Germany narrowed to about 150 basis points, more than ten narrower than a week ago; Italy pays about 107. The German ten-year closed at 3.27%.
The rate map — one sentence each. America: 4.87% on the ten-year, down 7 basis points on the week and 43 over 21 sessions. Britain: 5.16%, 5.61% on the thirty-year — still the highest long yield on the board. Japan: 2.64%, from 2.77%. France's 20-basis-point fall was the largest on the board. Germany: 3.27%. France: 4.77%. Italy: 4.34%. Canada: 3.66%. The equal-weight ten-year on the board stands at 4.10%, from 4.23%; the house sovereign pressure index fell to −1.91 from −1.66 — less pressure again.
The consequence — the map, restated. This letter's positioning: this diary stays away from mainland Europe's core, and from France in particular; Greece and Poland stay the exceptions. This week France's yield fell under America's and its fund rose 1.5% — two good weeks after a bad month. The map stays as it is until the spread holds under the 135 line named below. This is a diary's positioning, not advice.
Oil — the week's largest fall. The oil fund fell 12.10% to 148.41, from a close of 168.83 a week ago and 12.5% under its October 23 high close of 169.53; the Brent fund fell 12.8% to 62.22, from its record. US energy fell 12.0% to 61.62 and global energy 11.15% to 57.03 — both from record closes a week earlier. The trigger was Monday's signal from Washington and Tehran. For every economy that imports oil — Europe, Japan, Korea, India — a 12% fall is a tax cut, and India's week reads like one.
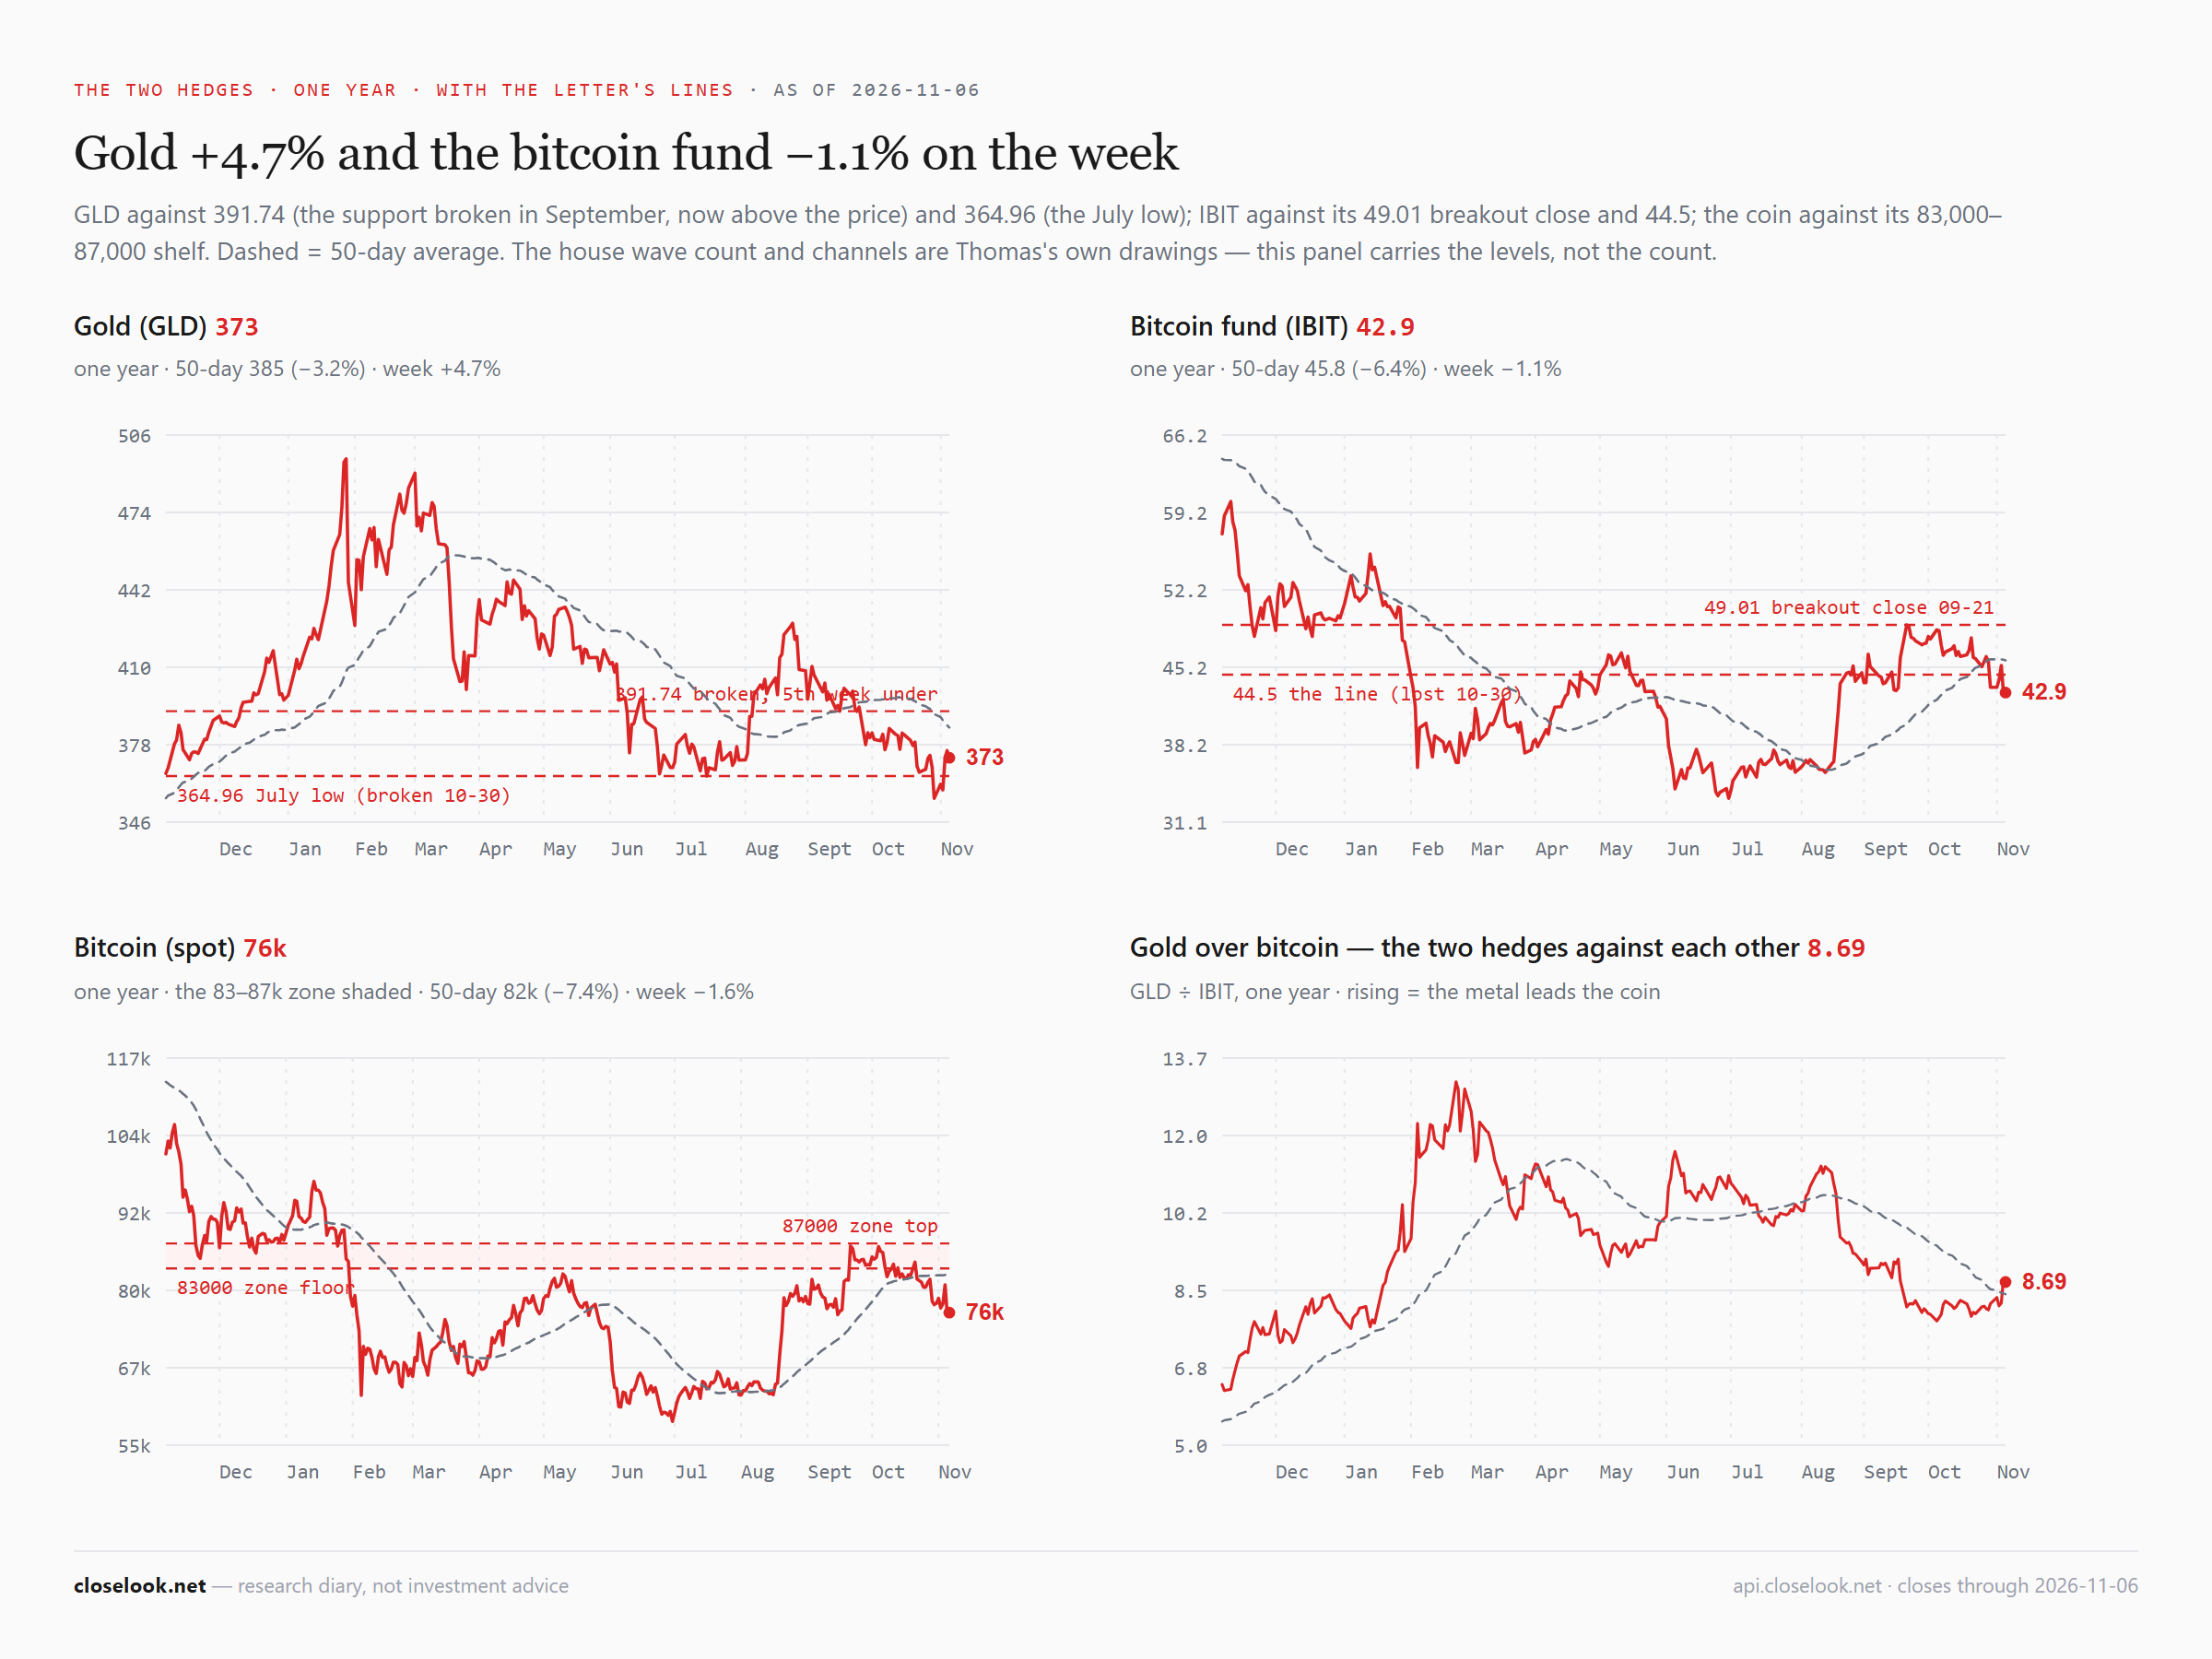
The hard assets — gold back above the line. Gold rose 4.71% to 372.52 — back above its July low close of 364.96, 24.9% under its January 29 record of 495.90. Last week this letter wrote that a weekly close back above 364.96 would say the fall was a flush. That is the close. Silver rose 5.09% to 46.87, still 55.6% under its January high. Copper miners fell 0.99%. Bitcoin closed Friday at 75,944, −1.6% on the week; the fund fell 1.11% to 42.88, still under the 44.5 line. The metals rose while oil fell — the opposite of last week, when the metals fell while oil rose.
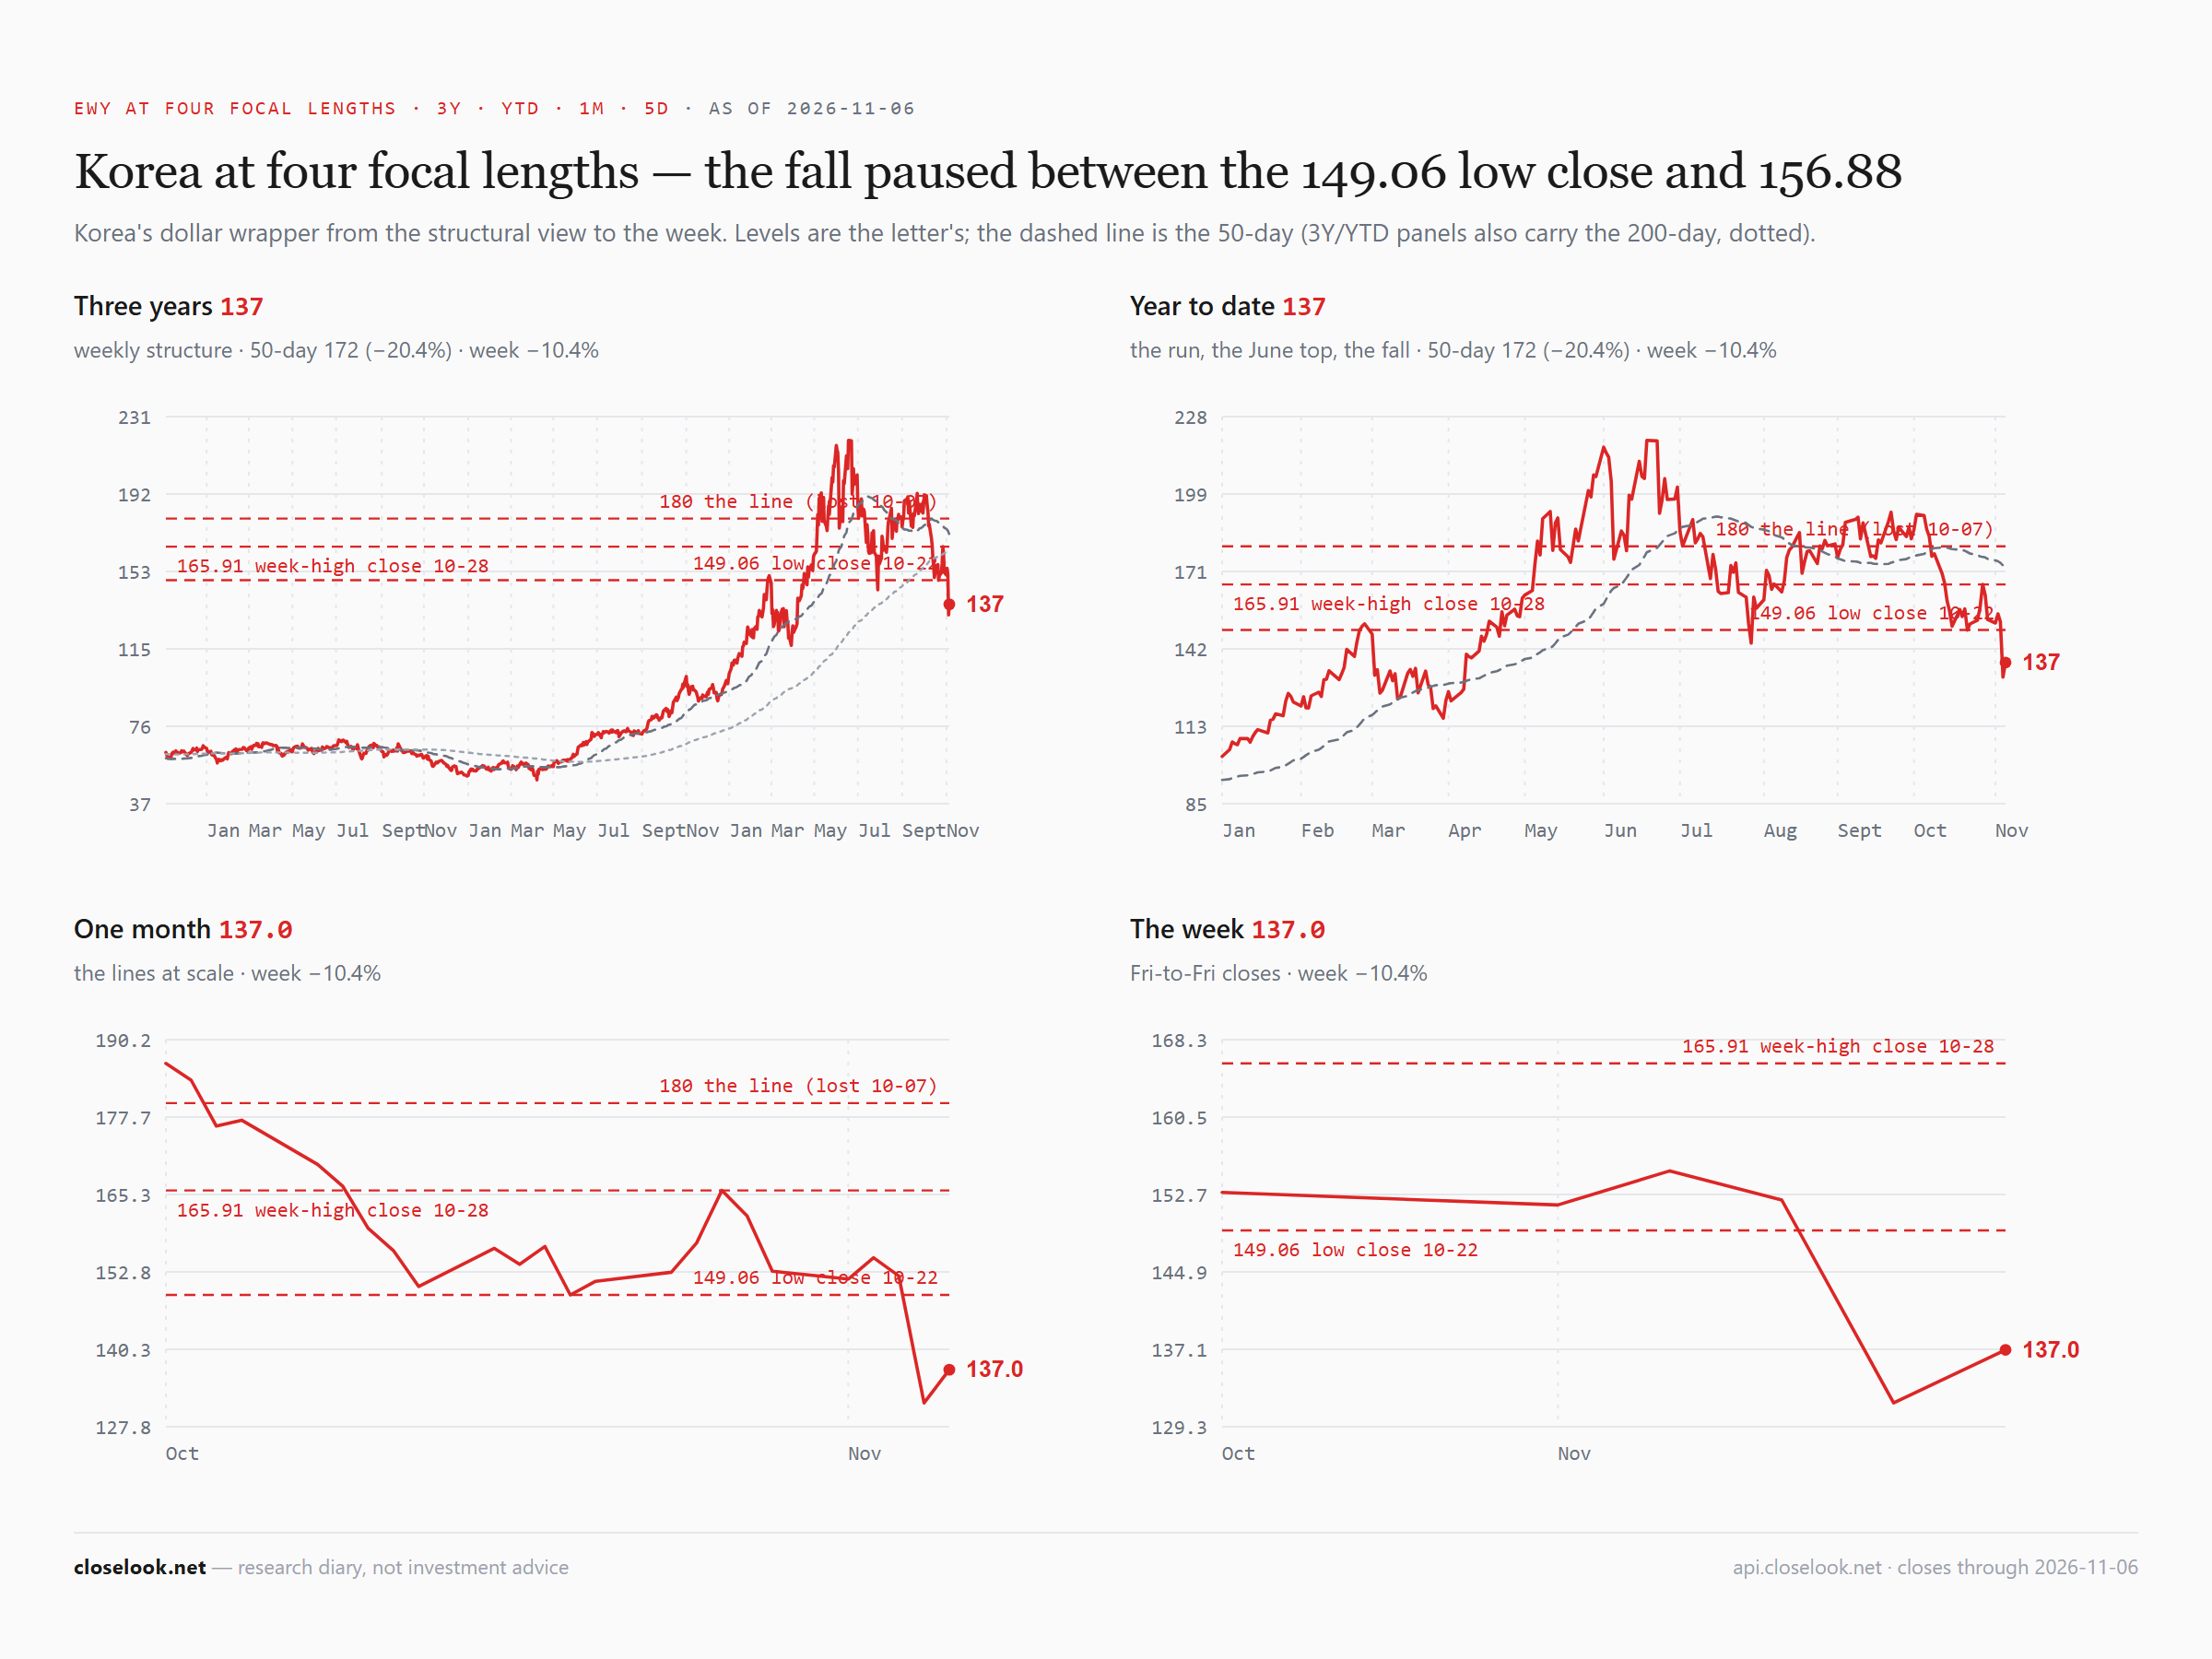
Seoul: the week in two sessions. The fund walked 151.62 → 155.06 → 152.12 → 131.65 → 137.01. Thursday's close was the lowest of the week; Friday's took back 4.1% of it. EWY is 37.5% under its June high and +40.9% on the year. In won the Kospi lost 11.7% on the week to 5,060 — a dollar investor lost a little less, 10.4%, because the won firmed.
Taiwan: under 100. EWT closed 100.66, 98.27, 97.08, 85.88, 89.24. Last week this letter named a weekly close under 100 as the sign of a second leg. This is that close, and 11 points under it. The fund is 24.4% under its October 5 record and still +40.5% on the year.
Europe, the voting machine and the weighing machine. Euro-AI fell 4.15% to 1,201.18, two of seven sleeves green: medtech +2.76% and enterprise AI and data +1.14%. The red: chip architecture −15.30%, semi equipment −9.05%, defence −8.88%, industrial AI −3.09%, power, grid and cooling −2.86%. Last week Europe's machines and power came back. This week its chip names fell with Asia's.
The macro print. Three numbers: a Kospi halted at −8.8%, 165,000 new US jobs, and a 4.87% ten-year. The first says the corridor's selling reached its home market. The second says the US economy is not the problem. The third says the bond market is looking past the second.
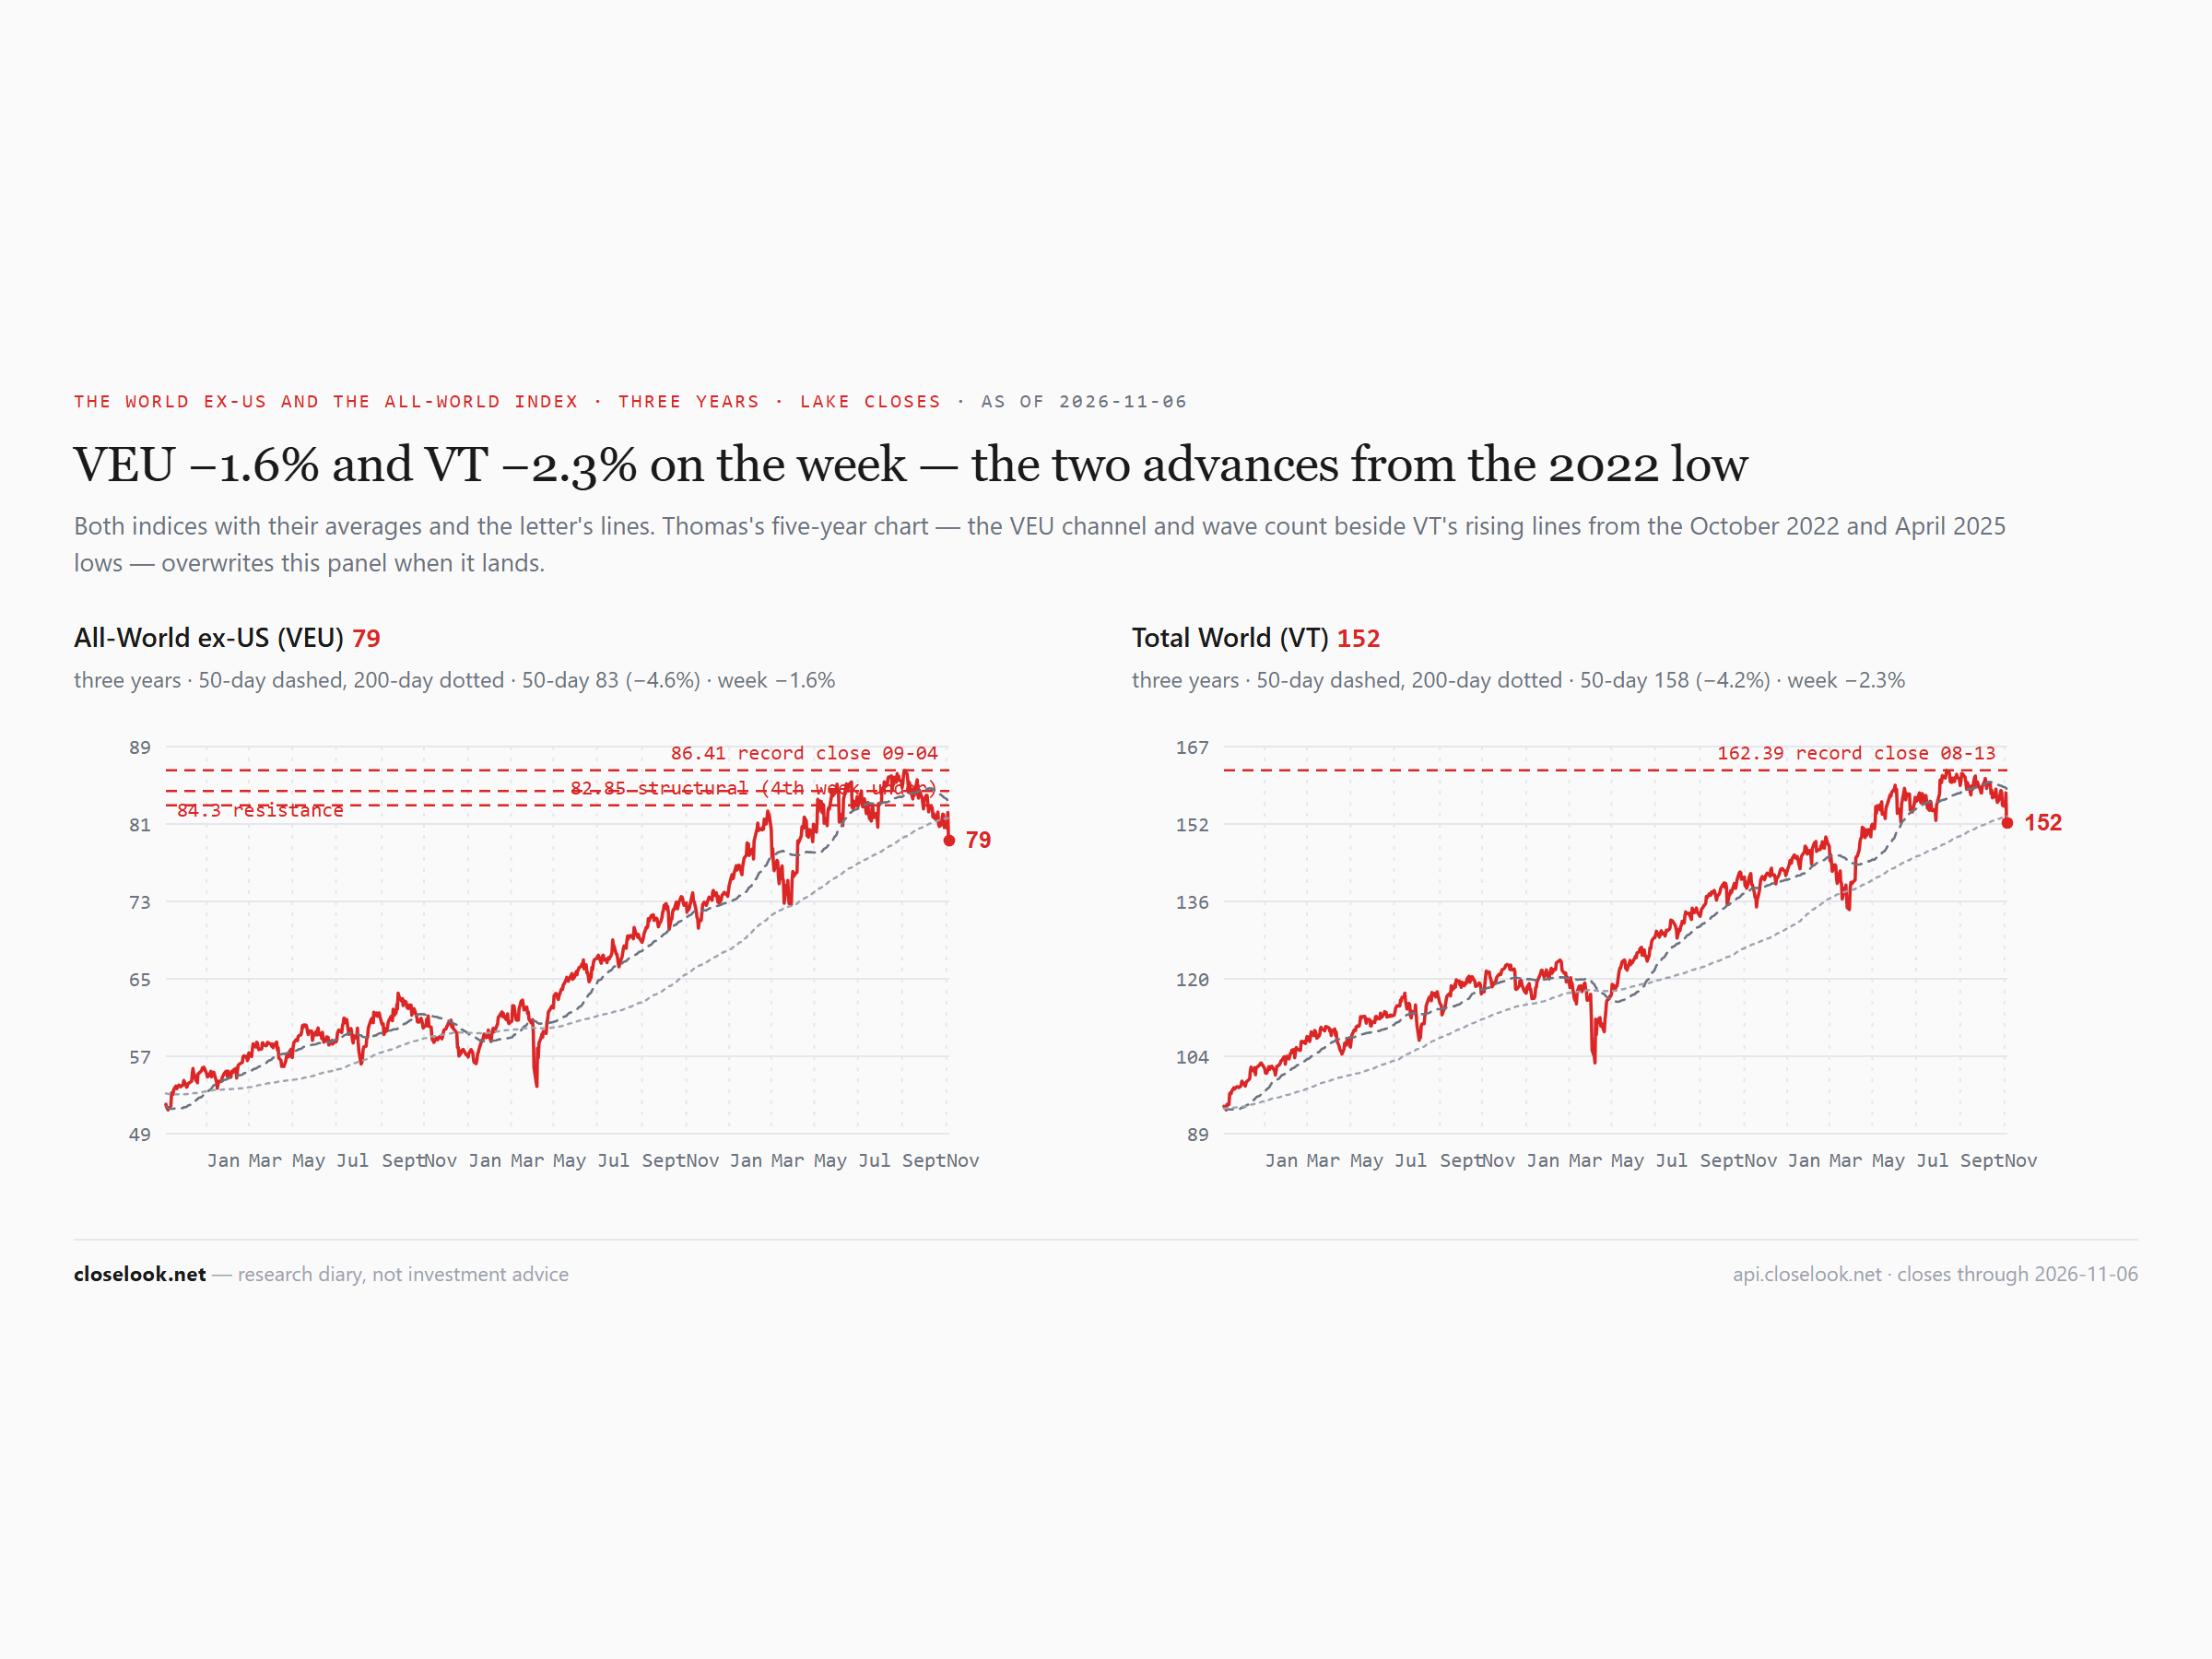
The structural read — the world ex-US lost its floor, the all-world lost its July low. VEU's Friday close of 79.25 and its intraday low of 78.84 sit under the horizontal support near 80.3 — the summer lows: 79.83 on 4 May and 80.38 on 29 July. The editor's preferred count reads the world ex-US as forming wave 4, a complex consolidation. Last week this letter wrote that a weekly close under about 80 would say the fourth wave is deeper than drawn. That is this close. VT closed at 151.73, under its July low close of 152.22. On the editor's alternative count the all-world advance since April 2025 is a fifth wave; a weekly close well under the 2022 channel line would be the first sign that it has ended. This week's close is further under it than last week's.
3 · The Outlook
The three-index read — the builders and the runners fell, the sellers held. We read the three together because they are three stages of one spend: capex (Rubin Build-Out, what gets built), opex (Agentic Ecosystem, what it costs to run), applications (Agentic Winners, what gets sold on top).
Capex −13.23% on the week to 1,485.88, none of thirty-six sub-indices green, +44.6% on the year. Opex −10.48% to 1,379.10, none of fourteen green, +39.7%. Applications +0.28% to 915.94, five of nine green, −6.4%. Last week the builders held and the other two fell. This week the builders and the runners fell together, by 10 to 13 points, and the applications did not.
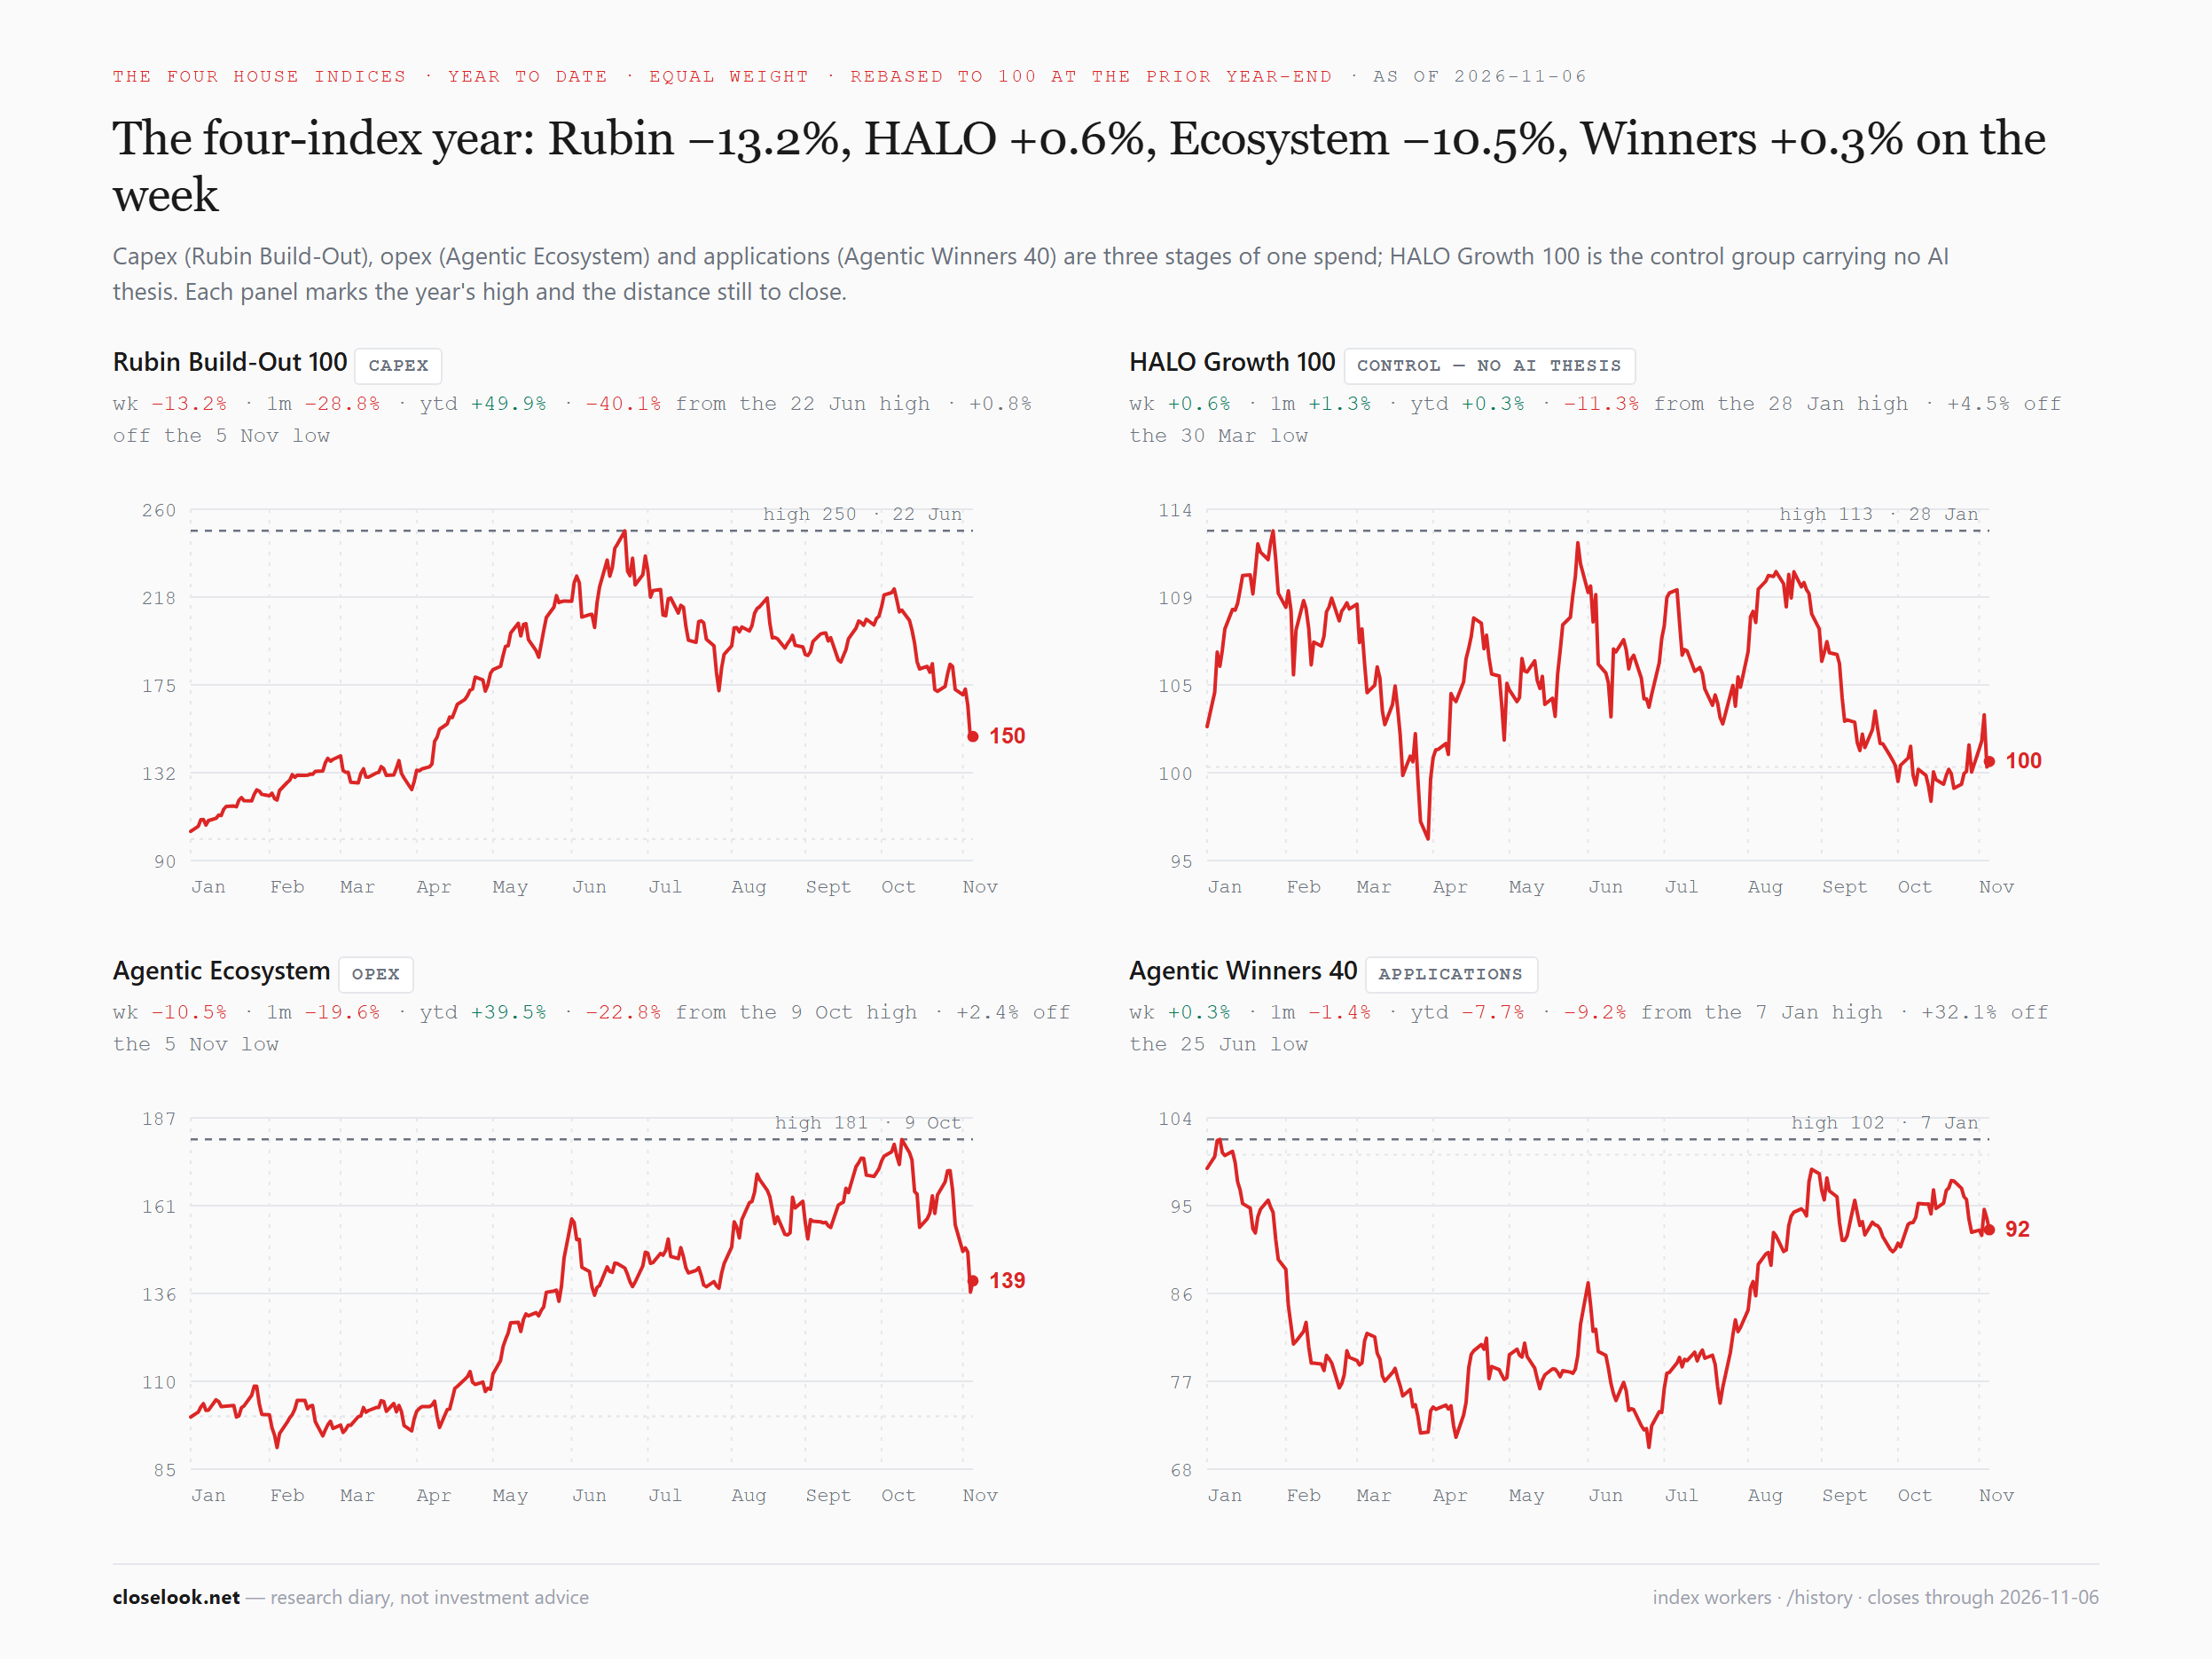
The order of the fall. Through 2026 the three rose in sequence: the builders first, the runners next, the applications last. The falls are arriving in the same order. Capex is now 40.1% under its June 22 high and opex 22.8% under its October 9 record; applications are 9.2% under a January high and 32.1% above their June low. The applications have not fallen yet. The data does not say they will; it says the first two did, in the order they rose.
The control group rose. HALO — our growth index carrying no AI thesis — rose 0.59%, −1.9% on the year, thirteen of twenty-three sleeves green. Inside it, energy transition and clean power +24.12%, the destination economy +8.00%, surgical and medical devices +4.65%, payments +3.70% — while autonomous defence and drones fell 11.10%, the hypergrowth leg 5.95% and space and satellites 5.68%.
Read the windows together. On the year capex still leads: +44.6% against +39.7% against −6.4%. On the month the order is reversed: applications −1.4%, opex −19.6%, capex −28.8% — and HALO +1.3%. The index with the worst year has the best month for a third week.
Inside capex: storage and memory led the fall. The least bad: gases and chemicals −2.85%, manufacturing support −5.73%, photomasks −6.12%, chip design software −6.18%, lithography −7.14%. The worst: storage −30.74%, HBM memory −20.14%, wafer processing −20.01%, advanced materials −19.60%, the Japan constituents −19.54%. Storage and memory are still the two best sleeves of the year, +130.2% and +91.4%. The sleeves that rose most fell most.
Inside opex: everything fell, the watchers most. The least bad: the Europe constituents −3.33%, runtime and API gateways −4.50%, compute operators −4.75%, the Asia constituents −4.79%. The worst: identity, trust and governance −13.79%, operations and observability −13.18%, data and memory −12.91%, govern and secure −12.72%, agentic security −12.28%.
Inside applications: devices and consumers up. Endpoints +9.62%, consumer +8.00%, the Asia constituents +3.28%; the red was the control plane −5.96%, enterprise −2.94% and the application leaders −2.53%.
Euro-AI, for the ladder's sake. The sovereign-Europe index fell 4.15% to 1,201.18, +20.1% on the year, 13.7% under its June high, two of seven sleeves green. On the ladder, Europe's AI index fell less than America's builders and runners, and more than its applications.
The regime gauge. The Money Temperature board closed the week at 47, from 46 — mixed and transitional, inside neutral and, by its own construction, not a signal. The week ran 46, 45, 46, 44, 47. The instruments: the dollar 65, the S&P 48, bitcoin 48, gold 47, the long bond 46, the Nasdaq 100 43, emerging markets 40, the world ex-US 37. A week ago the Nasdaq read 57 and gold 31; they now sit four points apart. The house cointegration monitor lists the S&P against gold as breaking, the spread 3.5 standard deviations from its mean — the widest gap on the monitor.
4 · What May Lie Ahead
The fourth quarter — the map under strain. This letter's expectation for the rest of 2026: America and Asia's corridor lead, mainland Europe and India trail, the dollar stays firm. Five weeks in: the corridor broke this week, India led it, and America's lead for the year is down to a tenth of a point. The dollar is the one part that held — level with its high close of the year. The expectation is under strain, not withdrawn. One week of India over Taiwan does not reverse a year of the opposite; a second and third would.
The season — the stance stands, tested. This letter expected uncertainty through the reporting season and named the stance: buy dips, do not chase. This week tested it harder than any week since spring: a 12% day in the chip index, a halt in Seoul, a bear market in Tokyo. The stance stands. A dip that comes from politics and a pause call, not from the results, is the kind the stance was written for — and the kind that can run further than expected.
The calendar. The Fed's next decision is on 9 December, with new projections; the last read of the futures, before Friday's jobs report, put a hike near 80%. The Texas question — a governor-elect who wants a data-centre moratorium — has no date yet. Every weekly close below is a Friday close; the next one is 13 November.
Levels and tripwires — VEU first, under the floor. The marks: 86.41 the record close (September 4); 82.85 the structural line — five weekly closes under it now; 82.10 Wednesday's close, the week's high; the summer-low support near 80.3 — 80.38 on 29 July, 79.83 on 4 May — now above the price; 79.25 Friday; 78.84 this week's intraday low; 72.75 the spring low (March 30), 8.2% below. A weekly close back above 80.3 would say this week was a test of the support from below; a second week under it would make the summer lows a ceiling.
VT — under the July low. 162.39 the high close (August 13); 156.82 the bottom of the August–October range; 152.22 the July low, now above the price; 151.73 Friday; 134.19 the spring low. A close back above 152.22 puts the July low back under VT; the 2022 channel line is the one that decides the fifth-wave question.
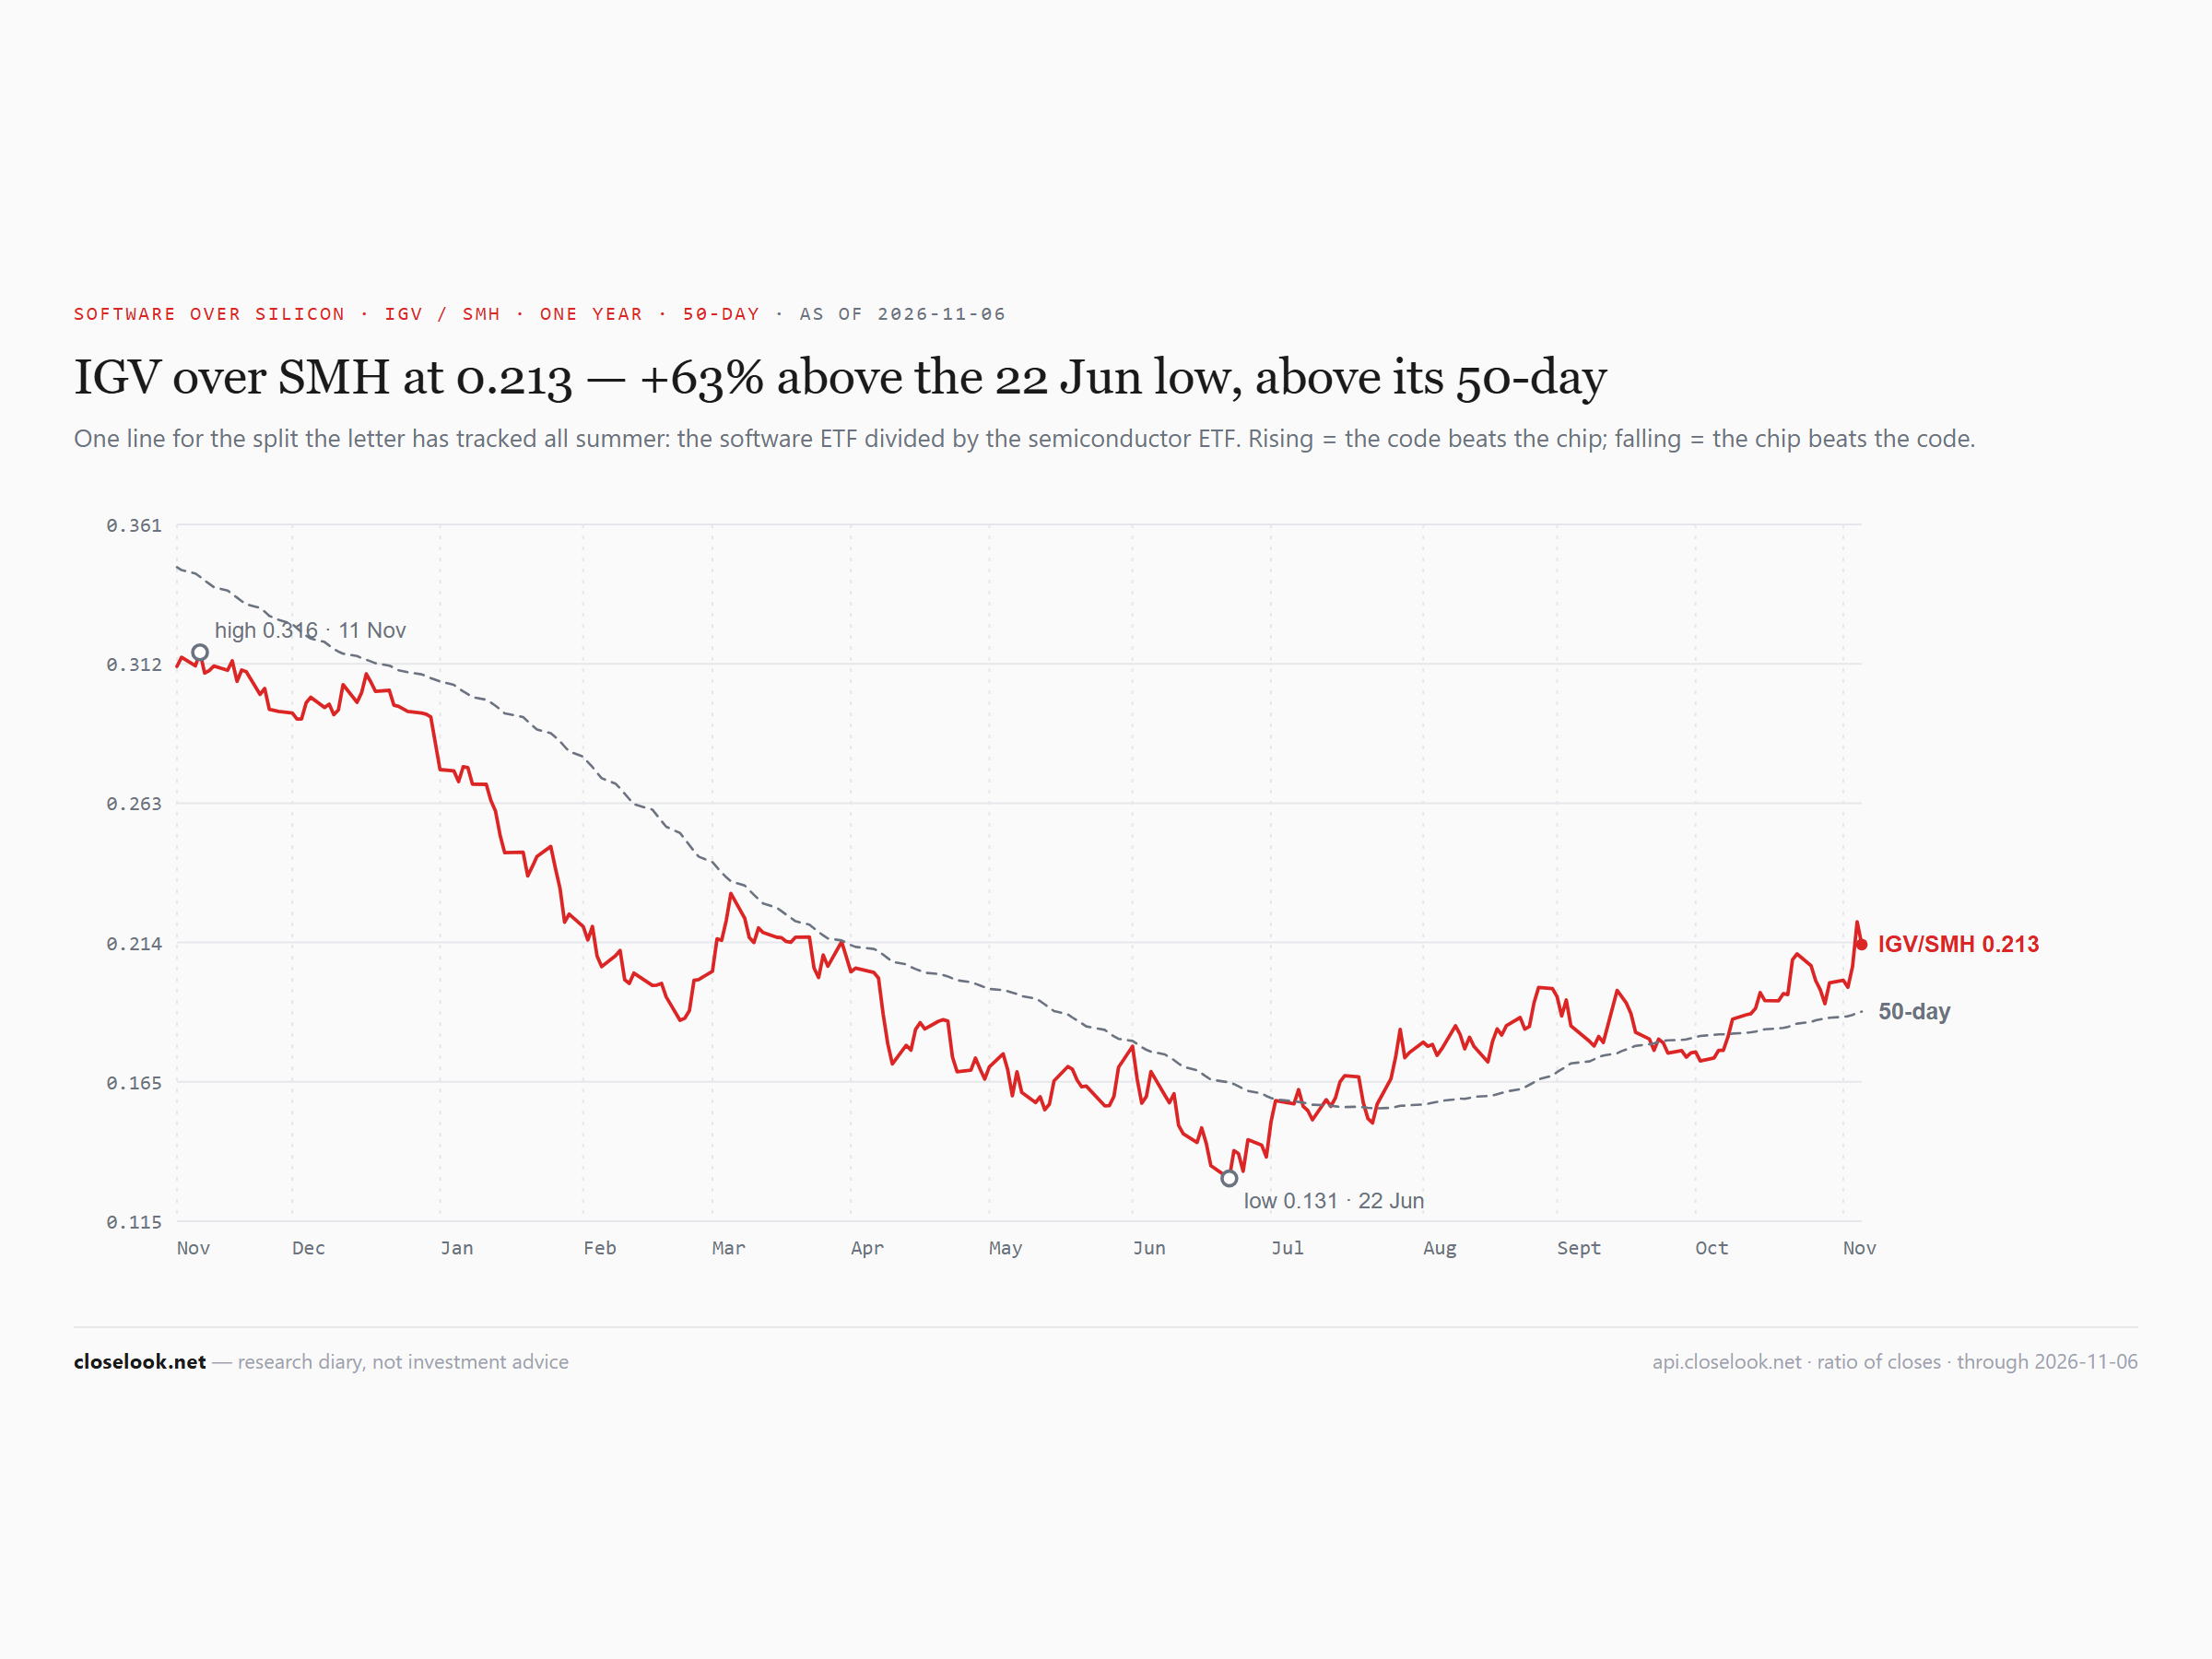
The leadership pair — software and Taiwan, both under 100. IGV 98.88 — back under 100, with an intraday low of 98.17; 112.67 the high of the year (October 9). Two weeks ago this letter wrote that a close under 100 would cancel software's claim to the lead. That claim is cancelled. Taiwan's EWT 89.24 — under 100 for the first weekly close since the steep line broke; 118.00 the record above. Neither the software nor the silicon leads now.
The long bond — the line held a third week. TLT 81.92, a third week above 81.2; 77.11 the October low close; 74, the October 2023 low, below. IEF 91.86, still under 93.17.
The ten-year — further from the peak. 5.31% on 5 October is the high close; 4.87% is Friday's — a second weekly close under 5.0%. A close back above 5.0% after a strong jobs report would say the bond market changed its mind about the Fed; a close back above 5.31% would say the peak was not one.
France — under America. About 150 basis points over the Bund, more than ten narrower on the week; a ten-year yield of 4.77% against America's 4.87%. The next line above is the round 200; a narrowing under 135 would say October was a spike, not a trend.
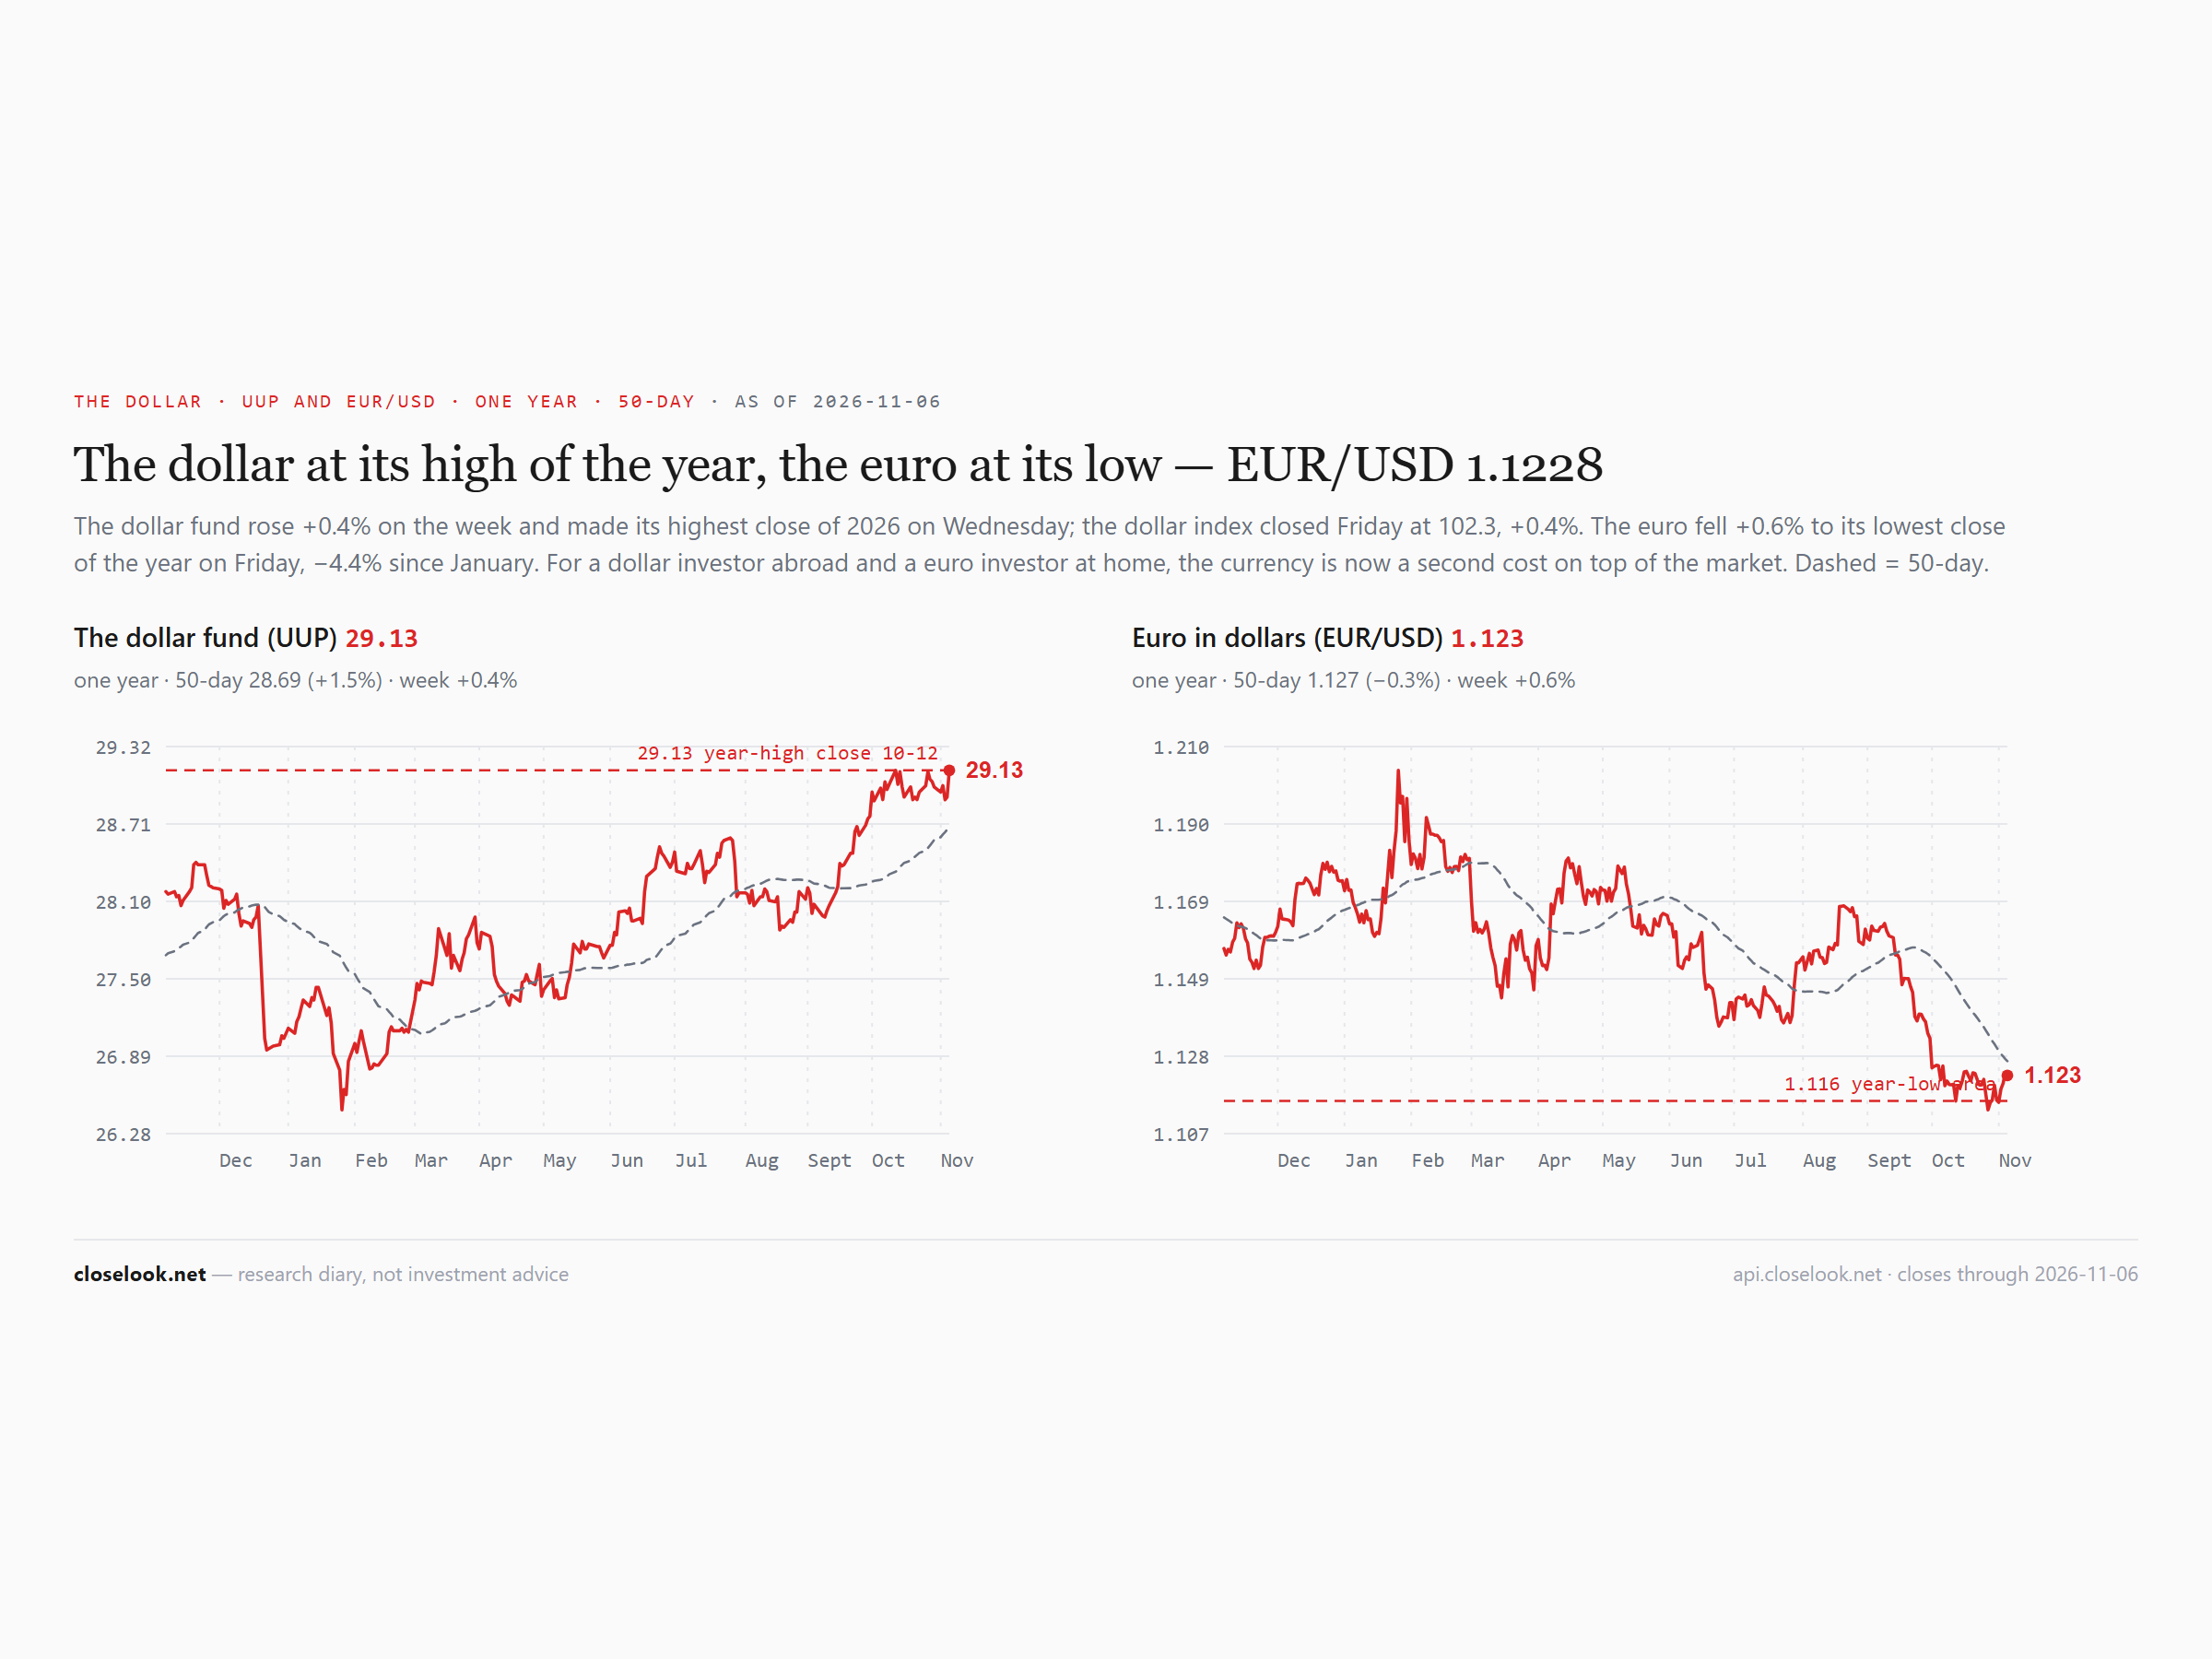
The dollar and the yen. The dollar fund's 29.13 matches its high close of the year (12 October). EUR/USD 1.1147 — under the 1.1160 low this letter named last week. USDJPY 158.43, from 157.55: 160 the door, 155 the level that brings the intervention talk back. A dollar at its high and a yen near 160 are a cost for every Asian market that borrows or buys in dollars.
EWY 137.01 — Thursday took the week. 155.06 the week's high close, 131.65 Thursday's close, 149.06 two weeks ago; 219.20 the June high far above. On the year the fund is still up 40.9%. A weekly close under 131.65 would say Friday's bounce was only a bounce.
Gold and the coin. Gold 372.52, back above the July low of 364.96; 391.74 the next line above. The bitcoin fund 42.88, under the 44.5 line; bitcoin 75,944, under the 83,000–87,000 zone. A second week above 364.96 would make the July low a floor again; a close back under it would make this week the bounce.
Brazil — after the reset. EWZ 31.98; 43.54 the record close of the year (October 9); the 52-week low close of 30.97 (22 December 2025) is 3.2% below. The real lost about 1.2% more against the dollar this week, to 5.51 per dollar. The fund is +0.7% on the year.
5 · The ETF Portfolio — Global ETFs
Global ETFs — 18 positions · unrealized +0.2% · benchmark Nasdaq-100 · snapshot Nov 10, 2026
| # | Symbol | Name | Weight | Unreal. |
|---|---|---|---|---|
| 1 | VEU | — | 10.6% | +2.0% |
| 2 | QQQM | — | 8.0% | -6.6% |
| 3 | XLK | — | 7.3% | -8.8% |
| 4 | SMHX | — | 7.1% | +20.2% |
| 5 | QTOP | — | 6.0% | +18.9% |
| 6 | INDA | — | 6.0% | -0.2% |
| 7 | TOPT | — | 5.8% | +29.2% |
| 8 | SPMO | — | 5.6% | -17.7% |
| 9 | EWT | — | 5.5% | -5.1% |
| 10 | CIBR | — | 5.5% | +3.9% |
| 11 | FLSW | — | 5.2% | +3.3% |
| 12 | EPOL | — | 5.0% | +8.4% |
| 13 | IBIT | — | 4.8% | +12.8% |
| 14 | WCLD | — | 4.7% | +0.8% |
| 15 | ILF | — | 4.7% | -8.6% |
+ 3 more positions · full per-position cost basis & P&L is C+ subscriber-only.
What we did this week: nothing — a sixteenth consecutive week without a transaction. The July rebuild remains the decision. Saturday's Pulse carries the five books' ledger: AI Build-Out sold three chip-supply lines and bought software and consumer names, and the two option books sold premium into the fall.
The book, marked — the $12,799 week. The fifteen-position book closed Friday at a market value of $305,035 — down $12,799, or 4.03%, from $317,833 at last Friday's closes. Unrealized gains −2.23% on cost, from +1.87%; realized gains unchanged at $42,599; a headline return of about +14.3% on the $250,000 deposited, from about +19.4%. Four of fifteen lines green, eleven red. The weekly (USD) export has not landed yet; this is the engine mark, units times Friday's closes.
What the week paid it — and what it charged. India +6.64% (+$1,268), gold +4.71% (+$670), Switzerland +0.33% (+$59), Latin America +0.03% (+$5) — together $2,002. The charges: the fabless fund −9.37% (−$2,423), Taiwan −11.74% (−$2,374), XLK −8.23% (−$2,218), US momentum −8.70% (−$1,782), Korea −10.39% (−$1,588), QQQM −4.97% (−$1,413), the Nasdaq top-30 line −5.91% (−$1,274); smaller, the US top-20 −$695, VEU −$597, Poland −$244, the bitcoin fund −$192. Four lines — the fabless fund, Taiwan, US tech and Korea — cost $8,603, two thirds of the week's loss.
What we plan to do: nothing on Monday — with the corridor question on the table. Last week the question was Latin America; this week Latin America was flat and the corridor lines cost two thirds of the loss. The fabless fund, Taiwan, XLK and Korea together carry 26.1% of the book, against India and gold at 11.6%. No decision today. The watch-items are the levels above — EWT under 100, EWY against 131.65, VEU against 80.3, the dollar at its high.
6 · What May Go Wrong
One: the moratorium spreads. This week one governor-elect in one state said he wants to stop new data centres, and the companies that build AI lost 12% in a session. If a second state, or the federal level, takes up the same idea, the corridor's customers would have less to build — and Taiwan and Korea sell to those customers.
Two: the December hike arrives with the jobs strong. 165,000 payrolls against 60,000 expected is a reason for the Fed to do what the futures priced before the report. A close back above 5.0% on the ten-year would take away the one support the market got this week from the bonds.
Three: the dollar breaks out. The dollar fund closed level with its high of the year, and the yen is a point and a half from 160. A dollar above its October high with the yen through 160 would press on every Asian market at once — including the ones that rose this week.
Four: the oil fall reverses. Monday's 6.5% drop in Brent came on a signal of talks, not on an agreement. If the talks stall, the week's best tailwind for India, Europe and Japan — a 12% cheaper barrel — goes away as fast as it came.
Five: Thursday was the first day of a leg, not its end. Korea and Taiwan fell 10 to 12% in a week and bounced 4% in New York on Friday. EWY under 131.65 or EWT under 85.88 on a weekly close would say the bounce was a pause inside the fall.
7 · Knowledge Corner
Why the dollar fund moved a day before its home market — reading the week in Tokyo, Seoul and Taipei. A New York-listed country fund such as EWJ (Japan), EWY (Korea) or EWT (Taiwan) holds shares that trade in Asia, but the fund itself trades in New York, after Asia has closed. Its price during the New York day is the market's best guess of where those shares will open the next morning in Asia. On a quiet week the two line up. On a week like this one, the fund can move a whole session before its home market does.
This week, in numbers. On Thursday in New York, Japan's fund fell 6.0%. Tokyo had closed Thursday down only 1.8% on the Nikkei — and on Friday the Nikkei fell 6.0%. The New York fund had priced Friday's Tokyo session on Thursday. On Friday it was flat, because Tokyo had already caught up. Korea and Taiwan show the same shape, larger: their funds fell 11.5 to 13.5% on Thursday, their home markets 3 to 5% that day and 4.5 to 6% on Friday, and then the funds rose 4% in New York on Friday on the jobs report.
| What moved | Thursday 5 Nov | Friday 6 Nov |
|---|---|---|
| Nikkei (Tokyo, yen) | −1.8% | −6.0% |
| Japan fund EWJ (New York, dollars) | −6.0% | 0.0% |
| Kospi (Seoul, won) | −5.3% | −6.0% |
| Korea fund EWY (New York, dollars) | −13.5% | +4.1% |
| Taiex (Taipei, Taiwan dollars) | −3.2% | −4.5% |
| Taiwan fund EWT (New York, dollars) | −11.5% | +3.9% |
What this means for reading a book. Two things. First, a week's figure for a dollar fund and its home index can differ for reasons of time, not of value: over Friday to Friday the Kospi fell 11.7% and the Korea fund 10.4%, the Nikkei 9.3% and the Japan fund 5.0% — partly the currency, partly what each holds, and partly that the fund's week ended with a New York session the home market has not yet traded. Second, Friday's 4% bounce in the Korea and Taiwan funds is a guess about Monday in Seoul and Taipei. The house reads it the way it reads any single session: as a price that the next weekly close confirms or takes back.
8 · Final Words
The chip corridor broke this week. Taiwan and Korea lost 10 to 12 percent, most of it in one New York session on Thursday, when a call for a pause on advanced AI, a Texas governor-elect's moratorium idea and a spending gap at Microsoft landed on the companies that build AI all at once. On Friday Seoul halted trading and Tokyo entered a bear market.
Most of the rest of the world did not follow. India rose almost 7 percent, China's large caps almost 6, Mexico and Spain about 3. Oil fell 12 percent on a signal of talks between Washington and Tehran, and gold rose back above its July low. The US ten-year stayed under 5 percent through a strong jobs report, and France's ten-year now yields less than America's.
The world ex-US index closed under 80 and gave up the summer-low support it held for two weeks. The all-world index closed under its July low. America's lead for the year shrank to a tenth of a point. In our own ladder the builders and the runners fell 10 to 13 percent; the applications and the control group held.
Price is the only truth. This week it said: the year's winner group was sold, and the money went to the markets that own the least of it. The weekly closes — 80.3 on the world ex-US, 152.22 on the all-world, 100 on Taiwan, 131.65 on Korea, 5.0% on the ten-year, 364.96 on gold — will say whether that was a week or a turn.